Audit wrongly states ISP earnings as 32c

I$P Finance hits a new high recently.


ISP Finance earned $40 million for 2016 or earnings per share of 46 cents based on an average of 87 million shares in issue for the year, but the audited statement reported only 32 cents based on a non-existence average of 126.5 million.
The company only issued 105 million shares hence it is not possible for the average to be greater.
The above error along with glaring errors elsewhere in the financial system at large raise the question about the investing public being adequately protected, in spite of regulators in place to do police the system?
Auditors are required to use care and due diligence in undertaking their duties to ensure that the companies they audit maintain proper records that will give a fair view of a company’s profit and financial position. Users of audited statement is not expected to see glaring errors in them. It raises questions about the quality of the audit and the management of the company as well.
Knutsford Express’ audited reports for 2014 and 2015, were filled with errors or questionable treatment of transactions, raising questions about the accuracy of the entire reports.
The earnings per share for 2014 was overstated due to inaccurate computation of the average number of shares issued in 2013, while showing earnings per share of $1.07 for 2014. The income statement erroneously stated by way of note, that “using the weighted average number of shares at end of 2015 would result in earnings being 50 cents for 2014.” Since no new share were issued in 2015 there can be no there is no need for a computation of an average and there can be no change to the earnings for 2014 if the correct average was computed for 2014 in the first place.
The report had further stated “During January 2014, the company raised additional capital of $99,862,700 from its initial public offering of 99,999,003 shares for its enlistment on the Jamaica Stock Exchange Junior Market”. The company in fact issued 26 million bonus shares in 2013 while the public offering was for 20,000,000 ordinary shares, only 4,867,338 new shares were offered by the company while 15,132,662 shares existing shares were sold to the public in the IPO by shareholders. At the time the IPO, 95,132,662 ordinary shares were already issued, the average number of shares should be approximately 60 million rather than 46.8 million used to compute the 2014 EPS, which would have worked out around 83 cents.
According to ISP Finance prospectus, 1n January 2007 the company was incorporated with an authorised share capital of 10,000 ordinary shares at J$1 per share. In June 2007 the company’s authorised share capital was increased to 5,000,000 ordinary shares with all being subscribed for at $1 each.
On February 11, 2016 the company’s authorised share capital was increased to 105,000,000 ordinary shares. Of the 100,000,000 ordinary share increase, 51,017,500 shares were allotted to Gencorp Limited at J$2 per each being the same price at which shares were offered in the IPO. Of the balance just over 48.98 million units were offered to the general public in the IPO.
Cement developments

Carib Cement silos.

There is some amount of excitement in the air, regarding developments in the Jamaican economy. Many investors are interpreting see the change signaling meaningful growth that will lead to increased demand for cement as developers increase their building activities to meet a growing demand for housing and commercial space.
According to Anya Levy of ReMax Elite realtors, demand is extremely high for space to accommodate Business Outsourcing Operations as foreign operations fall in love with the opportunities Jamaica is offering. The problem she states, is that the demand is mostly for 30-60,000 square foot space that is currently is in short supply. In a number of cases, existing commercial space is being converted to meet demand. But it is not only in the commercial arena that there is demand she states.
There are lots of residential units coming on stream. The Millsborough area in Kingston, is slated she says for some major developments for Townhouses in the US$500-600,000 price range. More units are expected that will be similar to the high rise 20 South building going up on South Avenue in Kingston, with another slated to be constructed next door to it. The story does not end there, Levy states that a number of units to be built in the country largest city, will be slated for the short term rental market.
All of this means more demand for cement. Investors expect, the country’s sole cement plant to benefit from the surge in demand that is expected to flow form these new developments as well as the office complexes to be built by Grace Kennedy and the Ministry of foreign affairs in downtown Kingston. Added to the list is the build out of 5,000 hotel rooms in the western side of the island and the many other smaller developments that are planned or started. It may be more than all of that, Levy intimated that she understands that a price increase is on the cards for cement.
Investors are keeping keen eyes on the operations of Caribbean Cement, with great expectations for a major rise in the stock price in 2017 with the company having cut cost and expected to reap increased sales from increased demand in the local economy with increased exports also expected. Against this background the RMOD arm of the Jamaica Stock Exchange wrote to the Company formally on Thursday, March 9, 2017, requesting their response for the reasons of an increase in “contracted” lease payment to Trinidad Cement and the increase in raw materials and consumables costs that rose by 33 percent and seems out of line with the increase in the sales.
The 2015 accounts show that US$22,500,000 (J$2,700,675,000) was due in lease payments in 2016. At an exchange rate of $128.44:US$1 the amount expensed in 2016 was $3,323,635,000 or US$25,876,946. The amount seems to conflict with the reduction by US$22,500,000 of the remaining lease commitment outstanding from US$66,500,000 to US$44,000,000 at the end of 2016.
According to information provided to IC Insider.com, the company who had promised a response by March 20, now indicates that a response is drafted for sign off by management.

Jamaica Broiler’s profit rises strongly

Jamaica Broiler’s profit from continuing operation climbed 25 percent to $721 million up from $579 million for the January quarter and rose just 4 percent to $1.55 billion compared to $1.49 billion for the nine months to January.
Sales of table eggs in Haiti, penetrated the market sharply for the group, with market share nearly doubling to 21 percent of the market up from 13 percent in 2015, the company reported in their latest fiscal quarterly, to January this year.
The strong growth in market share, helped profit in the Caribbean division to climb 161 percent from $115 million to $299 million from continuing operations, but profit in the Jamaican operations fell 20 percent to $1.9 billion while the US division recorded flat profits. Importantly, the Jamaican operations recorded an increase of 24 percent in segment results reversing the negative growth experience in the previous quarters. Gross profit margin for the year to date, fell slightly to 25.8 percent from 25.9 percent in 2016 but grew nicely in the January 2017 quarter, to 26.3 percent from 25.6 percent in the prior year. The improved margin enjoyed in the January quarter over the previous two quarters, translates to increased profit before tax of $200 million per year.
Earnings per share ended at 60 cents for the quarter and $1.29 for the nine months and should end up around $1.70 for the full year, from net profit of $2 billion. The 2018 fiscal profit is preliminarily forecasted by IC Insider at $2.
Revenue for the group climbed 12 percent, to $11.7 billion in the latest quarter, from $9.9 billion and $32 billion compared to $28 billion for the nine months to January. Divisionally, revenues to third parties in the Caribbean division climbed 23 percent from $1.15 billion, the Jamaican operations rose 13 percent to $23.4 billion while the US division recorded an increase of 20 percent to $7.5 billion. Broilers produced positive cash flows of $2.4 billion in the nine months, but ended up with just $303 million more at the end of the period after a net inflows of loan proceeds, paying dividends and capital spend, as the group continues to expand.
The stock traded at $15 on Tuesday on the Jamaica Stock Exchange for a PE of 7.5 based on 2018 estimated earnings and is well below the market average of 12.6.

The TOP 10 no brainer investing

Caribbean Cement highly rated in TOP 10

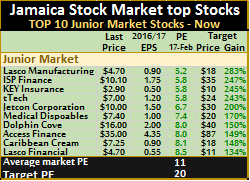
Investing in the TOP 10 junior or main market stocks is a no brainer. These stocks are valued well below the average of the market PE ratio and at an even larger discount to the valuation based on 2016 earnings, around 20 times.
Investors would be well advised to leave emotions out of investment decision making and get and stick to facts. Investors who bought Jamaica Stock Exchange at $14 now and now seeing it trading at $7 after just a few weeks, can attest to that. Even investors at current prices may find that the price could fall further when the company post its first quarter results. Those results will not enjoy the big income generated in the first quarter of 2016, estimated at $110 million, from the transfer of the shares in Desnoes and Geddes and should result in a big fall in profit for the 2017 quarter. Investors also pushed Jamaica Producers to dizzying heights, only to see a marked decline in the share price after, from $22 down to the $16 level and may have cause to worry with 2016 earnings from continuing operations not supporting the high valuation placed on it.
The market appears to be consolidating with a number of 2016 results not sending strong buy signals currently.
Prices of Access Finance, Dolphin Cove and Jetcon Corporation rose during the past week and exited the IC Insider.com’s Top 10 junior market list. These stocks are still within striking distance for the top tier listing but market activity in the coming week could change all of that.
Jetcon rose 22 percent during the week and 522 percent since it was listed in March last year. Entering the top list are Lasco Distributors, the expectations are that the company will benefit from the claim for damages, with much of the funds retained for income generation purposes,Lasco Manufacturing and AMG Packaging as the prices of all three slipped during the week. AMG Packaging approved 5 for 1 stock split, is to be effected on March 10, after much delay.
In the main market of teh Jamaica Stock Exchange, Cable & Wireless reported larger losses than expected in the nine months to December, as a result IC Insider.com revised the forecast for 2017 down to just 10 cents on the assumption of continued strong growth in revenues. The stock fell out of the top list as a result of the earnings down grade. The move by Cable & Wireless let Jamaica Broilers into the list with the stock prices falling to $14.54 on Friday.

Changes for TOP 10 stocks

Gains in the overall market of 20 percent for the year to date have spawned some attractive gains for many stocks, but there is likely to be much more to come for the rest of the year.
The junior market hit new highs during the past week but pulled back quite a bit on Friday, leading to positive and negative price changes. ISP Finance had two sizable trades during the week, the price was up to a new high of $10 but closed the week at $9. Medical Disposables slipped by $1.40 to $6 at the end of the week. Access Finance closed with the bid at $38 compared to $35 last week. Earnings for Lasco Manufacturing and Lasco Financial were reduced following release of the December results and partially accounted for the fall out of the TOP 10 for the two. Lasco Manufacturing sits just below the TOP 10 with a PE of 9 while Lasco Financial is in 16th spot with a PE of 10, both are below the junior market average of 12. The space left by the two, have been filled by General Accident having a PE of 8 and Caribbean Producers valued at a PE of just under 9.
In Main market TOP 10 trading activity during the past week, Jamaica Broilers jumped to $16 from $14.50 to end up be edged out of the top list by Scotia Investments. Strong demand pushed the number 1 main market stock, Cable & Wireless to $1.50 from $1.28 at the start of the week with more news on a potential offer to buy out minority shareholders by Liberty Global, while Caribbean Cement jumped to a new high of $39.60 but closed with just limited selling at $45. The company reported profit of $1.3 billion for 2016 down from $1.55 billion in 2015. In 2016 there were exceptional costs of $807 million while 2015 had one off income of $168 million. The cost savings that will flow from the cut in the labour force will have a positive effect on cost for 2017. Broilers that now sits just below the TOP 10 boast a PE of just 8 compared to an average for the main market of 12 and a potential of 20 for the year.

New record close for juniors – Tuesday

The junior market hit a new record close at the end of trading on Tuesday, with a strong gain of 57.28 points to close at 3,101.51 as 19 securities changed hands.
The market ended with an equal numbers of advancing and declining stocks, after three stocks rose by $1, $4 and $5.10.
At the market’s close, 7 stocks rising while 7 declined while 3 closed at 52 weeks’ highs. Trading ended with 1,021,882 units valued at $6,003,095 passing through the market, compared to 2,642,818 units valued at over $15,747,182, on Monday. At the close 6 stocks had bids higher than their last sale prices and 2 with lower offers, than the last sale, while 1 stock closed at new 52 weeks’ high while one traded at an intraday high.
An average of 53,783 units with an average value of $315,952 traded, compared to of 110,117 units with an average value of $656,133 on the previous trading day. The average volume and value for the month to date ended at 258,010 units and $1,598,653 compared to 272,597 units and $1,690,274 to the previous day. The average volume and value for January, ended at 165,547 units and $884,749.
At the close of trading, CAC 2000 rose 55 cents and closed at $7.50 with 11,000 units changing hands, Caribbean Cream closed trading with 84,589 units at $8.15, after gaining by 15 cents. Caribbean Producers closed trading with 3,466 units being exchanged at $4.50 for a loss of 10 cents, Derrimon Trading ended at $7.20 with 130,736 shares changing hands, Dolphin Cove jumped $4 in trading 2,451 shares, to close at a 52 weeks high of $20. General Accident closed trading with 20,009 shares while falling 2 cents to end at $4.10, Honey Bun gained 50 cents and closed with 30,210 shares changing hands to end at $7.50,

Knutsford Express jumped $5.10 to a new high of $35.

ISP Finance traded 5,000 units to end at a 52 weeks’ high of $10, Jamaican Teas traded 2,018 shares to close at $8. Jetcon Corporation closed trading with a 9 cents loss, with 66,550 shares being exchanged, to end at $10.80, Key Insurance traded 23,923 units, to close with a rise of 11 cents at $3, KLE Group fell 10 cents and ended with 43,319 units changing hands at $2.60. Knutsford Express ended trading just 200 units to close at record $35, after jumping $5.10, Lasco Financial traded 60,000 shares changing hands, to end with a fall of 20 cents at $4.50, Lasco Manufacturing closed with 183,341 units changing hands, with a loss of 5 cents at $4.95, Main Event had 251,120 shares changing hands to close at $4.80. Medical Disposables closed at $7 with 21,446 shares changing hands, Paramount Trading ended with 56,373 shares changing hands at $3.80 and tTech shed 70 cents and closed trading with 26,131 units changing hands at $7.20.

Main Event doubles IPO price

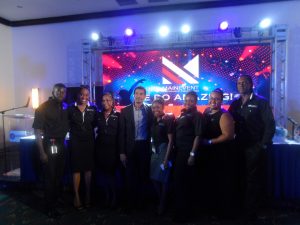
Staff members of Main Event

Shares of main Event Entertainment that issued shares to the public in January at $2 each has more than doubled since.
The stock traded on the first day of listing, the 8th of February, at $2.61 but with just 100 units trading, with the next trade, taking place at $3.70 for 100 units. On Friday February the 10, 15,722,362 units traded with the price ending at $4.70 for a rise of 135 percent. Monday February 13, the stock closed trading at $.81 while trading 537,458 shares. On Tuesday the price slipped back to end at $4.51 as 757,244 shares changed hands. Wednesday saw trading in 696,685 shares be executed at $4.50, on Thursday 592,737 shares traded to close at $4.51 and 420,952 units traded on Friday to close at $4.80, to crown a successful two weeks for the stock that has gained 140 percent from the IPO price.
The stock which IC Insider.com project will earn around 35 cents per share in 2017, now trades at a PE of 14, with the junior market average now around 11.5, the upside from now will be challenging.

Broilers and Kremi now TOP 10ers

The past week saw much changes in the main and junior markets as prices gyrated up and down, for several of the stocks. Some of the highly valued stocks, declined in value as some investors took profit from the sharp rise since the start of 2017, for a number of stocks.
In the TOP 10 junior market selection, Caribbean Flavours (CFF) rose 24 percent to $12.44 during the week and moved out of the list, with the bid at $12.50, making space for Caribbean Cream, now occupying ninth spot. CFF sits just outside the top tier of junior market stocks and could well reenter at the end of next week. ISP Finance moved to a new high of $10.10 on the bid, having traded during the week at record high of $10 and no longer sits on the number 1 spot. Key Insurance suffered a setback with a big 2016 fourth quarter loss of $136 million, coming from increased insurance claim provisioning of $433 million for the quarter and $1 billion for the full year. Hopefully, that is now behind them, clearing the way for 2017 to deliver what the company seems capable of doing. tTech pulled back in price, to sit at a more comfortable $7, after some selling came in for the stock. Access Financial climbed to a new all-time high of $35, helped by strong nine months results and lack of supply of stocks for sale.
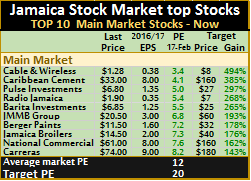
Scotia Investments climbed to $41.19 during the week, from $38 the previous week and exited the TOP 10 main market stocks. The move made space for Jamaica Broilers that lost value during the past week, falling from $16.25 at the start of the week, down to a more attractive $14.50, with an increased forecast of $2 earnings per share for the 2018 fiscal year starting May, this year. The week saw more interest in Radio Jamaica and JMMB Group, the latter trading at $23 on Friday, but closed lower by the end of trading, helped by net profit rising 55 percent to $2.68 billion, for the nine months to December last year. Earnings per share for the nine months came out at $1.63 and 39 cents for the December quarter.

Scary data pushing some stocks

Overvalued Cargo Handlers, rated a buy by Barita.

Investors have been acting strangely of late, buying a few stocks at inflated valuation that are well ahead of anything in the market. There are just no logical explanations for it. It is downright dangerous for some investors, who seem set to get badly burnt.
IC Insider.com attempted to get an understanding of this unusual development of scary PE ratios. One possible clue came from two seasoned investors. One bought shares in Jamaica Stock Exchange (JSE) on the assumption that the PE was only 4, he was unaware that the earnings per share, last reported by the company, was not adjusted for the 5 to 1 stock split. The other investors pointed out that Cargo Handlers was selected by Barita Investments as the top junior market stock for 2017. That is a strange selection as research going back to the early years of the JSE, shows that only around 20 percent of top 10 stocks ends in the top 10 in the subsequent year, in very bullish periods, even less do so. A look at Barita’s stock market update chart, shows the Cargo Handlers having a PE of just 11.47 with earnings of $2.18, but the earnings is well ahead of the 43 cents the company reported for 2016. The PE for the stock, based on 2016 earnings is near 60 and 46

Jamaica Producers is one of the company’s that investors seem to be pushing the price, based on pre-bonus earnings.

times, IC Insider’s 2017 projection, making it the richest priced stock on the market.
Cargo Handlers may not be the sole stock that investors seem to be ignoring the effect of stock split on values. Barita shows JSE with a PE of 12.5 with earnings of $1.02, thankfully there is no recommendation for this one. Jamaica Producers is shown with a PE of 6.52 from earnings of $3.02, with a buy recommendation. Producers earnings are at best inflated with one off items, with them earning at the above level highly unlikely, as such the stock boast a PE of 40 times 2017 earnings. Pan Jam Investment is shown with earnings per share of $3.97 and a PE of 10.08. The only problem is that Pan Jam earnings for the nine months from continuing operations for 2016, is in the order of $1.92 making reaching the Barita’s earnings forecast challenging.
When the quarterly reports start coming in with adjusted earnings, it could be a huge disappointment and wake up call for some investors. It just does not seem smart for investors to be buying stocks that are valued well ahead of the market and expect to beat the market, unless there are huge increased profits down the road.

10 TOP Junior market stocks for 2017

tTech, one of ICI Insider.com top selections for 2017.

With just over one month of 2017 slipping by, the junior market is up more than 14 percent in a relative short time. Market movement delivered some stunning gains with five stocks rising between 54 percent and 77 percent up to Friday.
The PE ratio, the best measure of valuing stocks, for this market is at 10.5 times 2017 estimated earnings and 16 times 2016, with 9 stocks selling above this level, including Cargo Handlers selling at a rich 51 times 2016 and 40 times 2017 earnings. The top 10 stocks have PE ratios for 2017 between 4.3 and 7.4 times estimated earnings compared to the average of 10.5. Nine socks are priced higher than the average.
Technical indicators show the junior markets braking through major resistance levels at 2,600 points and seem poised to reach new highs around 3,400 points before the next level of resistance is met, that is 15 percent away from the close on Friday.
What makes junior market stocks attractive, is their size, relative to the majority of main market stocks and their ability to grow at a much faster pace, from existing business or expansion into new ventures, delivering superior profits and greater growth in the stock prices.
ISP Finance has very limited supply of stocks available for sale, this should ensure that the price should surge to match seller and buyers. The company could see a sharp rise in profits if the $145 million raised in a bond issue last year is invested in new loans. Based on its interim results to September last year, interest income works out at 100 percent per annum. At these levels and with the infusion of cash from the bond and the cash to flow from profits, the stock could enjoy and explosive blast, if they are able to put the funds into profitable loans.
tTech revenues for this technology company grew strongly by 34.3 percent for the nine months to September and stronger 43 percent for the September quarter, with very good demand for its services. A negative is that cost has been growing just as fast, as they add personnel to service customers need. At September 2016, the company had 33 full-time employees compared to 24 at the same period in 2015. While staffing grew 57 percent between September 2015 and September 2016, the growth in the September quarter was only 7 percent over the June quarter. The sharp growth in cost slowed growth in profits, from a relatively small base. The slowdown in staffing in the September quarter, should allow more revenues to flow into profits in 2017 onwards.

Lasco Manufacturing

Lasco Manufacturing has enjoyed very strong demand for its new drinks, resulting in major expansion of the factory. Total revenue to September 2016 was $4 billion, an increase of 28 percent over the same period last year, resulting from increased production volumes brought to market, as part of the expansion of the manufacturing plant.
The company indicated that production at the liquid plant continues to grow steadily. The plan is for increase capacity to meet strong market demand for the iCool line of beverages, by ramping up production with the installation of additional equipment by the end of the financial year. The new Dry Plant at White Marl is fully operational together with the existing Red Hills Road Dry Plant. New products will be introduced by the end of 2016 to enhance the product line which is projected to continue to realize significant sales and profits, the company stated.
Main Event is the latest public issue to hit the market. The issue was heavily oversubscribed. The price is set to enjoy a big bounce when it list this week Wednesday with the PE ratio of just 7, based on 2016 earnings and less based on estimated 2017 profit. The funds raised will be used to expand its operation, including setting up a branch in Montego Bay.
Medical Disposables focussed on increasing the product line it represents in 2016, reflecting in a strong 38 percent sales growth for the first six months of the financial year, but at lower margins. Increased cost associated with the expanded sales has so far kept profit from growing a great deal in 2016. That should change in 2017, as sales growth, out pace cost increases. With the focus on rapidly expanding products and sales, this is clearly a stock for investors to keep a keen eye on.

Caribbean Flavours traded at $9.50 on the junior market last week

Caribbean Flavours is a company with much promise for growth, with potential for increased exports and new product lines for sale, locally and with the Caribbean region. The stock is selling below many other in the junior market currently, and the price has room to run, having fallen to $9.50 with the confusion investors faced, with the acquisition majority shares by Derrimon Trading.
Access Financial is undervalued based on a number of factors but the stock is extremely scarce. Earnings for the fiscal year ending March, should be in the order of $2.80 and based on this and with 10 junior market companies selling at more than 17 times 2016 earnings, the stock should be trading over $45. As the company makes profit, most of the funds are reinvested in its operation to expand loans, this in turn fuels strong increased profit. Access seems set to generate earnings of $4.35 per share for the 2018 fiscal year, which will push the price much higher than its current level.
Key Insurance nine months profit ended at $66 million compared to $68 million for the 2015 period and seems set to reach $120 million for the full year, for earnings per share of 35 cents. The company should benefit from the lowering of restriction on investments that insurance companies could undertake which should free up funds for more profitable investments as the companies see fit. Investing in general insurance companies can be riskier than for many other companies, in the short term.

Jetcon Corporation revenues enjoyed strong growth for 1st nine months of 2016

Jetcon Corporationlisted at $2.25 in 2016, is shot to $10.50 for a rise of 366 percent. An announcement of a stock split and dividend gave the stock added push as investors bought more shares at higher prices. The company more than doubled profits to September last year over results for 2015 for the same period. Jetcon benefitted from the capital injection of the public share issue. It helped boosts inventory, and in turn grew sales by 61 percent to $610 million for the nine months to September and 86 percent for the September quarter. The publicity from the listing seems to have enhance the company’s image in the minds of potential customers which has also helped sales. The trend of increased sales for the past two years suggest that sales growth may continue to be strong in 2017 and should be helped by the continued attractive financing terms available in the market, strengthening of the economy and reduction in PAYE that some workers will enjoy, when the tax threshold increases in April thus increasing take home pay.
Dolphin Cove was the darling of the investing public when the company was listed but seems to have lost its lustre as profit growth slowed sharply. With continued growth in the tourism industry and more cruise ships coming to the country, the company should get a boost in revenues and earnings for this undervalued stock.

Persons associated with this article may have an interest in the companies commented on.