Express Catering abusing small shareholders


Express Catering generated US$7.3 million in cash flow and paid interest of $2.5 million on borrowings used to fund loans to the parent company.  The loan to the parent jumped US$7.7 million during the year to US$24.6 million or J$4 billion.
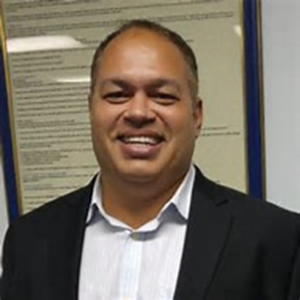
Ian Dear, Managing Director of Express Catering

The just-released audited accounts do not indicate the company’s ability to recover the debt, which has been rising for years and exceeds shareholders’ equity of US$13 million.
At the same time, minority shareholders bear the cost of the US$15 million loan borrowed to help fund the parent company, without a cent being passed on to the parent. This is very poor governance practice. The practice opens the company to tax charges for the loss of interest income, as the loan is not an arm’s-length transaction. Worse, it opens the company to legal action from minority shareholders for suppressing minority.

Shareholders get hit in a number of ways. The cost of lending the parent company reduces profits, resulting in a lower stock price and lower dividends, with the possibility that some or all of the debt may have to be written off.
During the year, the company suffered a reduction in revenues and profit, mostly caused by a drop in visitor arrivals through Sangster International Airport since November last year.
Revenues fell from US$25.9 million to US$18.9 million, while profit declined to US$2.68 million from US$3.76 million after interest costs of US$2.5 million, roughly the same as in 2025.
Starbucks is one of Express Catering brands.

Express Catering needs to regularise lending to the parent company, with a set date for repayment and compensation for interest at market rates, back to the inception of listing. It also needs to show, in future financials, the ability to recover the debt, with a charge being placed on the assets of the parent company.
Going forward, airport departures have been recovering and are now down around 20 percent from 2025 levels, with expectations that the numbers will continue improving into 2027 as most of the hotels that were closed reopen.
Carib Cement post impressive results


Jamaica’s sole cement producer, Caribbean Cement Company, delivered another quarter of bumper profit, with a 396 percent surge after tax to $2.7 billion from just $544 million in 2025 for the quarter ending in June. Profit rose significantly by 126 percent to $5.7 billion after tax for the half year, from just $$2.54 billion for the same period in 2025.

The outstanding profit results emanated from a 14.5 percent rise in revenues to $9.31 billion in the 2026 second quarter, from $8.13 billion in 2025 and increased 13.7 percent or the half year, to $18.57 billion from $16.33 billion in 2025.
Gross profit performance resulted in a “gross profit margin of 50.2 percent, compared with 32.7 percent in the prior year period. The improvement reflects stronger operating efficiency and more favourable production environment compared with 2025, when the Company incurred substantial costs associated with its planned maintenance shutdown, including approximately $920 million in additional related expenditure and imported cement to maintain market supply,” the company stated in its quarterly report commentary to shareholders.

The solid profit performance resulted in operating cash flow of $7.25 billion, compared with $4.25 billion in the prior year. Cash and cash equivalents stood at $18.55 billion as at June 2026.
Net Asset value came in at $45, with earnings per share ending at $3.17 for the June quarter and $6.75 for the six months to June. ICInsider.com maintains full year forecast at $14 per share, with the PE based on it of 8.2, which is well below the average of 12 for most main market stocks, an indication of potential gains ahead.

Profit jumps 18% for Grace


GraceKennedy delivered an 18 percent jump in after tax profit of $2.4 billion for the June 2026 quarter, from a 6.26 percent increase in revenues of $45.6 billion. For the half year, profits rose 11.76 percent to $4.75 billion from a 4.6 percent rise in revenues to $93 billion.

Grace delivered Interest and Other income along with its share of results of associates and joint ventures amounting to $2.17 billion, up 21 percent over the $1.79 billion in the second quarter in 2025. For the six months to June, the Group delivered an increase of 6.6 percent to $3.8 billion from $3.567 billion in 2025.

The Group took a $1.4 billion hit in other comprehensive income for the quarter and $1.7 billion for the half-year. These resulted mainly from re-measurement of post-employment benefit obligations and foreign exchange loss adjustments.
Earnings per share came in at $2.41 for the quarter and $4.78 for the half year, putting it on track for $10 for the year. Net asset value per share amounts to $95.86 at the end of June. The stock closed trading on Wednesday at $74 with a PE of 7.4 times 2026 earnings and a good long term buy. The group declared a dividend of 70 cents per share, payable in September.

Profit surges 159% at Paramount Trading


Profit for the third quarter ending February, this year jumped 159 percent to $24 million from $9.3 million at Paramount Trading, from a 5.7 percent rise in revenues for the quarter to $433 million from $409 million. Net profit jumped a solid 380 percent to $110 million from a loss of $39 million for the nine months period, from a mere 5.5 percent rise in revenues to $1.26 billion compared with $1.2 billion for the same period in the previous year.

Gross profit margin increased to 43 percent in the third quarter from 37.87 percent in the corresponding period in 2025 and for the year to date, rose to 43.85 percent from 35.15 percent in 2025, resulting in gross profit climbing 20.4 percent to $187 million in the February 2026 quarter from $155 million in 2025 and for the year to date it rose sharply by 31.7 percent to $554 million from $421 million, growing sharply to $32 million after tax compared to just $9.3 million in the third quarter of 2025.
Administrative, selling and distribution expenses rose 8.5 percent to $137 million in the third quarter from $126 million in the 2025 period and increased a mere 2 percent to $384 million in the nine months, from $378 million, as selling and Distribution expenses declined 58 percent to $7.2 million in the nine months ended February, from $17 million in 2025. Finance cost declined in the quarter to $20 million from $23 million in the same quarter in the prior year and from $66 million to $64 million for the nine months.
The operations generated Gross cash flow of $137 million, after working capital consumed $59 million and ended cash funds of $85 million at the end of the period and investments of $96 million.
Current assets ended the period at $1.45 billion inclusive of receivables of $516 million, cash and bank balances of $86 million. Current liabilities ended the period at $563 million and Net current assets of $887 million.

Shareholders’ equity close the third quarter amounts with $1.14 billion with long term borrowings amounting to $469 million and short-term borrowings of $84 million.
Earnings per share for the quarter was 1.6 cents and 7.2 for the nine months. IC Insider.com projects earnings of 10 cents per share for the current 2026 fiscal year, giving it a PE of 10.8 times based on the last traded price of $1.08 on the Jamaica Stock Exchange Junior Market. With the market average of 14, the stocks is undervalued. The big question, can the company keep on building on this platform? Recent history, leaves that as the real big question.
The company paid a dividend of 2.6 cents per ordinary share in December 2025.

Profit triples at Berger Paints


Berger Paints, Jamaica’s major paint manufacturer concluded their 2026 annual general meeting this past Friday, with a new chairman at the helm. Management informed shareholders of the demolition of fourth quarter profits due to the damage caused by Hurricane Melissa. According the General Manager Dwaine Williams the company was on target to deliver one of the best results with the hurricane snatching it away.

Berger Paints directors at the recently held AGM right to left are the chairman Ian Mitchell, Dwaine Williams General Manager, former chairman, Christian Llanos, Chamika Cuffy, Financial Controller, Michael Fennel , OJ, Nicholas Maclean. In attendance but not at the head table are Milton Samuda and Jacqueline Sharp.

He went on to point out that the improved 2025 first quarter results, suggesting that the new-year is on track for a surge in profits. According to Williams, the first quarter has some demand as a result of the rebuilding out west, but suggests that increased demand is expected as the rebuilding matures. The rebuilding is seeing demand for steel, cement and other construction materials, but after that, paints will be demanded he stated.

The directors in reporting on the first quarter performance stated,” demand strengthened progressively through the quarter as rebuilding activity accelerated. The Company met that demand with high service levels and dependable supply.”
The new year has started well for the company with a 180 percent jump in the March quarter, at Berger Paints to $31 million, from just $11 million after corporate taxes in first quarter 2025. Profit before tax came in at $38 million, up 123 percent from $17 million in the prior year. The profit was partially fueled by a sharp jump in other income to $24 million, from a gain of just $7 million, in 2025, partially reflecting a $20 million swing from a foreign exchange loss of $13 million in 2025 to a gain of $7 million in the current period. Taxation rose 19 percent to $7 million form $6 million in 2025.
The 2026 outcome on the surface appears impressive, but falls well short of the profit of $48 million in 2024. For the first quarter this year, revenues climbed 16 percent to $890 million, from $769 million in first quarter of 2025, just slightly less than the solid 20 percent growth in the third quarter last year over the 2024 gross inflows.

Shareholders in attendance at Berger Paints 2026 Annual General Meeting held on Friday, May 15 at the Courtyard- Marriott Hotel

At the nine-month stage in 2025, net profit amounted to $18 million on revenues of $2.4 billion, compared to $9 million on revenues of $2.3 billion in the same period of 2024. Hurricane Melissa struck Jamaica at the end of October last year, the start of peak painting season, which traditionally accounts for around 90 percent of Berger’s annual profits, suggesting profit in the region of $200 million for the full year, but for the devastating effect on the fourth quarter performance.

Raw materials cost climbed 11 percent to $423 million for the quarter from: $381 million in 2025. Gross margin before manufacturing costs, climbed to 54 percent from 50 percent, in the 2025 first quarter and reflects gains from ongoing capita investments. in this regard the company stated that they plan to spend $100 million in the current year on capital expenediture.. Manufacturing expenses increased by 31 percent to $17 million from $13 million in 2025. Employee expense rose 11 percent to $185 million from $166 million in 2025. Other operating expenses rose 31 percent to $226 million from $172 million in the prior year. Depreciation amounted to $26 million, up 7 percent from $24 million.

First quarter2026 earnings per share came in at 14 cents, up from 5 cents in 2025 first quarter. IC Insider.com projects the full year’s earnings at $1.35 on the assumption there will no major disruption to business during the year. The stock closed at $5.35 on May 15, 2026, with a P/E ratio of just 4, based on the current years projected earnings and 214.3 million shares outstanding. Net asset value per share is $5.13, just below the last traded stock price.

The operations generated was $63 million in Cash flow during the quarter with movements in working capital resulting in a net outflow of $69 million and ending with cash on hand amounting to $200 million and reflecting an improvement over $165 million at the end of March 2025.
Inventories grew 29 percent to $920 million, but was lower than the position at the end of the 2025 at $1.23 billion. Receivables declined 17 percent to $741 million from $891 million at the end of March 2025. Current liabilities ended the period at $1.25 billion slightly up on the $1.19 billion at the end of March 2025.
Shareholders’ equity stood at $1.10 billion up from $1.18 billion year ago.

Profit explosion at Transjamaican


Profit surged a solid 46 percent at Jamaica’s premier toll operators –Transjamaican Highway to US$13.2 million, for the quarter to March this year, compared to US$9.1 million in 2025. The vastly improved profit performance flowed from revenues that jumped an almost incredible 29 percent to US$29 million, from US$22.5 million for the 2025 first quarter.

Management indicated that “increased commuter traffic across the network was one area that contributed to the growth in revenues.

While revenues were climbing sharply, helped by US$3.5 million earned from the Mandeville leg of the highway, which came on stream during the period, costs remained subdued, with a 9 percent rise to US$12.3 million from $11.3 million in 2025. Taxation rose from US$3 million to US$3.55 million.

The company reported earnings per share of 0.0106 US cents, equivalent to 16.74 Jamaican cents per share, which puts the full year earnings at 67 Jamaican cents for the year. At this level of earnings, the stock is priced around 11 times current year’s profit.

Following the end of the quarter, a dividend of US$13 million, equivalent to all the profit generated in the quarter, was paid in April, an increase of 30 percent over US$10 million paid in the first half of 2025.

Profits surged 53% at Carib Cement


Profits surged 52.8 percent at Jamaica’s sole manufacturer of cement, Caribbean Cement Company, resulting from 13 percent rise in revenues of $9.3 billion, compared with $8.2 billion in the first quarter of 2025.

“This strong performance was driven primarily by higher sales volumes, reflecting sustained demand in the domestic market associated with ongoing recovery activities following Hurricane Melissa,” management stated.

The improved profit position was helped by a significant gross profit margin improvement of 51 percent, compared with 46% in the corresponding period of 2025. “This improvement was driven by operational efficiencies achieved at the production facility, and management’s continued focus on cost discipline. Following the successful completion of the expansion project in 2025, improved margins, cost stability, and reduced unit production costs compared to last year,” managed stated.

Operating expenses, including administrative, selling and distribution expenses, amounted to $865 million, an increase of 5 percent from $825 million in the prior year.

Earnings per share for the quarter were $3.58, an increase of $1.24 compared to the same period in 2025, and suggest full year earnings of around $14. With the stock price trading at $101.50 on Wednesday, the PE is 7.3, well below the market average.

Net cash flows generated from operating activities ended at $4.2 billion, reflecting an improvement of $1.9 billion over the 2025 first quarter and resulted in cash and cash equivalents of $15.7 billion.  

Profit jumps 36% at Supreme Ventures


Jamaica’s leading gambling company, Supreme Ventures, delivered a robust performance for the March 2026 quarter, with net profit jumping a solid 36 percent after tax, to $703 million, up from $514 million for the first quarter of 2025, resulting in earnings per share of 26.67 cents.

Gaming income rose 4.6 percent to $14.46 billion, with gross profit improving to $3.30 billion, with revenues up from $13.8 billion in 2025 and gross profit of $3.16 billion. Direct costs increased 10.5 percent to $11.1 billion, compared with $10.67 billion in 2025, well above the revenue gains.

Selling, general and administrative costs climbed marginally to $2.31 billion from $2.22 billion in 2025 in the quarter.
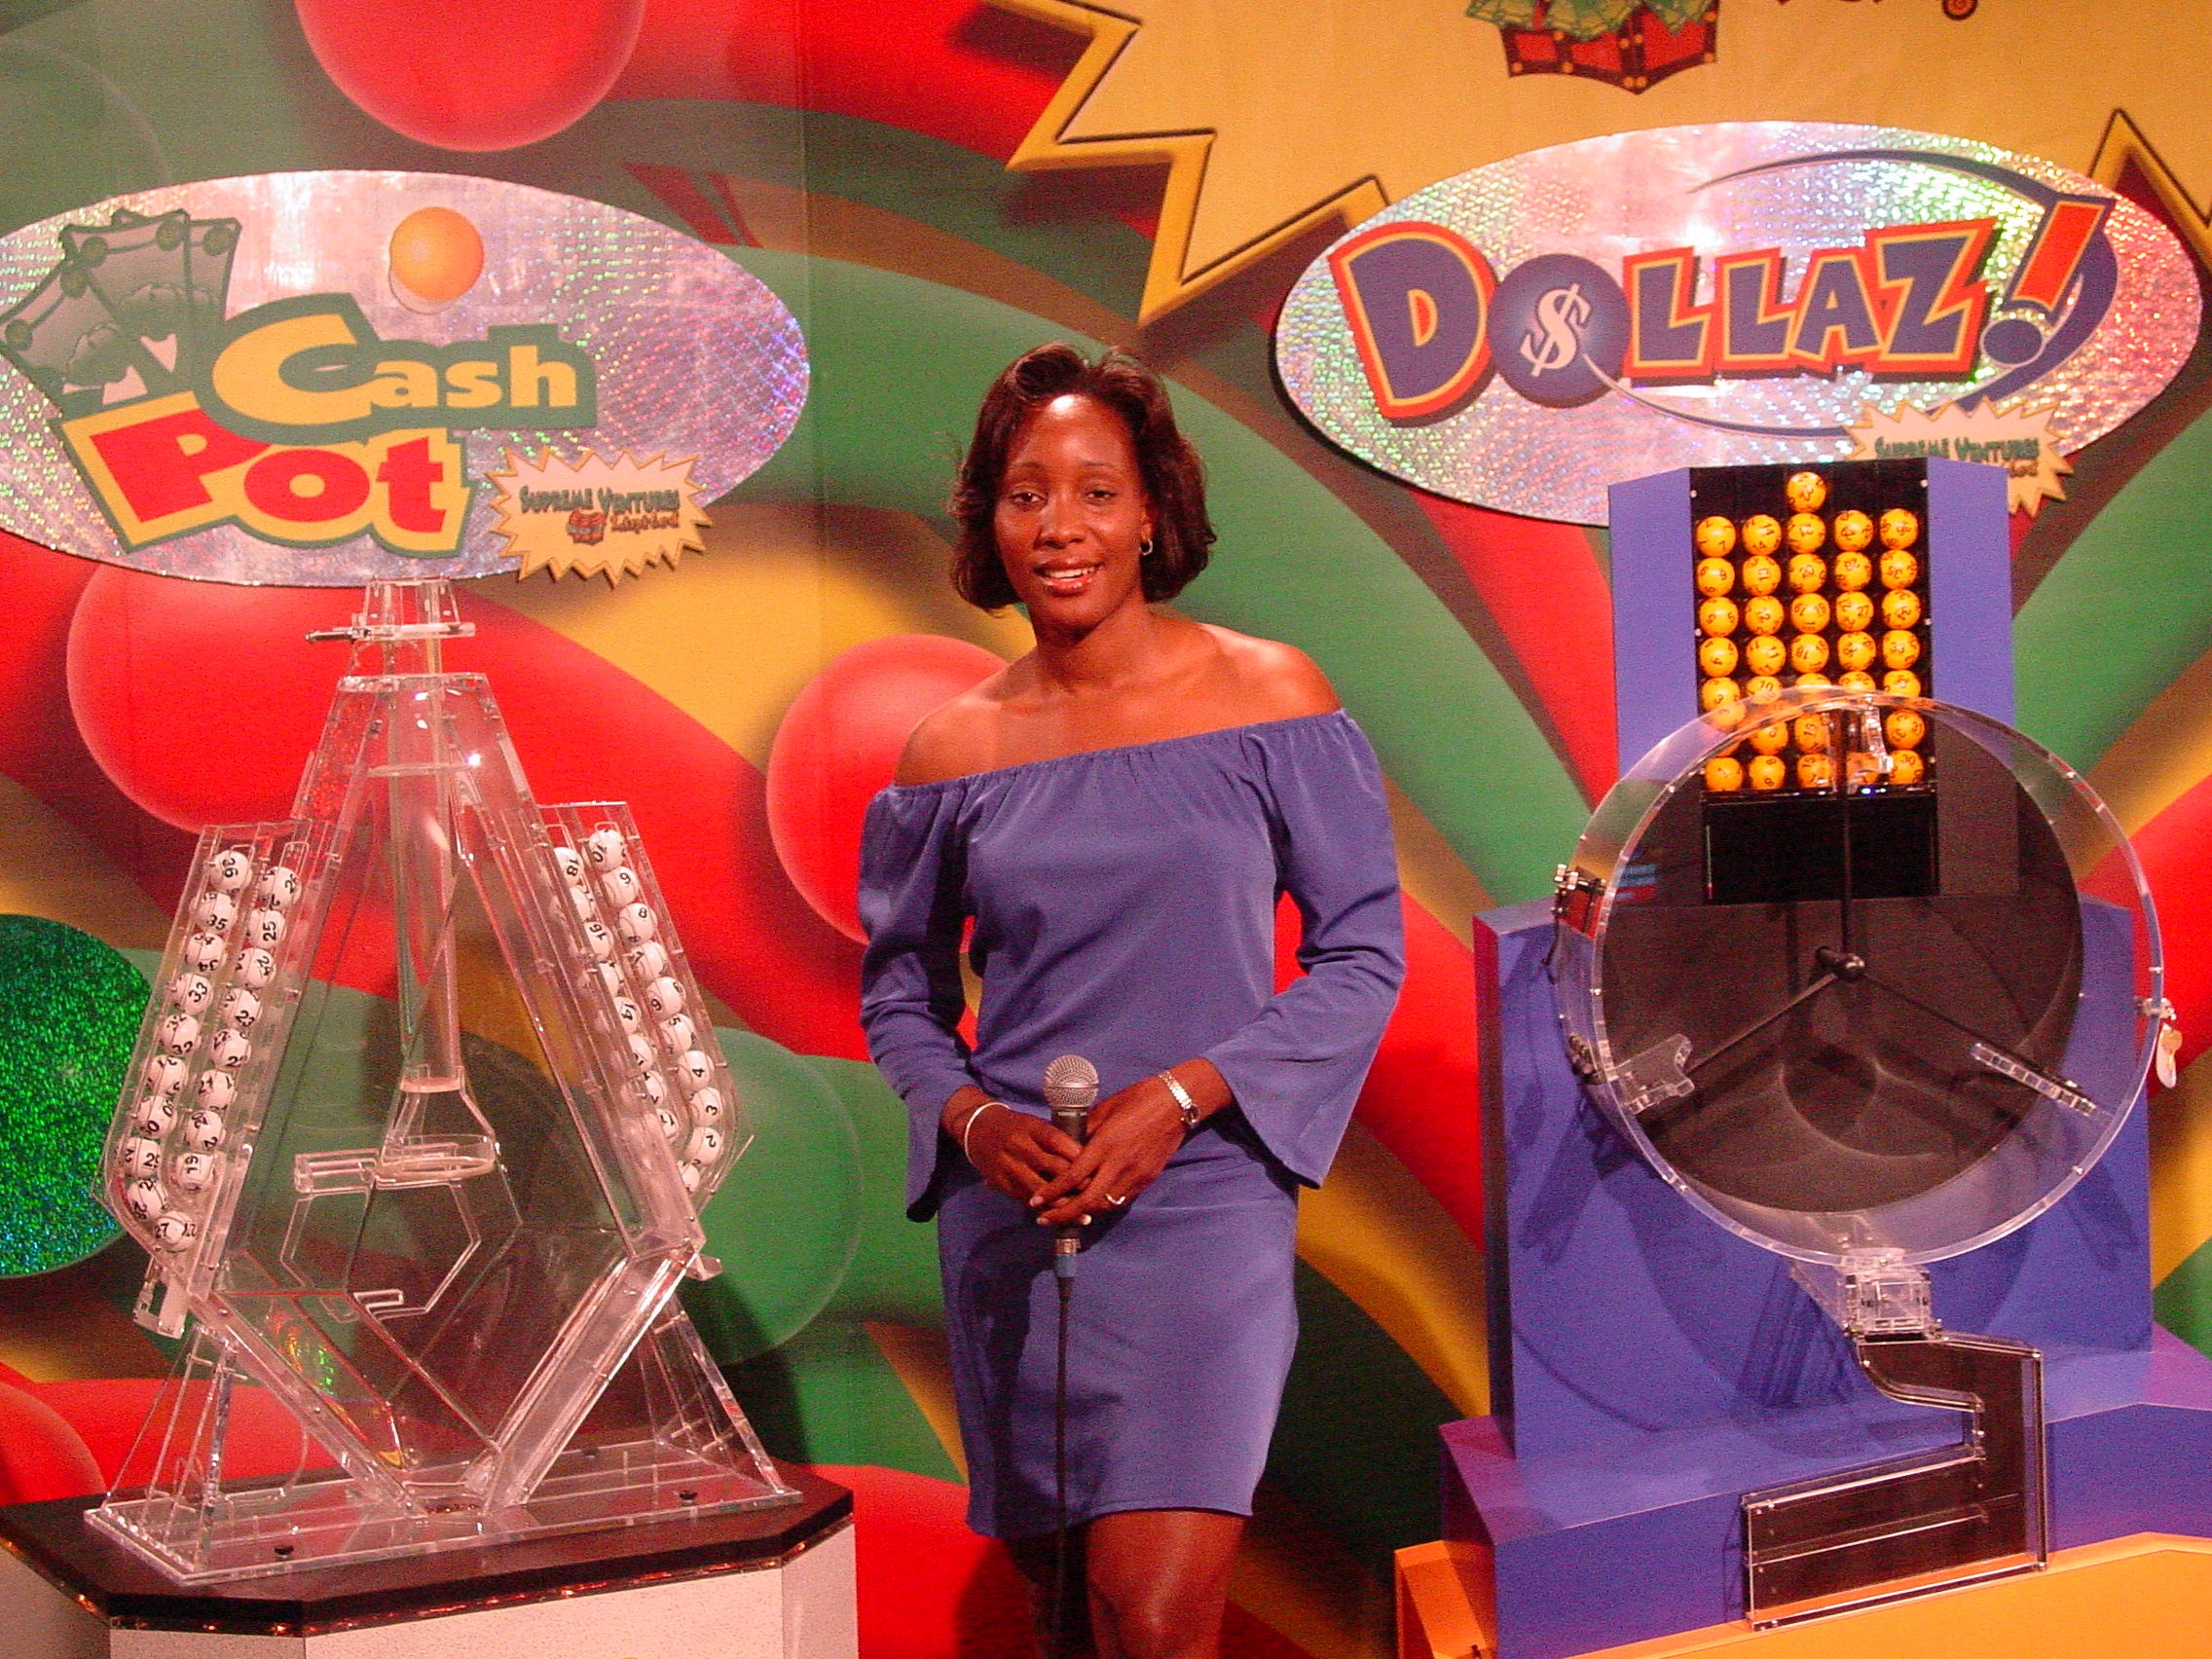
Segment results show Lottery bringing in revenues of $6 billion, marginally ahead of the $5.94 billion in 2025, delivering segment results of $1.4 billion, up from $1.34 billion in 2025. Sports betting raked in $4.43 billion compared to $4.25 billion, resulting in segment results of $517 million versus $509 million. Pin Code generated income of $3.86 billion, up 8.4 percent from $3.56 billion in the first quarter last year, segment results of $110 million versus $98 million.

The operations had positive cash flows of $632 million up from $290 million in 2025, resulting in Cash and cash equivalents of $1.77 billion, an increase from $1.2 billion at the end March 2025. The group also has investments of $2.2 billion.

Management states that “the Group remained compliant with all financial covenants and that the hurricane caused an estimated $1.6 billion reduction in gross ticket sales and had a $100 million negative impact on net profit. Nevertheless, terminal recovery in the lottery segment reached 98%, and targeted measures, such as deploying additional terminals and using generators and Starlink connectivity, supported ongoing operations.” 
The company confirmed a dividend of 22.89 cents per share, totaling $60.4 million, to be paid to shareholders on Thursday, July 2, to those on record at May 7, 2026. Dividends of $77.28 million were paid during the March quarter. 

The shares are listed on the Jamaica Stock Exchange and  last traded at $15.57 on Wednesday.

Stationery & Office Supplies drops in 2025


A six percent rise in revenues in the first nine months of 2025 melted down to a modest 1.3 percent for Stationery & Office Supplies (SOS) for the year, to $1,866 million, over $1.843 billion recorded in 2024, following the negative impact on sales caused by the impact of Hurricane Melissa in the last quarter.

While the top line held up well, supported by a 50 percent surge in export sales across the Caribbean region and strong growth from the EVOLVE furniture line, the bottom line came under considerable pressure, partially affected by the impact from the hurricane and lower margins from exports.

Stationery & Office Supplies hit a record high on Friday.

Stationary & Office Supplies – Montego Bay office.

Gross profit for the year came in at $953 million, down 5.5 percent from $1.01 billion in the prior year. The gross profit margin narrowed from 54.7 percent to 51.1 percent, reflecting higher shipping and input costs that the company chose to absorb, as well as the lower-margin profile of the growing export business. Cost of sales rose to $913 million from $835 million, a 9.4 percent increase that meaningfully outpaced revenue growth.
Administrative and general expenses climbed 7.2 percent to $612 million, driven largely by a 9.5 percent increase in staff costs as the workforce expanded from 162 to 170 employees and management remuneration that rose to $142 million. Selling and promotional expenses were essentially flat at $154 million, while depreciation and amortisation held steady at $45 million. Total expenses for the year reached $828 million compared to $785 million in 2024, a 5.5 percent increase.
Operating profit fell sharply to $137 million from $228 million in 2024, a decline of approximately 40 percent. Net finance income of $11 million and foreign exchange gains of $10 million, resulted in pre-tax profit for the year of $160 million, down 35 percent from $247 million in the prior year. The effective tax rate was approximately 17.4 percent, after accounting for a 50 percent tax remission as a Junior Market listed company. Net profit after tax amounts to $133 million, well below $223 million in 2024, a fall of 40 percent.

Earnings per share for the full year was 6 cents, down from 10 cents in 2024. The company paid dividends of $45 million during the year, representing 2 cents per share, the first dividend distribution since 2023.

Fourth Quarter 2025
The fourth quarter was severely disrupted by Hurricane Melissa, with Revenues declining by 14 percent to $377 million, from $437 million in the same period of 2024. Gross profit collapsed by around 50 percent to roughly $105 million as storm-related inventory losses at the Montego Bay warehouse and reduced trading activity weighed heavily on results. Expenses for the quarter declined 11 percent to approximately $183 million as the company curtailed discretionary spending. The net result was a pre-tax loss of approximately $6 million for the quarter, compared to a pre-tax profit of $15 million in Q4 2024, a swing of $21 million. The quarterly EPS was aa loss of 0.2 cents.

Segment Performance
The Furniture segment remained the powerhouse of the business, generating revenues of $1.35 billion in 2025, up 9.6 percent from $1.23 billion in 2024, with a gross profit of $760 million and a segment gross margin of 56.4 percent. The Book segment, representing the SEEK brand, saw revenues decline sharply to $76 million from $106 million, with gross profit falling to just $6 million from $27 million, reflecting both hurricane disruption and the pre-commissioning stage of the new factory. Stationery and other supplies posted revenues of $441 million, down 13 percent from $506 million, generating a gross profit of $187 million at a margin of 42.4 percent.
The company had an official opening for the Seek factory a week ago, with reports that it elicited some fresh orders and increased interest in the products that are manufactured. As the leading player in the office and stationery business smaller players who may want to exit the business will most likely look to them to be acquired. This is an ever present possibility, so investors should not be surprised if there are such developments in the future that could push revenues and profit.

Balance Sheet
urrent assets at year end stood at $1.06 billion, with current liabilities of only $358 million, with a net current asset of $701 million, a modest improvement from $687 million in 2024. Cash and equivalents rose 15 percent to $382 million from $332 million. Inventories grew 4.5 percent to $416 million. Shareholders‘ equity increased to $1.64 billion from $1.55 billion, with a net asset value per share of 73 cents. Long-term borrowings, totalled $17 million, down from $27 million.
The company generated gross operating cash of $201 million, after favourable working capital movements and tax and interest payments, net operating cash flow was $215 million, ahead of the $187 million generated in 2024. Capital expenditure consumed $114 million, primarily on the SEEK factory build-out, motor vehicles and computer equipment. Financing outflows of $69 million included the dividend payment, lease repayments and loan servicing. The net increase in cash for the year was $50 million.
ICInsider.com projects earnings per share for 2026 at 15 cents at a PE ratio of 12.3 times earnings at $1.85 the stock last traded at on Thursday. This compares to the Junior Market average of 15.6 currently. At the close of trading on Thursday supply of the stock for sale has dried up with only 7 offers of 149,000 share for sale. Watch this stock that could deliver a 50 percent gain or more for the year.

SOS SEEK’s factory opening March 27


Stationery and Office Supplies will officially opens its newly completed SEEK book manufacturing and storage facility, on March 27. A landmark investment amounting to over $150 million, significantly expands the company’s production capacity as it enters a new phase of expansion and growth in its book production business.
Stationery & Office Supplies hit a record high on Friday.

Stationary & Office Supplies – Montego Bay office.

The new facility, located at 26 Collins Green Avenue, and close to the Stationery and Office Supplies offices on Beechwood Avenue, encompasses 8,000 square feet of dedicated manufacturing and storage space, built at a cost exceeding $150 million. The expansion increases SEEK’s operational floor space by 300 percent, providing the room needed to scale production, house new machinery, and build inventory buffers to support both local and regional demand. Management indicates that the plant has the capacity to supply Jamaica with the total needs of exercise books with capacity for export.

Following headwinds in the Books segment in 2025, revenues declined to $76 million from $106 million in 2024, due problems with machinery and disruption to sales due to damage caused by Hurricane Melissa in the western section of the island.

Stationery & Office Supplies new book making operation.

With new machinery now tested and staff fully trained, the company is already seeing a meaningful step-up in production volumes and improved unit economics as the facility scales up. The investment also aligns with SOS’s broader sustainability agenda in broadening the portfolio of products for sales locally and in the wider Caribbean.
Reduction in Seek sales during the year helped in keeping revenues for SOS to $23 million more than the $1.84 billion in 2024, with 2025 ending at $1.87 billion. Stationery and other items also contributed less revenues than in 2024, with sales slipping $65 million from $506 million to just $441 million in 2025.