Express Catering generated US$7.3 million in cash flow and paid interest of $2.5 million on borrowings used to fund loans to the parent company. The loan to the parent jumped US$7.7 million during the year to US$24.6 million or J$4 billion.
Ian Dear, Managing Director of Express Catering
The just-released audited accounts do not indicate the company’s ability to recover the debt, which has been rising for years and exceeds shareholders’ equity of US$13 million.
At the same time, minority shareholders bear the cost of the US$15 million loan borrowed to help fund the parent company, without a cent being passed on to the parent. This is very poor governance practice. The practice opens the company to tax charges for the loss of interest income, as the loan is not an arm’s-length transaction. Worse, it opens the company to legal action from minority shareholders for suppressing minority.
Shareholders get hit in a number of ways. The cost of lending the parent company reduces profits, resulting in a lower stock price and lower dividends, with the possibility that some or all of the debt may have to be written off.
During the year, the company suffered a reduction in revenues and profit, mostly caused by a drop in visitor arrivals through Sangster International Airport since November last year.
Revenues fell from US$25.9 million to US$18.9 million, while profit declined to US$2.68 million from US$3.76 million after interest costs of US$2.5 million, roughly the same as in 2025.
Starbucks is one of Express Catering brands.
Express Catering needs to regularise lending to the parent company, with a set date for repayment and compensation for interest at market rates, back to the inception of listing. It also needs to show, in future financials, the ability to recover the debt, with a charge being placed on the assets of the parent company.
Going forward, airport departures have been recovering and are now down around 20 percent from 2025 levels, with expectations that the numbers will continue improving into 2027 as most of the hotels that were closed reopen.
 The outstanding profit results emanated from a 14.5 percent rise in revenues to $9.31 billion in the 2026 second quarter, from $8.13 billion in 2025 and increased 13.7 percent or the half year, to $18.57 billion from $16.33 billion in 2025.
 Grace delivered Interest and Other income along with its share of results of associates and joint ventures amounting to $2.17 billion, up 21 percent over the $1.79 billion in the second quarter in 2025. For the six months to June, the Group delivered an increase of 6.6 percent to $3.8 billion from $3.567 billion in 2025.
 The group reports that, based on the unanimous recommendation of a committee of independent directors of the board of directors of SGJL, it has entered into a definitive arrangement agreement with its majority shareholder, Scotiabank Caribbean Holdings Limited to take SGJL private whereby, among other things, all of the issued and outstanding shares of SGJL that SCHL does not currently own will be repurchased for $61.50 in cash per share, subject to court approval as well as the approval of SGJL’s minority shareholders.
 Gross profit margin increased to 43 percent in the third quarter from 37.87 percent in the corresponding period in 2025 and for the year to date, rose to 43.85 percent from 35.15 percent in 2025, resulting in gross profit climbing 20.4 percent to $187 million in the February 2026 quarter from $155 million in 2025 and for the year to date it rose sharply by 31.7 percent to $554 million from $421 million, growing sharply to $32 million after tax compared to just $9.3 million in the third quarter of 2025.
 Shareholders’ equity close the third quarter amounts with $1.14 billion with long term borrowings amounting to $469 million and short-term borrowings of $84 million.


 Management indicated that “increased commuter traffic across the network was one area that contributed to the growth in revenues.
 “This strong performance was driven primarily by higher sales volumes, reflecting sustained demand in the domestic market associated with ongoing recovery activities following Hurricane Melissa,” management stated.
 Selling, general and administrative costs climbed marginally to $2.31 billion from $2.22 billion in 2025 in the quarter.
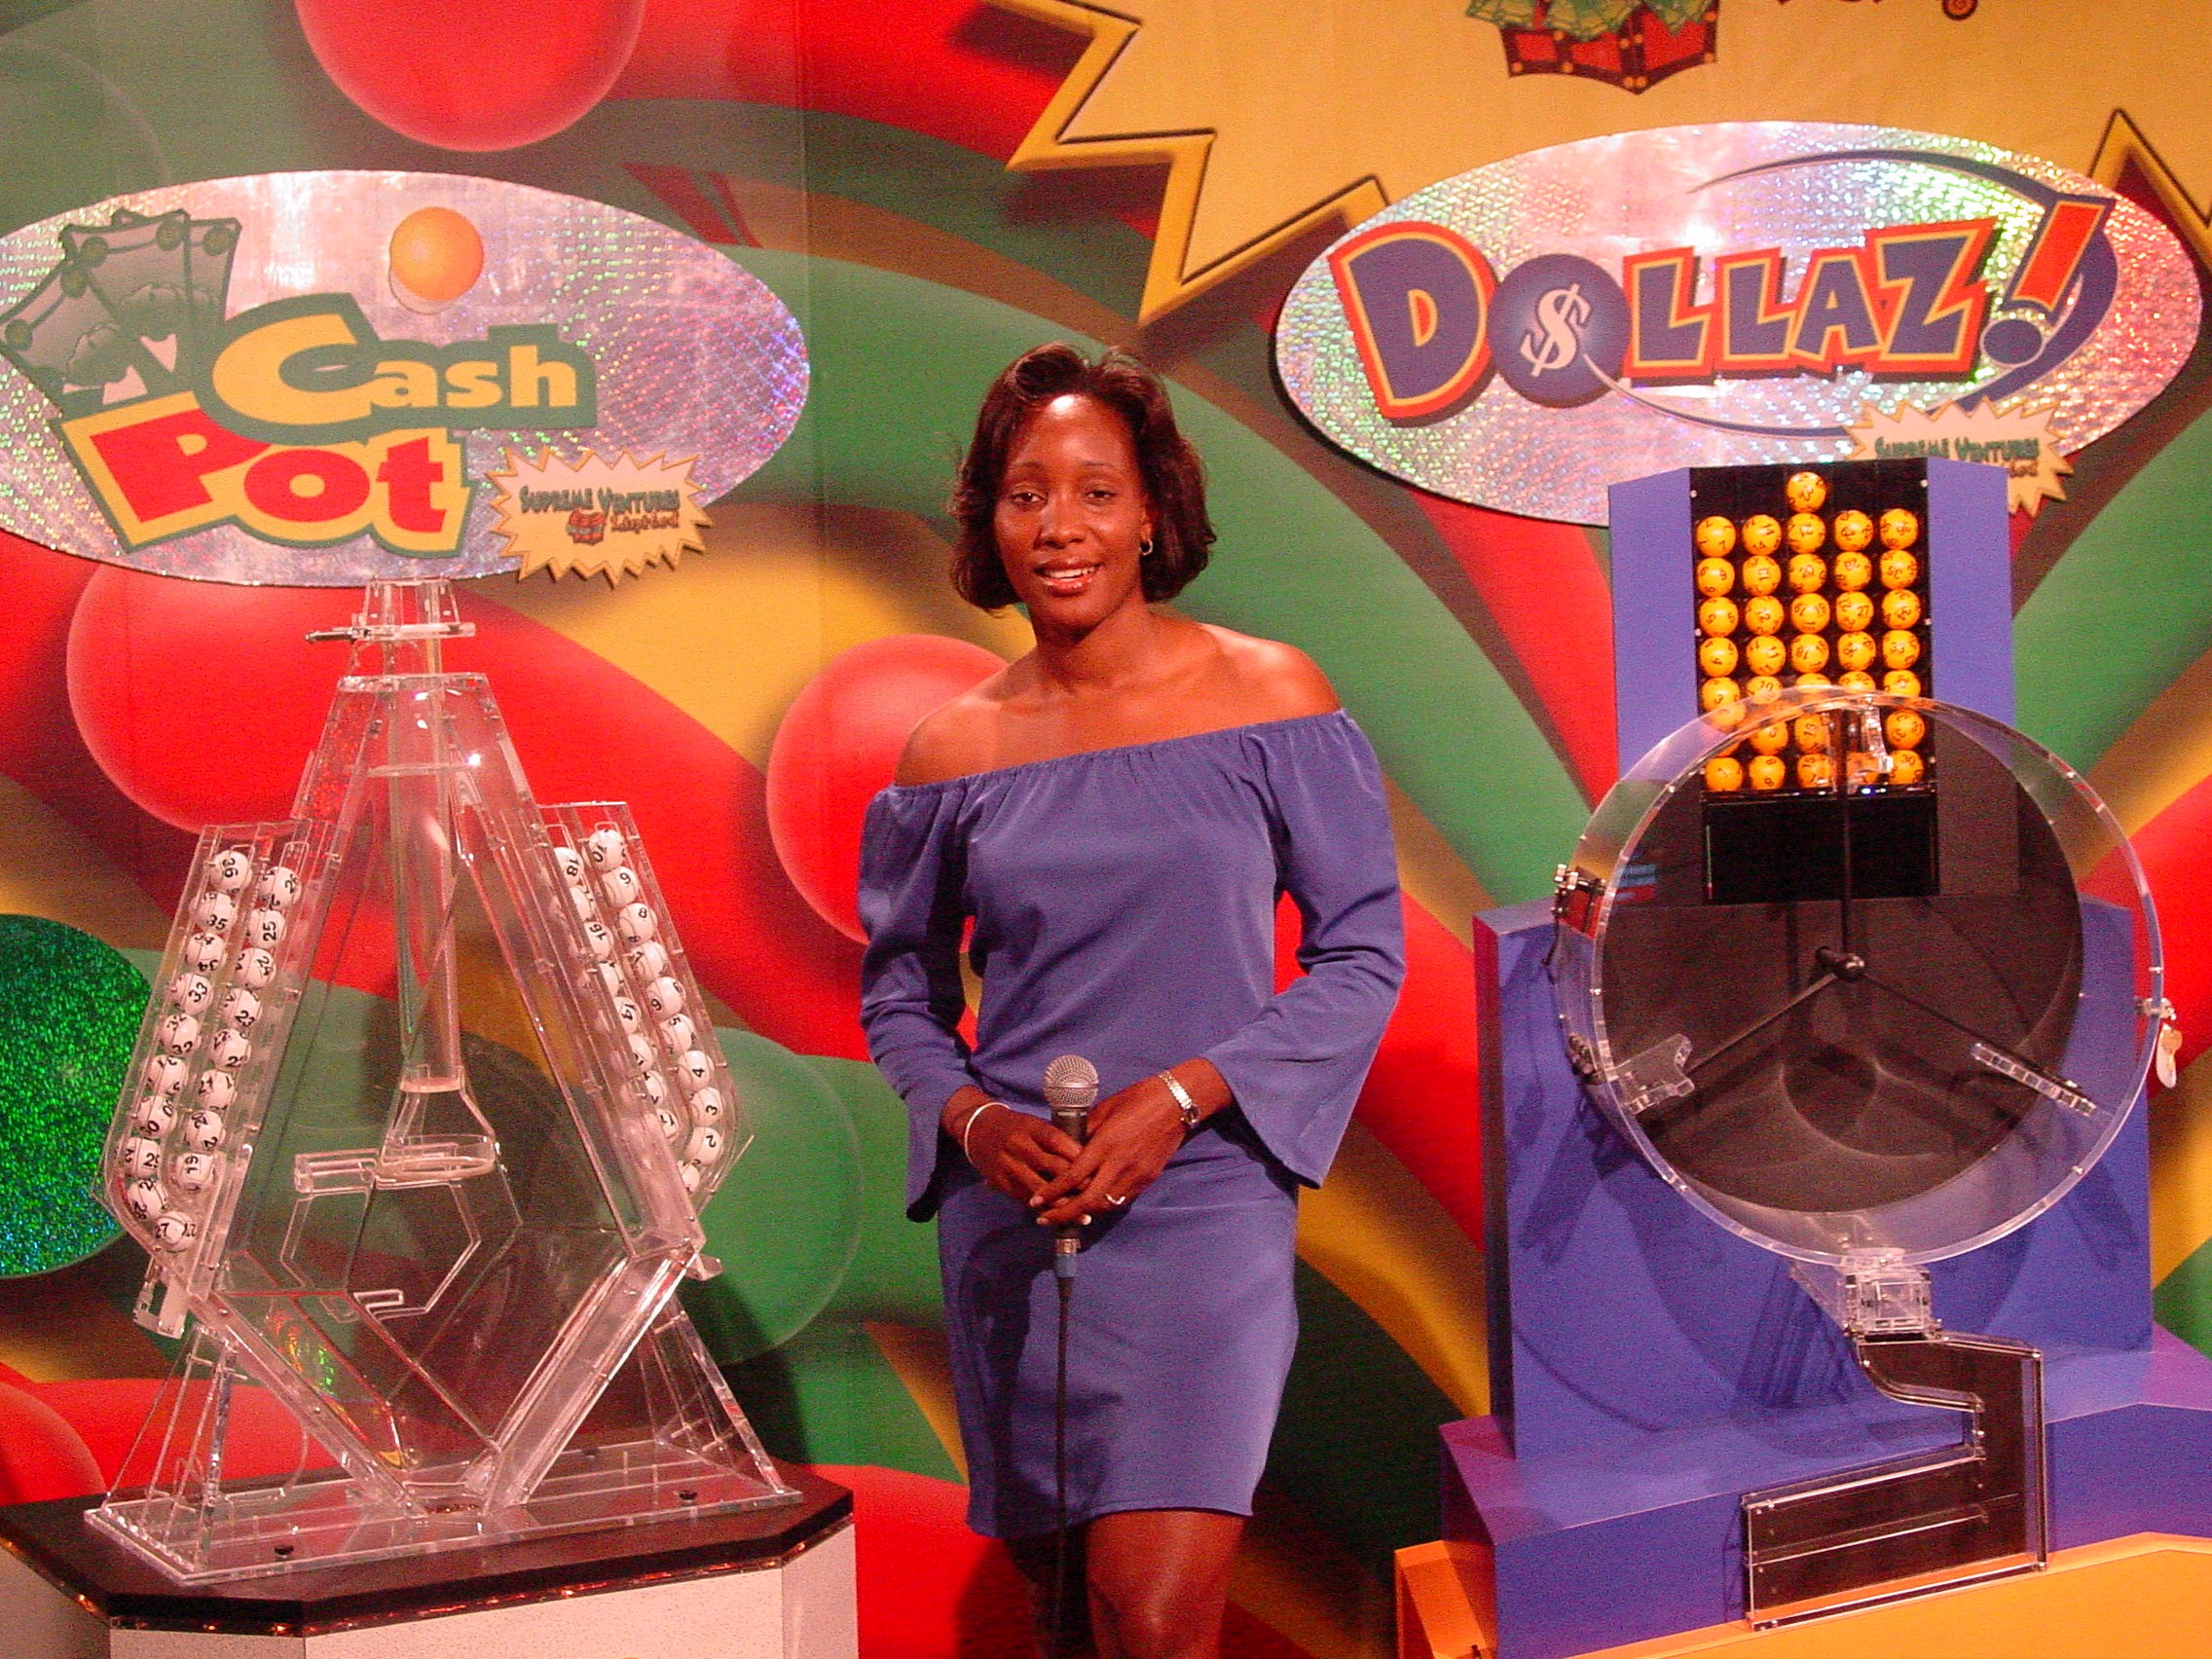 Management states that “the Group remained compliant with all financial covenants and that the hurricane caused an estimated $1.6 billion reduction in gross ticket sales and had a $100 million negative impact on net profit. Nevertheless, terminal recovery in the lottery segment reached 98%, and targeted measures, such as deploying additional terminals and using generators and Starlink connectivity, supported ongoing operations.”
 A number of companies suffered from a loss in revenues during the final quarter of 2026, following the passage of the hurricane. Others faced continued revenue pressure from the critical tourist sector that recorded sharp decline in visitor arrivals in the first quarter of 2026 and probably for a longer period.
 Underperformers stock or the quarter was In Junior Market was Kintyre Holdings, which fell 46 percent, having ran up to 70 cents at the end up 2026, faced heavy selling in the quarter, as buyers reduced the price they were prepared to buy the stock at. Iron Rock Insurance declined by 29 percent, with investors concerned about the impact the hurricane would have on underwriting margin as well as concerns on the investment portfolio performance with lower interest rates in the country. Paramount Trading dropped 19 percent, reflecting some profit taking after the stock ran up in 2025 based on improved half year results but much lower second quarter profits compared with the first quarter as sales suffered with the interruption caused by Hurricane Melissa. Main Event shed 16 percent, with Hurricane Melissa shattering an already pressured operation that was passing through a period of reduced revenues resulting in a small loss for 2025 coming out of a year of uncertain economic outturn leading up to the general elections in 2025.