 NCB Financial Group broke out of a triangle pattern over the past week, as the price hit a record $81 on Friday. The technical indicator is signaling a strong buy signal and a huge movement ahead, with the group reporting strong gains in profit for 2017 over 2016. The stock has traded in a very narrow band in the $70 region for a number of months as it consolidated ahead a the big move it seems ready to make with limited supply coming into the market. Results for the none months to June suggest earnings in excess of $8 per share for 2017 with more to come in the new year starting in October. IC Insider.com placed the stock two weeks now on a market watch list.
NCB breaks out & heading higher
July 30, 2017 by
JSE Q2 profit jumps 41% one to watch
July 24, 2017 by
 A sharp fall of $92 million in Exchange Operations’ revenue for the half year to June, resulted in the segment results falling $110 million to $41 million but a 41 percent rise in Depository Services’ revenues to $156 million and 20 percent in Trustee Services’ income to $137 million resulted in the segments’ profit rising by 83 percent and 17 percent to $82 million and $75 million respectively.
The improved performance in the newer services of the Jamaica Stock Exchange saw second quarter results increasing over the performance of the first quarter with a rise of 41 percent in profit after tax compared to a decline in the first quarter versus the strong 2016 first quarter. The gains in the June quarter reduced the fall in profits for the by percent to $102 million, compared with the corresponding financial period last year of $158 million. The six months performance resulted in earnings per share of 15 cents, the June quarter returned 6 cents per share.
Total Expenses grew 19 percent over the 2016 quarter to $167 million and 13 percent for the six months to $330 million. Major increases were experienced in professional fees which included cost for defending claims against an employee and advertising and marketing.
“It is expected that for the remaining quarters there will be more companies listing their securities on the exchange and a positive movement in fee income due to the expected increase in trustee Services clientele,” the chairman, Ian McNaughton and Managing Director Marlene Street Forrest stated in a release to shareholders accompanying the financials.
The balance sheet shows assets of $1.24 billion, cash funds of $517 million and stockholder’s equity of $891 million.
IC insider.com is forecasting earnings per share of 35 cents for 2017. The stock last traded on the Market of the Jamaica Stock Exchange at $6.
Lasco Financial setting for profit explosion
July 24, 2017 by
Lasco Financial enjoyed decent gains in profit for Q1
Revenues at Lasco Financial Services jumped 22.4 percent for first quarter over the similar 2016 period to reach $319 million for an increase of $58.5 million, but importantly trading income climbed 31 percent to $303 million.
According to Managing Director, Jacinth Hall-Tracey “this result represents year over year growth of and is being driven by our strategy of expansion which began in the previous financial year”.
Profit before taxation, moved from $69.7 million in 2016 to $81 million, a 16.5 percent increase with profit after tax increasing 15.8 percent to $66.9 million, compared with the corresponding financial period and resulting in earnings per share of 5.4 cents.
Total Expenses grew 24.6 percent over the 2016 quarter to $238 million with Selling and Promotion cost rising by 31 percent. The increase was “largely driven by increases in Selling and Promotion as we continue to push the LASCO Money consumer facing brand name. This brand has resonated well with our customers and has enabled us to fully explain all our services. Previously, most customers were only aware of our Cambio and MoneyGram services. This brand awareness has been paying off in the increased transactions in all our locations as our customers embrace our more friendly community brand,” Hall-Tracey advised shareholders in a release accompanying the financials.
In the previous financial year, Lasco began the implementation of a strategy to expand the Loans Division by adding a Business Loans Unit. This expansion gave rise to several new loan offices as well as an increase in administrative and sales staff. Increased focus on lending, resulted in 70 percent growth in the loan portfolio that should move the portfolio in the region of $340 million. At the end of March loans amounted to $282 million up 43 percent over the $197 million due at the end of March 2016, no figures for loan is disclosed in the quarterly.
The balance sheet shows assets of $1.54 billion, cash funds of $574 million and stockholder’s equity of $1.22 billion.
IC insider.com is forecasting earnings per share of 30 cents for 2018 and should go on to about double in 2019. Lasco Financial last traded on the Junior Market of the Jamaica Stock Exchange at $3.55.
Express Catering trading fiasco
July 21, 2017 by
Ian Dear, Managing Director of Express Catering
The Jamaica Stock Exchange indicated that the maximum price Express Catering could trade at on Friday was $1.86 which came about from a 15 percent average, of the price that triggered the circuit breaker which is $1.75 and the IPO price of $1.50.
Had the first trade, taken place at $1.95 it would have shut down trading in the stock for an hour, but that price would have stood, being 30 percent above the IPO price.
Regardless, investors placed a large number of bids to acquire the stock which was heavily oversubscribed, when the shares were issued to the public. The attached picture shows the bids above $2.20 at the close which are expected to be cancelled, with the closing bids limited to $2 which is the indicative starting price on Monday. That price will determine the maximum price the stock can trade at on Monday. Something must be wrong if investors can place orders into the system only to see them manually cancelled by the exchange after trading ends. This development is public relations and bad news for the exchange, but not many persons seem to care.
The circuit breaker rule put in place to try and prevent wild daily movements in a stock prices seems to have out lived its life. It is not working well with new listings as it is preventing orderly trading in most new listings in the early days of trading.
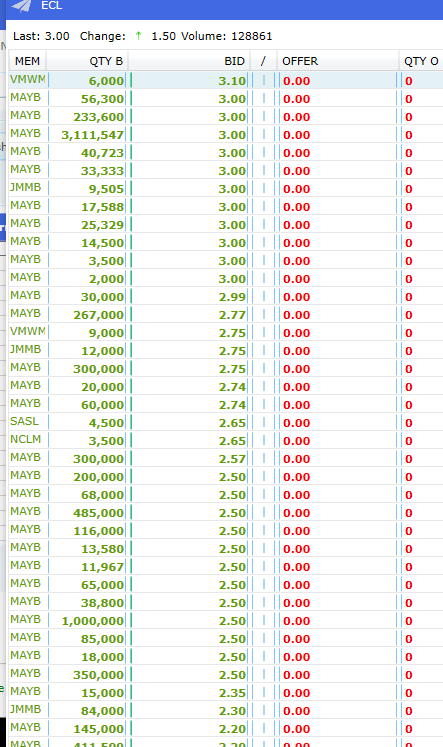
All the above orders amounting millions of shares in Express Catering will be cancelled after trading on Friday
According to an extract sent by the Jamaica Stock Exchange the Circuit Breaker Rule states that “No stock should trade +/-15% from the close price or the effective close price at the opening of the market. The effective close price is determined whenever the closing bid is greater than the close price or whenever the closing ask is less than the close price. Use the closing bid as the effective close price, if the value is greater than the close price or use the closing ask as the effective close price, if the value is less than the close price. However, during the day if the Circuit Breaker is triggered for a security, the trades at prices outside of the original prescribed band for the security will be disallowed for an hour to allow for the release of market news and a cool down period. The price of the trade that triggered the Circuit Breaker should not be +/-15% outside of the original prescribed price band. After the hour has passed the security will be released for trading within a new prescribed price band based on the new reference price, which is a simple average of the trigger price and the close price. The new reference price will be used to determine the trade range for the remainder of the day. The stock will not be allowed to trade +/- 15% of the new reference price.”
If it is were conceded that there is need for a daily price limit, the above rules have been made more complex than needs be the case. There is no logic in limiting one stock to trade at a 30 percent above the last traded price or indicative price and another to be limited to a lesser amount on the same day because an investor buys a stock at 30 percent above the prior days last price another at 15.1 percent above it which limits the trading for the rest of the day to less than 30 percent in the latter case. The new rules that were approved by the stock exchange in 2014 made no reference to a limit to the bid or offer that can be made during the day, exchange personnel have decided amongst themselves to improperly invoke the additional change that limits trading unnecessarily. The stock exchange should make good sense prevail and allow the above rules to be implemented fully as stated without the introduction of rules that the updated regulations do not include and from all indications were not signed off by the stock exchange council, went the change was submitted for approval. If that is done, it would remove the nonsense that now prevails in the Express Catering trading, with a huge line up of bids above $2 that are slated to be cancelled after trading today.
Another miniscule IPO allocation
July 18, 2017 by
 The general public ended up collecting a miniscule amount of shares in Express Catering recent public offering of shares with the first 12,000 shares being allocated in with the balance in excess allocated approximately 4.57 percent.
Mayberry Investments, brokers to Express Catering public issue, advised that a total of 1,270 applications valued at approximately $1,197,204,000 were received for 327.5 million shares valued at $491,250,000 that were on offer. Mayberry states that 1,237 applications valued at $634,599,000 were received for the public pool, approximately 13 times the value of $48,937,000 on offer in the public pool.
Shares allocated for Company Reserves Shares, Mayberry Reserved Shares and Key Partner Reserved applications were allocated in full. Mayberry states that “the company will endeavour to return refunds within 10 working days after the closing date.
SOS solidly BUY RATED
July 6, 2017 by
 Stationery and Office Supplies reported earnings of 26 cents per share for 2016 and IC Insider.com forecast 40 cents pretax for the current year from just over $90 million in pretax profit, a near doubling in profits over the $53 million reported in 2016.
Revenues increased 11 percent in 2013, just 5 percent in next year, 14 percent in 2015 and 12 percent in 2016 and 20 percent for the first six months of 2017, hitting $702 million in 2016 and seems on target to get to around $850 million for 2017.
Pre-tax Profit in 2016, pre-tax profits jumped 279.5 percent to end at $53 million compared to only $14 million in 2015, and $8 million in 2014.
Improvement in the Company’s revenues has been attributable to organic expansion driven by the achievement of deeper penetration in the market for the Company’s products and services but inflation and devaluation of the Jamaican dollar versus the United States currency would also play roles. Improved profit and cash flow generated in the last two years helped to fund increased inventory making more choices available to customers and that is reflected in a noticeable pick-up in sales. The Company has expanded its product offerings, adding to the list of brands it distributes and venturing into manufacturing its own brands of furniture – Image and Torch.
 Gross profit as a percentage of sales was a strong 48 percent in 2016, coming from 43 percent in 2015 and 44.55 percent in 2014. Lower cost of sales led to an improved gross profit position of $339 million in 2016, which 26.09 percent increase over that earned in 2015 and 10 percent more in 2015 over 2014.
As at the 31 March 2017, SOS reported first quarter revenues of $220 million, 20.7 percent more than the $182 million reported in the corresponding period for 2016. Cost of sales as a proportion of revenue remained in line with the FY 2016 representing 50.66 percent of total revenue; this percentage was however slightly higher than the 48.75 percent for all of 2016. The company reported pretax profits of $30 million compared to $29.5 million in Q1 2016. A number of factors impacted the 2016 results that resulted in higher profits than would normally be the case as such the 2017 profit are better than the figures suggest. In effect the 2016 first quarter could be around $20 million from normal ongoing operation.
Gross profit for the three month period ended 31 March 2017 was $108.64 million or 16.2 percent more than the $93 million reported in 2016. SOS also reported an increase in administrative costs of 21 percent to $53 million and selling expenses climbed 37.5 percent to $18 million.
 Total assets were valued at J$498 million at the March this year comprising current assets of $243 million. Inventories stood at $117 million, receivables $93 million and cash of J$12 million. Total liabilities amounted to J$231 million, with trade and other payables of J$78 million. Shareholders equity stood at $270 million or $1.35 per share.
The company will benefit greatly from listing and sales to climb above recent levels form the increased exposure that will be gained from listing on an ongoing basis as well as the increased working capital that will provide additional choices for customers and help fuel increased sales. IC Insider.com accords the stock BUY RATED with the price to rise sharply after the stock list.
This SOS IPO who are the connections?
July 4, 2017 by
 The McDaniel family owned Stationery and Office Supplies (SOS) after 50 years of serving their more than 3,000 clients, are heading in a new direction. No longer content to hug up 100 percent of the company the family is now are embarking enjoining the public to ride on with them to the next level.
In furtherance of this new thrust SOS is now seeking to list on the Jamaica Stock Exchange Junior Market with an initial public offering 50,024,100 ordinary shares, to raise approximately $95,048,200 before expenses. The issue is inclusive of 22,500,000 reserved shares some of which are being sold at $1.60 for staff, with the rest being made available to the general public at $2 per share the offer opening at 9 on July 19th, with the closing set for 4:30 P.M. on July 26th.
The Company reported pretax profits of $53 million in 2016, from sales of $702 million, with earnings of 26.5 cents per share, resulting in a PE of 7.5 before tax. Earnings for 2017 is estimated at around 40 cents on a pretax basis at an attractive PE of 5.6 times 2017 earnings. Revenues for the first six months of 2017, are up almost 20 percent over the similar period in 2016. Office furnishing and fixtures account for approximately 60 percent of sales revenues and stationery and office supplies for 40 percent management advised IC Insider.com.
 The Company estimates that the expenses in the invitation will not exceed $12,000,000 inclusive of General Consumption Tax and an expanded marketing and publicity spend, expected to not only drive interest in the IPO but create greater awareness about the company. and its products.
Minimum raise| The Company needs to raise at least $50,000,000 to qualify for listing on the Junior Market. If that amount is not achieved an application will not be made for the shares to be admitted to the Junior Market and all funds will be returned to the persons who made them.
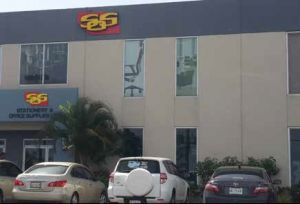
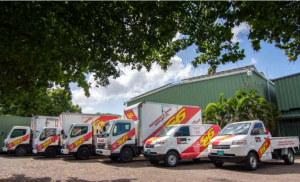
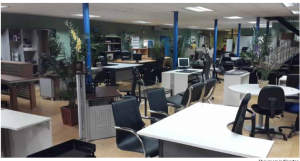
History| The Company started business in July 1965 under the guidance of Richard Hing, George Hew and David McDaniel. In 1970, the Company became wholly owned by the McDaniel family when all of the issued ordinary shares were acquired by David and Marjorie McDaniel. The Company now operates out of a 35,000 square feet warehouse, office and showroom on Beechwood Avenue in Kingston and a 3,000 square feet location in Montego Bay that houses 1,200 square feet of office and showroom space and a 1,800 square foot warehousing facility supported by a staff complement of sixteen. The Head Office currently employs eighty-three team members. Eleven delivery vehicles are operated by the company including trucks, which support delivery to customers.
Products|The Company now sells and market office supplies and stationery items, modular office furniture, partitions, metal products, chairs, cabinets and shelving. The Company is the sole local distributor for the leading international brands in office furniture – Fursys and Boss. In 2011, lower priced items were introduced to meet growing demand, by introducing the first of two proprietary brands, the first being the “Image” brand and shortly thereafter in 2012, the Company introduced its second brand “Torch”. SOS also does a small amount of sales to the eastern Caribbean and will be seeking expand business into that Region. According to the company’s management, the increased warehouse space will be critical to this effort. A lesser known service the company carries out, is the servicing of office equipment. This area they indicate has room for increased revenues and profit.
During the last six years, the Company added commercial shredding to its suite of services offered to the general public. The service has become popular among entities which have large volumes of waste paper and other sensitive material that stores data, but are concerned about improper disposal methods. The Company’s states that its “shredding facility meets international best practice standards and has the capacity to shred up to 5,000 pounds of paper per day as well as the destruction of tapes, hard drives and compact discs. The Company’s shredding facility offers the customer the ability to view an on-line real-time video stream of the shredding process being undertaken on-site on their behalf, or if preferred the customer may also be present when the shredding process is being undertaken”.
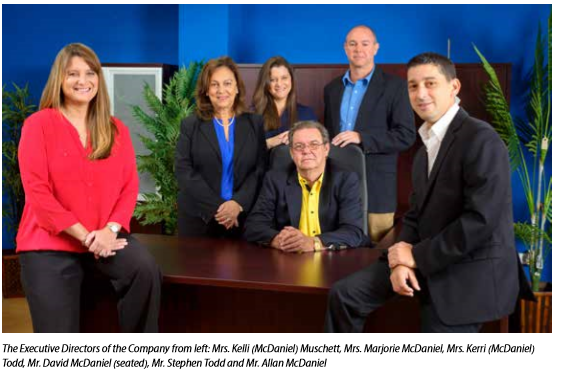
The directors of the company are, David McDaniel, Marjorie McDaniel, Allan McDaniel, Stephen Todd, Kerri (McDaniel) Todd, Kelli (McDaniel) Muschett, Anthony Bell, Gary “Butch” Hendrickson and Evan Thwaites.
Stationery & Office Supplies heads to market
July 4, 2017 by
 The Mcdaniel family owned Stationery and Office Supplies are heading for listing on the Jamaica Stock Exchange Junior Market with an initial public offering 50,024,100 ordinary shares.
The issue is inclusive of 22,500,000 reserved shares, some of which are reserved for staff at $1.60 per share, with the rest being made available to the general public at $2 per share the offer opening at 9 on July 19th, with the closing set for 4:30 P.M. on July 26th.
The Company reported pretax profits of $53 million in 2016 for earnings of 26.5 cents per share resulting in a PE of 7.5 before tax. Earnings for 2017 is estimated at around 36 cents on a pretax basis or a PE of an attractive 5.6 times 2017 earnings.
Radio Jamaica looks promising
July 3, 2017 by
 Radio Jamaica generated revenues of $1.2 billion in the March 2017 quarter, $156 million less than the December quarter but had $49 million more in direct expenses in the March quarter when it was expected that direct expenses would have fallen in keeping with the reduced income.
The group also reported lower profits in the March quarter compared with the December quarter and suffered a loss before taxation of $30 million and $65 million after an increased taxation charge of $35 million, bringing the full year taxation provision to $75 million. RJR ended the fiscal year with profit after tax of $145 million or just 6 cents per share. Results for 2018 should be much better as staff cost will fall with reduction in staffing while some one off cost that affected profit, should not recur.
In the March quarter, general expenses fell by $110 million from the December quarter to reach $562 million. The sharp change could result from reclassification of some expenses to direct cost, resulting in the jump in this area in the last quarter of the fiscal year. In the December quarterly report, the company stated that “increased cost of $64 million was incurred largely from further operational investments and one- off costs”. The areas that incurred the cost are continued rollout of 1 Spot Media, legal expenses incurred in protecting copy rights and defending legal action and repairs to broadcast transmitters. This was reconfirmed by Managing Director, Gary Allen in response to questions posed by IC Insider.com as the reason why profit in the Television segment had fallen even as revenues rose.
“The figures have seven months of the old structure. Only five months of HR synergies were realised in the financial year under review, as redundancies took place in September/November” Gary Allen, Managing Director advised IC Insider.com, in response to our question of how much staff cost is in the 2107 figures for person who were made redundant?
Prior to the merger investors were advised of major cost reduction and improved revenues that will flow from the merged entity. Allen stated ‘they have started with the HR synergies. Others are being realised as we integrate systems in the operations. Most elements will be implemented by the end of 2018/2019.”
Cash flow from operating activities was $363 million but $248 million was spent on acquiring fixed assets with the group ending with cash and equivalent of $291 million at the end of the year. RJR also has investments in bonds and Government of Jamaica securities amounting to $487 million.
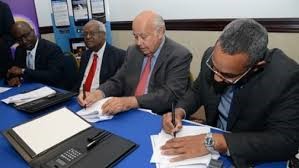
Gleaner & RJR execs signing merger agreement in 2015
The RJR Group underwent major changes with the acquisition of the Gleaner media business. Comparing the 2017 fiscal year’s results with that of 2016 makes little sense with the latter having very little financial data of the acquired business.
Data contained in the segment results, provide some indication as to the performance of various parts of the group. The performance of the segments in 2017 over 2016 show, Audio Visual generating just $65 million more in revenues in 2017 to end with $1.868 billion and contributed $72 million to profits compared to $157 million in 2016, Audio comprising radio operations had revenues of $711 million compared to $567 million and contributed profit of $238 million versus $112 million, Independent Radio coming on stream and growth in Outside Broadcasts contributed to the increase. The print division showed revenues of only $78 million in 2016 and a loss of $190 million saw a major about turn, with revenues of $2.8 billion and profit of $173 million for 2017.
Allen went on to state that “the market will remain competitive and the economic conditions of Jamaica will continue to impact media spend. Improvements will come from those able to leverage market leadership positions, product diversification, overseas earnings and new marketing strategies. RJR has all the necessary ingredients to meet these challenges and the opportunities on the horizon.”
The stock traded at $1.60 on the Jamaica Stock Exchange on Friday and with IC Insider.com projecting earnings of 25 cents per share for 2018 fiscal year ending in March, the stock seems attractive coming against a back ground of continued growth in the Jamaican economy.
Jamaica Broilers’ profit jumps 28%
July 1, 2017 by
Jamaica Broilers
The financial year to April 2017 was a good one for Jamaica Broilers Group, with attractive revenue and profit growth. For the full year, profit after tax attributed to the company’s shareholders rose 28 percent to $2.23 billion from $1.74 billion in 2016.
Sales revenues grew 15.3 percent to $44.44 billion for the year from $38.52 billion in 2016. The group enjoyed a 17% increase in revenues in the fourth quarter to $12.32 billion up from $10.52 in 2016 but profit but rose from $900 million to $1 billion at a slower pace than the growth in revenue.
A fall in the pace of growth in gross profit was a major factor in the slower growth in the last quarter as direct cost rose limiting gross profit to a rise of 13 percent to $3.57 billion in the quarter from $3.16 billion in 2016.
Segment results showed the Jamaican segment generating revenues of $31.96 billion up from $28.4 billion but segment results fell from $3.6 billion to $2.87 billion. Revenues for the US based operations grew to $10.86 billion from 8.8 billion and generated segment profit of $1.3 billion compared to $1 billion in 2016. Other Caribbean Countries generated revenues from third parties of $1.6 billion up from $1.3 billion in 2016 and contributed $944 million to profit up from $254 million in 2016.
While some Jamaican companies are by passing cheap borrowed funds for expansion purposes, Jamaica Broilers with equity capital of $14.4 billion has $7.7 billion in debt. The group holds $2.76 billion in cash with loan receivable of $2.55 billion of which $500 million is due within 12 months. Cash flow from operations is attractive at approximately $3 billion for 2017. During the past year $749 million was expended on the acquisition of fixed assets compared to $800 million in 2016 and the group paid dividends of $420 million for the 2017 fiscal year, up from $311 million in the prior period.
Forecast for 2018 is for EPS of $2.60, up from $1.85 for 2017. The stock closed on the Jamaica Stock Exchange on Friday at $18 at 10 times 2017 earnings but 7 times 2018 earnings compared to an average of the main market of 13.7. IC Insider.com rates the stock a buy for growth and income.