West Indies Petroleum Terminal closed trading on Friday at $7.25 per share, capping a remarkable 1,300% surge since its December 23 debut at $0.50. The spectacular gains resulted in the stock trading at valuation levels that defy conventional metrics, with a huge decline clearly on the cards.
 At Friday’s close, WIPT trades at 244 times 2024 earnings, according to data compiled by ICInsider.com, after eliminating the one off impairment cost mentioned below, a stark contrast to the broader Jamaica Stock Exchange with an average PE of 18 times earnings. The company was initially valued at roughly 11 times earnings at listing.
The rally reflects scarcity more than fundamentals. WIPT was listed by introduction, with no new shares issued, resulting in a minimal float, fuelling speculative demand.
The company has not released any results for 2025, but profitability remains modest, with net profit of just US$1.04 million on revenue of US$8.21 million for 2025, a 51.9% earnings decline from 2023. The results for 2024 were driven by higher finance costs and a US$1.04 million impairment charge, which is not expected to repeat.
The extreme valuation disconnect suggests investors are pricing in dramatic earnings growth that has yet to materialise. Management has signed third-party storage agreements with Musket Corp, TotalEnergies, and Sunoco to supply fuel across Jamaica, which diversifies revenue, but the path to justifying a 244x multiple remains unclear.
For value investors, the math is sobering: at $7.25, the market is betting WIPT will transform from a US$2 million profit company into something vastly larger, in the order of 17 times, amounting to a profit of US$34 million that is not going to happen.
 Many of those listed on the JSE have limited life spans as they are primarily income generating instruments, with a finite life span. The JMMB preference shares are in this category. The old JPS preference shares that were issued at $2 each have declined in value due to a decline in interest rates but the supply of these are very limited. These seem to have no set date to be repaid.
 Ordinary shares offer unlimited capital appreciation and the potential for an endless dividend stream depending on the level of profit generated. Preference shares have limited capital upside potential unless they have participative features, allowing them to share in profits over and above the coupon rate.
 Bank of Jamaica (BOJ) raised interest rates in 2021 with the overnight rate landing at 7 percent in November 2022 and has remained there since, with BOJ keeping a tight lid on market rates by the use of Certificate of Deposits with rates mostly around 10 percent on average, to tame inflation that peaked close to 12 percent in early 2023.
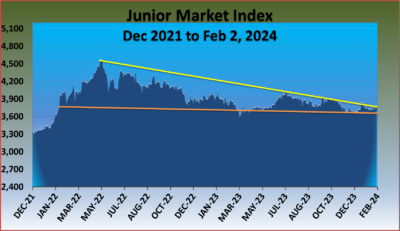
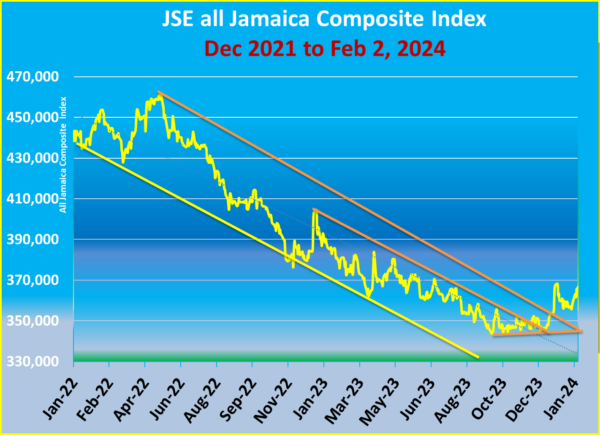
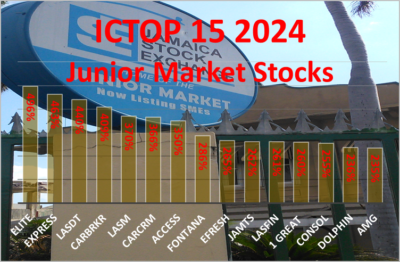
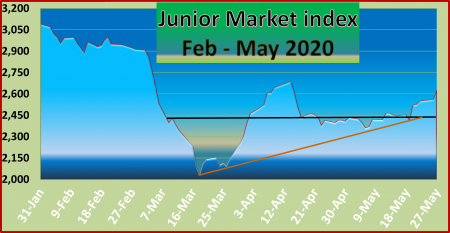
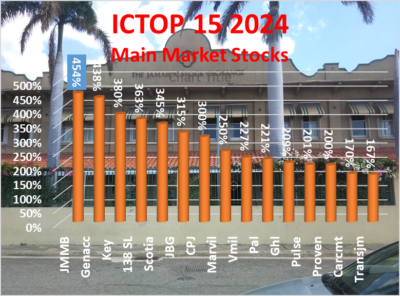 Part of the decline in the Junior Market in 2023 is due to an overall level of over-exuberance by investors in 2022, pushing the prices of a limited number of Junior Market stocks to unrealistic levels, with sharp correction for some of these in 2023 and helping to drag the market. The situation in the Main Market was somewhat different with a lack of interest from institutional investors until the final quarter of the year which is reflected in a continuous slide in the Main Market Index throughout the year until the end of September, indeed from a two-year high of 461,783 points on the All Jamaica Composite Index in May 2022 until it bottomed at the end of September 2023 at 344,153 points and put on almost 23,000 points to the end of the year. While the Main Market declined for two consecutive years, the Junior Market was experiencing its first yearly decline since 2020.
 Barring increased interest rates, the Jamaican economy should grow just around two percent in 20224 and that ought to be sufficient to help generate increased demand for goods and services and assist many listed companies to increase profits from existing operations. Expanding companies will see above average performances.
 The stock pays interest at 3 percent above the 180 days Treasury bill rates, currently, the rate payable is just over 10 percent before tax. At the current price, the annual yield is a mere 2 percent. So why are investors buying the stock at such an elevated price and why are there more sellers?
 “The
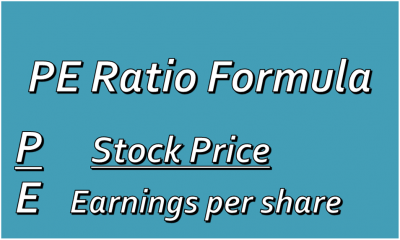 The general rule; buy stocks with low PEs and stay away from those with high PEs and monitor them regularly to see if there are significant changes that may warrant changes in an investment.
 An APO is just like an IPO but it is usually better as the former is already listed and has followers and a wide number of shareholders who are familiar with the company’s history of management and financial wellbeing.
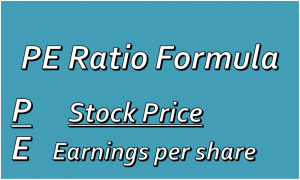 The bulk of investors who would be buying the vast quantity are more professional than not and are versed on the valuation levels of stocks. Accordingly, they are unlikely to be buying a stock that has doubtful expansion credentials at an inflated value. The most popular valuation tool, the PE ratio does not support a price much higher than $1.20, with EPS of 6 cents per share. A price of $1.20 equates to a relatively high PE ratio of 20. Only a few stocks are valued close to this multiple and many of them have prospects for profits to grow. Wigton has no immediate prospects for growth in earnings, pricing it at 20 times EPS would, therefore, be unwise. The market will speak but the heavy selling on Friday is more in line with the thinking that the top is not far off. Investors who buy shares above the accepted market norm will likely get crushed unless they have a long term investment horizon on their minds. PE ratios are there to give a sense of appropriate values. When investors try to break away from where the bulk of investments funds place the value of a stock at, they usually end up regretting the move.