Melissa pressures Junior Market stocks


The Junior Market delivered minor gains in the first quarter of 2026, with the Market Index edging 0.21 percent higher, from 3,401.41 at the end of December, last year, to 3,408.64 at the close of March, 2026. While the index’s move appeared subdued, individual stock performance within the market was dynamic with the leading stock rising a solid 85 percent in a market pressured by disruption caused by Hurricane Melissa that played a major role in pressuring several stocks in the Junior Market.

A number of companies suffered from a loss in revenues during the final quarter of 2026, following the passage of the hurricane. Others faced  continued revenue pressure from the critical tourist sector that recorded sharp decline in visitor arrivals in the first quarter of 2026 and probably for a longer period.
At close of the quarter, prices of 17 stocks rose and was overwhelmed with 29 declining.

Amongst the carnage that some companies suffered, Jetcon Corporation sparked with new cars helping to deliver the top spot for the Junior Market with solid 85 percent gain to lead by a wide margin for in closing the quarter at $2.78, following in a big surge in revenues and profits in 2025, with the expectation of improvement in profits in 2026, over that of 2025, with the fourth quarter of 2026 recording profit before tax of $33 million and pointing to the possibility of more growth in 2026.  Well behind the leading stock, MFS Capital rose a respectable 31 percent, helped by an undervalued stock with the company pumping out above average profit from ongoing operations for the six months, with revenues climbing 40 percent over that for 2024 resulting in profit from continuing operations before tax, rising form $9 million $28 million. Future Energy Source gained 27 percent, with the company posting strong December results from increasing sales, with profit surging 176 percent in the quarter over the prior year and suggesting a big rise for the full year and even more for the fiscal year ending in March 2027. Atlantic Hardware finished fourth, with an 18 percent advance, following increased demand for the stock, following the passage of hurricane Melissa. That did not show up in the company’s results for the December quarter, although revenues climbed but operating profit was flat. Caribbean Assurance Brokers was the fifth best performing Junior Market stock with a rise of 16 percent, with the price was recovering from selling pressure in late 2025.

Underperformers stock or the quarter was In Junior Market was Kintyre Holdings, which fell 46 percent, having ran up to 70 cents at the end up 2026, faced heavy selling in the quarter, as buyers reduced the price they were prepared to buy the stock at. Iron Rock Insurance declined by 29 percent, with investors concerned about the impact the hurricane would have on underwriting margin as well as concerns on the investment portfolio performance with lower interest rates in the country. Paramount Trading dropped 19 percent, reflecting some profit taking after the stock ran up in 2025 based on improved half year results but much lower second quarter profits compared with the first quarter as sales suffered with the interruption caused by Hurricane Melissa. Main Event shed 16 percent, with Hurricane Melissa shattering an already pressured operation that was passing through a period of reduced revenues resulting in a small loss for 2025 coming out of a year of uncertain economic outturn leading up to the general elections in 2025.

WI Petroleum pumps JSE Main Market in Q1


Stocks delivered relief for investors in the first quarter this year lead by an astronomical rise in the price of West Indies Petroleum, that led 21 stocks in recording gains in the Main Market, even as prices of 31 stocks declined.  

The JSE Market Index rose 8.83 percent from 317,986.88 at the close of December 2025, to 346,079.71 at the end of March, this year, compared with a fall of 1.7 percent in 2025 for the same period.
West Indies Petroleum 722 percent quarterly surge was the most dramatic single move on the Main Market in years and is best understood in the context of a low base price at the start of the quarter combined with heavy speculation in a stock that is scare and significantly overvalued with a PE of 221, with minimal growth in profits. Kingston Properties was the second-best performer with a gain of 53 percent, reflecting improved quality of the 2026 operating profits and precious severe undervaluation of the stock. Transjamaican Highway rose 42 percent, buoyed by growing revenues and profit with positive projections tied to increased vehicular traffic from the Mandeville leg of Highway 2000 and increased dividend payment. Sagicor X-Fund advanced 23 percent, with its performance underpinned by improving profit outlook. NCB Financial Group rounded out the top five with a 21 percent gain, recovering from prior-year lows as the market repriced the stock from a vastly oversold position in 2025 as the group’s chairman struggled with negative perception that filtered into the stock’s performance.

Underperformers
On the losing side, Proven Investments (PRVN) declined 22 percent, weighed down by increased cost that resulted in a small loss in the December quarter and sharply reduced profit for the nine months versus the similar period in 2025. Mayberry Group (MBG) fell 21 percent, reflecting losses from the performance of its underlying equity holdings and a small loss on net interest income in 2025. Caribbean Producers Jamaica (CPJ) and Mayberry Jamaica Equities (MBJ) each declined 17 percent, with CPJ facing headwinds from mixed results for 2025 and reduction in visitor arrivals to the country that will affect sales and profit negatively in 2026, as the bulk of revenues come from that sector. Losses at MBJ ballooned sharply for 2025 due mainly to fall in market value of investments. Palace Amusement dropped 16 percent, with the company posting losses for the half year to December and continues to face challenges with returning to patronage at the pre COVID levels. Supreme Ventures (SVL) retreated 14 percent, as profits declined in 2025 and the gaming market faces increased competition, while concerns over gaming revenue sustainability also weighed on sentiment.
SOS SEEK’s factory opening March 27


Stationery and Office Supplies will officially opens its newly completed SEEK book manufacturing and storage facility, on March 27. A landmark investment amounting to over $150 million, significantly expands the company’s production capacity as it enters a new phase of expansion and growth in its book production business.
Stationery & Office Supplies hit a record high on Friday.

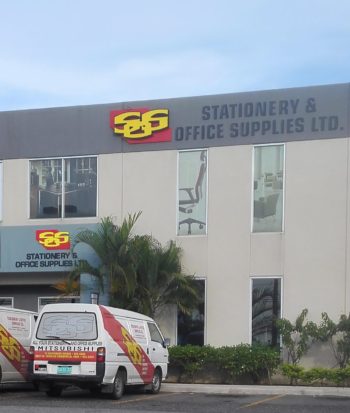
Stationary & Office Supplies – Montego Bay office.

The new facility, located at 26 Collins Green Avenue, and close to the Stationery and Office Supplies offices on Beechwood Avenue, encompasses 8,000 square feet of dedicated manufacturing and storage space, built at a cost exceeding $150 million. The expansion increases SEEK’s operational floor space by 300 percent, providing the room needed to scale production, house new machinery, and build inventory buffers to support both local and regional demand. Management indicates that the plant has the capacity to supply Jamaica with the total needs of exercise books with capacity for export.

Following headwinds in the Books segment in 2025, revenues declined to $76 million from $106 million in 2024, due problems with machinery and disruption to sales due to damage caused by Hurricane Melissa in the western section of the island.

Stationery & Office Supplies new book making operation.

With new machinery now tested and staff fully trained, the company is already seeing a meaningful step-up in production volumes and improved unit economics as the facility scales up. The investment also aligns with SOS’s broader sustainability agenda in broadening the portfolio of products for sales locally and in the wider Caribbean.
Reduction in Seek sales during the year helped in keeping revenues for SOS to $23 million more than the $1.84 billion in 2024, with 2025 ending at $1.87 billion. Stationery and other items also contributed less revenues than in 2024, with sales slipping $65 million from $506 million to just $441 million in 2025.

General Accident to more than double


General Accident Insurance Company and Beacon Insurance Company Limited, a Trinidad and Tobago based general Insurance company, announced their intention to complete a transaction to create a leading Caribbean insurer.

Paul Scott, Chairman of General Accident shake hand with Beacon’s, Gerald Hadeed after the signing of the acquisition agreement

The acquisition will push General Accident’s gross written premiums up to a projected sum in excess of J$32 billion annually, up from more than $11.4 billion last year.

General Accident’s parent, Musson (Jamaica) purchased 100% of Beacon in October. Beacon will subsequently become a subsidiary of General Accident, subject to additional regulatory approvals.

The acquisition will greatly expand General Accident’s presence in Trinidad and Barbados and allow it to enter new markets in Dominica, Grenada, St. Kitts, St. Lucia and St. Vincent, the report stated.
Beacon will continue to operate as an independent subsidiary of General Accident. The combined company intends to maintain both the Beacon and General Accident brands in Trinidad and Barbados.
Beacon reported insurance revenues of TT$505 million (J$12 billion) in 2023, the latest financial statements seen, with total assets of TT$788 million and shareholders’ equity of TT$192 million (J$4.6 billion). Profit reported by Beacon in 2023 was TT$11 million or J$264 million.
General Accident reported insurance revenues of $9.6 billion in the nine months to September this year, up from $8.3 billion for the same period in 2024. For the quarter ended September, $3.3 billion versus $2.9 billion in 2024, with profit after tax of $297 million for the nine months to September 2025 versus $216 million in the prior year. For the September quarter, profit was $122 million, up from $57 million in 2024. These results are before any claims, likely to come from the damage caused by the recent hurricane.

Beacon has offices and an Agency network that spans Trinidad & Tobago, Barbados, Grenada, St Lucia, St Vincent & The Grenadines, St Kitts & Nevis, and Dominica.
General Accident, will need to rationalize cost by reducing, where possible, areas of duplication within the expanded group. Savings will also come from better underwriting terms that will flow from a lager group and a wider geographic expanse and the ability to expand more rapidly into a much bigger group. IC Insider.com sees, General Accident’s current Barbados and Trinidad general insurance companies being absorbed into Beacon and thus reduce operating costs.

Who is Odene James?


Listed companies, many of which pride themselves on good corporate policies, should do better in speaking to investors. Ms. James has been added to the list of directors of Caribbean Assurance Brokers, effective October 1.
Why did the company not advise the public about who she is? This is terrible. Let’s be fair, this is not the only company to have failed to advise investors of the credentials of new appointments. A quick review of the internet reveals very little about her credentials.

Jamaica Broilers shareholders clobbered


Jamaica Broilers released a damning report in March this year of management’s stewardship in its January third quarter Results. The directors “advised that it had identified several issues related to expense management and operational controls in its U.S. Operations and had engaged external advisors in the United States to review operational control and any implications it had for the financial performance of the U.S. Operations.”

Christopher Levy – Jamaica Broilers President and Chief Executive.

The group is now updating investors on the latest information. “Having received preliminary and not yet finalised reports from its external advisors, and having assessed the financial performance of the U.S. Operations, the Company wishes to disclose the following material information, which it believes could have significant implications for the financial statements of the Company, namely unsubstantiated accounting valuation methodologies affecting several financial statement line items, including Inventories and Biological Assets.”

“The issues identified appear to constitute material prior period errors and will, once determined and finalised, be fully corrected following the conclusion of the annual financial audit for the Company. As a result of the likely restatement of inventories and biological assets, we anticipate a material negative impact on the historical profitability of our U.S. operations and the Group’s consolidated retained earnings and capital.”
The Company wishes, however, to assure its shareholders and stakeholders that the Board and Senior Management of the Company have been, and are taking steps, in conjunction with its legal and financial advisors, to address the above referenced issues related to the expense management, operational management and financial performance of the U.S. Operations, with a focus on accurate reporting on the profitability of the U.S. Operations and for the Company.

The problem at Jamaica Broilers is a big black eye on the Jamaican securities industry. There are far too many issues in the sector in need of urgent attention, as investors are being severely abused. Those in a position to act and correct the problems have turned a blind eye, until there is a big blow up like Usain Bolt losing his money. What about companies that have billion-dollar loans made to the related companies, interest free while minority shareholders pay the cost of funding them. What about investment firms that breach agreements with their customers and get away with it while the FSC sits and watches.

ANSA McAl delivers a TT$2.5B blow to shareholders


Shareholders in ANSA McAl are set to lose TT$2.5 billion in 2025 from their investment in the company, following the directors decision to suspend dividend payments, (currently $320 million per year) for 3 years, with the stock price dropping 21 percent from $58 to $46 up to the end of last week.

In addition to losing the $320 million per year for the next three years, shareholders have already chalked up a loss on their shares of $2.1 billion, following the announcement in March, and it could get worse, with the bid to buy the stock at $45 and the offer to sell at $46, last Friday. The dividend suspension will conserve TT$951.5 million for the three years based on $1.80 paid in 2024, 2023 and 2022, but it has had a detrimental impact on shareholders.

In addition to cash savings from the suspension of dividends, the company will save the cost of servicing the twice-yearly dividend payment and will incur less interest expense as a result of the suspension.
ANSA McAL, the majority owner of Berger Paints Jamaica, decided to suspend dividend payments due to the acquisition of a company for US$327 million, which resulted in a US$$200 million loan.
This decision was published on March 21st, 2025, in the Chairman’s statement, which accompanied the audited financial results.  According to the report, “ANSA McAL is confident that the reinvestment of dividends for this three year period will yield far greater long-term benefits – enhancing its competitive position, supporting expansion into new markets, and unlocking new growth opportunities. Moreover, ANSA McAL fully expects the result of this strategic decision to be a significant appreciation in its share price, ensuring that shareholders benefit from a stronger, more resilient, and more valuable company.”
Some shareholders do not buy the optimism expressed by the directors, at least not now. For the year ending December last year, revenue grew by 5 percent to $7.4 billion and profits climbed just over 10 percent to $571 million from $517 million in 2023. On the surface, the stock should have been rising, instead, it has fallen from a 2025 high of $61. Compounding the issue, revenue grew 9.6 percent to $1.8 billion for the March 2025 quarter. Profits for the quarter dived 50 percent to $54 million from US$107 million as finance cost surged from $10 million to $52 million.
The directors commenting on the 2024 results stated, “Beyond these outstanding financial results, we took a bold step forward in our long-term strategy by completing the largest acquisition in our 143-year history. The US$327 million acquisition of BLEACHTECH LLC, a leading US-based chlor-alkali producer, is a transformative move that positions us for even greater success.”
At the end of March, Shareholders’ equity stood at TT$8.2 billion. At the end of December last year, borrowed funds amounted to $2.6 billion, just around 32 percent of shareholders’ equity. With the leverage level so low, there seems to be no need to suspend dividends and, by extension, destroy shareholders’ investment.

Seprod gunning for 80% of AS Bryden


Seprod, the Jamaican conglomerate, announced an offer to acquire up to 447,491,012 ordinary shares of its subsidiary A.S. Bryden & Sons, representing 29.85 percent of the 1.4992 billion issued ASBH’s outstanding shares. 

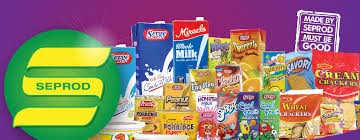
Some of Seprod”s products.

The offer will be satisfied by the issue of 396.43 Seprod shares for each 1,000 ordinary shares of ASB. The offer will expire on June 5, unless it is extended.
According to the latest public notice of the company, Seprod currently holds 751.66 million shares, the acquisition would take them to 1.2 billion or 80 percent of the outstanding shares, enough to keep them listed on the Jamaica Stock Exchange on the surface of it.
Connected parties to Seprod own around 300 million shares, these include Musson Investments with 144 million shares and Stony Hill Capital with 114 million units. Richard Pandohie, CEO of Seprod owns 65.8 million shares. It would appear that the offer is an exercise, primarily to roll all these holdings into Seprod and simplify the accounting for the investments.
At the close of trading on the AS Bryden shares closed at 33 and Seprod at $81.05, the equivalent of 2.456 Bryden shares for each Seprod share. Shareholders of Bryden will be getting shares in a more dynamic company with greater growth prospects than in the stand alone Bryden.

One Great Studio buys media company

One Great Studio a Junior Listed company announces a strategic acquisition of the business of DRT Communications, a leading public relations and media intelligence firm, for a total consideration of J$115 million, which includes a J$35 million performance-based earnout over 3 years.

Djuvane Browne, Managing Director

Danielle Terrelonge is the Managing Director and Chief Storyteller at DRT Communications, a “fully equipped marketing communications agency.” “The team is equipped to plan and execute public relations campaigns, develop content for electronic, print mediums, and websites, and manage communications projects from concept to completion,” the company states on its Linkedin site and engages between 11-50 employees.

The acquisition is in line with the company’s CEO Djuvane Browne’s objective of acquiring an advertising firm to compliment the advertisement placement of One Great Studio.

According to One Great Studio, “we’re digital natives with deep knowledge of design, technology & business. We help you generate more leads & make more sales with digital marketing, websites, web applications & mobile applications.

Acquisition doubles ISP Finance


Micro financier, ISP Financial Services has more than doubled its size by acquiring the principal balance of a loan portfolio of approximately $1.2 billion. The acquisition more than doubles the company’s loan portfolio of just over $1 billion at the end of September last year net of provision for loan losses, pushing it to $2.2 billion.

The terms of the acquisition were not stated in the release by ISP at the close of the day on Wednesday but ICInsider.com has been reliably informed that the acquisition took place using a combination of internal and external funding which a portion of the principal deferred to be paid at some time in the future.

Last year’s annual general meeting scheduled to be held on November 21, 2024, was postponed until January, this targeted date has been pushed back, but no doubt will be held drown about March or April. The portfolio is acquired from a large Jamaican owned banking group. ISP had stated in 2021 that they were in discussions to acquire a portion of the loan portfolio of Micro lender, Mundo Finance but that deal was never materialized.
The current acquisition is likely to double revenues that stood at $520 million in 2023 and were 9 percent higher for the nine months to September last year to $400 million with $118 million generated in the September quarter. The acquisition could push profits sharply higher and also with the benefit of economies of scale. Profit for the nine months last year was up 66 percent to $55 million. IC Insider.com estimates that profits could exceed $2 per share or more in a full year of operation if all goes well.

At the end of September 2024, ISP equity capital was $641 million, with borrowings of $520 million. This recent acquisition stretched the capital base considerably with the debt to capital ratio out of line with acceptable levels, accordingly, ICInsider.com expects the company at the upcoming annual general meeting to have shareholders approve an increase in the share capital with the possibility that the stock could be split ahead of a likely return to the capital market to raise fresh equity capital to needed to normalize the capital base and to fund growth in the loan portfolio.