Jamaica Producers’ profit jumps
Revenues for the year to September declined from $6.44 billion to $6.15 billion. Net profit nine months to September amounts to $807 million, an increase of 194 percent over $275 for the year to September 2014. The year to date profit includes gain on sales of property of $319 million recorded in the June quarter.
Gross profit inched up to $440 million in the third quarter from $421 million in 2014 and for the nine months, from $1.4 billion to $1.45 billion. Share of profit in associated companies and joint ventures contributed $217 million for the 2015 quarter up from only $61 million in 2014 and for the nine months to $491 million versus $228 million.
Cash flow from operations amounts to $186 million compared to $267 million in 2014, leading to cash and equivalent of $471 million at the end of the 2015 period. Administrative and other cost rose moderately by $12 million for the quarter to $485 million and $43 million for the nine months to $1.45 billion. Jamaica Producer is headquartered in Jamaica, is listed on the country’s stock exchange, last traded at $23.80 with earnings per share including gains on property of $4.17 for the nine months to September this year and $1.02 for the quarter, for the full year earnings from ongoing operations should end around $3 per share, the stock now trades at around 8 times 2015 earnings from ongoing operations. The main activities of the company and its subsidiaries are juice and food manufacturing, the cultivation, marketing and distribution of fresh produce, logistics, land management and the holding of investments.
Total equity capital amounts to $6.5 billion, borrowed funds amount to $2.1 billion, while current assets stood at $2.49 billion and current liabilities at $1.76 billion.
Point Lisas remains undervalued
Point Lisas is headquartered in Trinidad, is listed on the country’s stock exchange, last traded at $3.90 and is an undervalued stock with earnings per share including gains on property of $1.85 for the nine months to September this year.
Profit before tax of Point Lisas Industrial Port Development (Point Lisas) for the period to September, excluding fair value gains on property, amounts to $20.4 million an increase of 181 percent over $112,000 for the same period for 2014. Gross profit climbed sharply by 29 percent to $51 million in the third quarter from $40 million in 2014 and for the nine months, an increase of 12.66 percent from $134 million to $151 million.
For the September quarter, profit after tax moved from a loss of $14 million to a surplus of $14 million including fair value gains on property of $10.6 million and fair value loss of $4.7 million in the 2014 quarter. For the year to September, fair value gains on property amount to $58 million for 2015 and $91 million in 2014.
Revenues grew by 10 percent for the nine months to September compared to the period to September 2014. Cash flow from operations amounts to $31 million and is up from $13 million in 2014, leading to cash and equivalent of $60 million at the end of the 2015 period. Administrative and other cost declined moderately by $5 million for the quarter and for the nine months.
According to management in their report to shareholders, the increase in revenue was heavily influenced by containerized cargo operations which experienced a 15 percent increase in throughput over the same period in 2014. The data showed a 4 percent increase in imports, an 8 percent increase in exports and a 60 percent increase in trans-shipment cargo. General cargo experienced a 10 percent decline due to an 88 percent decrease in exports, a 1 percent increase in imports and a 4 percent increase in trans-shipment.
Total assets climbed to $2.28 billion in the third quarter 2015, equity capital amounts to $1.97 billion, borrowed funds amount to $125 million, while current assets stood at $121 million and current liabilities at $52 million.
“In the second and third quarters, PLIPDECO provided bunkering services as part of its service and revenue expansion drive. During the fourth quarter, the Corporation intends to continue with infrastructural improvements, information technology upgrades and move steadfastly with the Port upgrade project. The future outcome of these undertakings would further enhance productivity, overall efficiency of Port Operations and ultimately boost profitability,” Ian R. H. Atherly, Chairman of the company said in a release accompanying the financials.
Grace grows Q3 profit 7%
Revenues for Grace Kennedy rose a strong 14.4 percent in the nine months to September, this year, to $59.7 billion from $52.2 billion generated in the corresponding period of 2014. Profit attributable to owners of the group for the third quarter of 2015 was 7 percent higher than for the similar period last year, reaching $754 million.
Profit declined by $338 million or 14.2 percent for the year to date, compared with the similar period of 2014, moving from $2.38 billion to $2.05 billion.
The earnings per stock unit to September amount to $6.19, down from $7.21 in 2014, for the full year should end around $3.4 billion or $10.30 per share.
“The Group’s performance was in part impacted by the costs associated with the integration of our expanded US Food operations through GraceKennedy Foods (USA), recognition of the total asset tax liability in the first quarter, lower foreign exchange gains and higher finance costs”, Group Chief Executive Officer, Don Wehby and chairman Gordon Shirley said in his report to shareholders.
“The Money Services segment recorded higher revenues and profits due to higher remittance transactions and increased market share in Jamaica, higher revenues from our cambio operations in Trinidad, and cost containment initiatives implemented by the segment”, Wehby and Shirley stated.
Shareholders’ equity stands at $37.2 billion with book value per share of $112.47. The company will pay a third interim dividend of 90 cents per stock unit on 16th December.
Grace’s shares are listed on the Stock Exchanges of Jamaica and Trinidad and last traded at J$68.11 and TT$3.60 giving it a PE of 6.7 times 2015 earnings leaving room for quite some growth.
Flat profit for Republic Bank
Republic Bank reported profit attributable to shareholders of TT$1.22 billion for the year ended September 2015, representing an increase of $30 million or 2.5 percent over that reported for 2014.
For the last quarter, Republic shareholders enjoyed net profit of $326 million versus $324 million in the 2014 quarter, from net operating income of $1.06 billion up from $950 million in 2014.Earnings per share for 2015 is $7.59 and for 2014 $7.42 and diluted earnings per share of $7.57 versus $7.39 in 2014 while return on average assets ended at 1.97 percent, down from 2.10 percent in 2014. Return on average equity for 2015 is 14.09 percent compared to 14.33 percent in 2014.
“Growth was driven by a 10.6 percent increase of $235 million in net interest income, arising from a $5.9 billion or 21.8 percent growth in the loan portfolio and the recovery of $123 million after tax on a non-performing facility. This was offset by an increase in operating expenses of $212 million and impairment expenses of $109 million,” Ronald deC. Harford, Chairman of the group stated.
Harford continuing, indicated the “increase in operating expenses is attributable mainly to the consolidation of HFC Bank (Ghana) and Republic Bank (Suriname) which amounted to $89 million. Impairment expenses of $52 million (net of minority interest) was recorded by HFC to bring its loan provisions in line with Group policy and $57 million was booked by Republic Bank (Cayman) relating to loans and goodwill impairment”.
Total Group assets increased by $6.6 billion or 11.2 percent over the prior period to $66 billion at September 2015 which was aided by two acquisitions during the year by increasing their holding in HFC to 57.11 percent and in July and 100 percent shareholding in RBC Royal Bank (Suriname) N.V. These two purchases added $5.5 billion to the total assets.
A final dividend of $3.10 for the year ended September 2015 (2014: $3.00) will be paid on December 1, bringing the total dividend for the fiscal year to $4.35, a slight increase over the $4.25 paid in 2014.
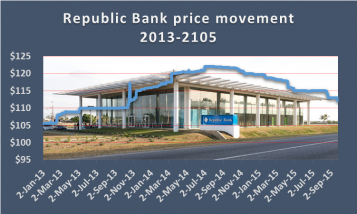
Republic Bank is headquartered in Trinidad and is listed on the country’s stocks exchange and last traded at $112.
Strong Buy Rated growth more to come
While Jamaican stocks have jumped sharply those in Trinidad are just marking time which a number of prices retreating as interest rates were pushed up by the central bank on a number of occasions and the country faced falling oil revenues with the fall in world oil prices.
In the Jamaican market, stocks that were selling around 5 times earnings or less at the start of the year, have seen a sharp revaluation of many, with an average now around 9 times earnings based on this year’s estimated earnings. A total of 22 companies or 41 percent of the ordinary listings are selling above the average. Indications suggest that the rally in Jamaica will continue, with expectation for interest rates to decline going into 2016. A sharp 32 percent fall in interest rates from March last year to October this year, is one of the main driver of the market. Company results have been mostly strong with many enjoying large increases over the results of last year as well as over the 2013 period. A fall in the cost of energy and fuel and expanded sales in some cases are major drivers of profit gains this year as well.
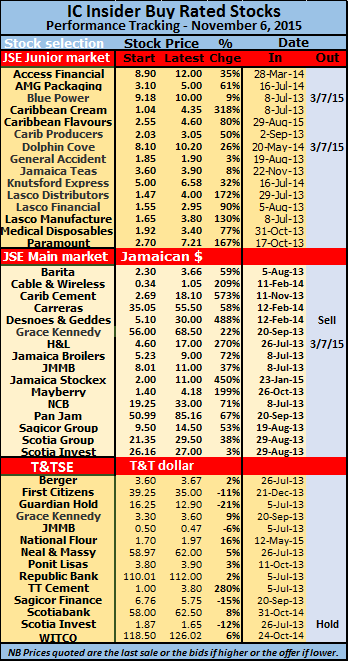
It is partly against the above developments, that IC Insider BUY RATED listing of stocks should be viewed. Some of the stocks have been placed on hold based on the gains to date and much higher valuation as a result of this year’s growth.
Four junior market stocks should be held at this moment rather than buys, unless investors are looking at a two to three year’s investment period. Lasco Distributors, Lasco Financial, Lasco Manufacturer and Medical Disposables have reached rich valuations and should be held at this stage of the market. Profit growth for 2017 fiscal year for the Lasco companies should be very strong and will make them attractive buys again, the task is when should these be bought again to take advantage of the strong growth ahead? The problem now is that supply for these stocks is low, currently. Dolphin Cove growth has slowed for this year and remains a hold for now until 2016, the rest of the junior market selections are still attractive buys, with potential gains of 50 to 130 percent for a number of them.
Desnoes and Geddes should be sold now with the price at $30 rather than to await a payout from the proposed buyout proceeds. The Jamaica Stock Exchange share has gained 450 percent since we placed a BUY RATED status on it. The price has room to grow but investors will need to be cautious about buying at current price levels until the release of the September quarterly report in a few days. A hold is placed on the two Scotia shares with both now valued around 10 time 2015 earnings. Carreras is priced close to 10 times this fiscal year’s earnings but high dividend yield well in excess of current Treasury bill rate of 6.2 percent will make the stock an attractive income earner and will continue to drive the price upwards. Mayberry Investments should be a hold at this stage, with reporting earnings not in strong support of the present stock price, the company has the assets that will aid in a large increase in net asset value.In Trinidad, companies are having a tough time growing profits in a meaningful way but there are still a few stocks that are worthwhile holding, with Trinidad Cement being a very compelling buy now selling at a PE of 4 times this year’s earnings. National Flour is undervalued and has room for growth with increased profits in 2015. Most of the rest will have to await 2016 for increased profits and growth.
Strong C&WJ mobile growth
The report went on to state, “In the first half of the current fiscal year, our total number of network sites grew by 10 percent and our mobile networks carried 93 percent more data traffic, with Jamaica data traffic up 241 percent, BTC up 137 percent, Panama up 81 percent and Barbados 73 percent higher.”
In the Caribbean, the company said “we completed Phase 1 of our broadband expansion in Jamaica passing 800 homes in Portland with Phase 2 underway and set to pass an additional 7,300 homes taking our total homes passed to 276,000. We also began installation of a new backbone to upgrade core capacity to multiple 100Gbps links. In Trinidad, we passed an additional 4,800 homes with HFC, taking our total homes passed to 311,000 in Trinidad and we passed an additional 19,000 homes with FTTH in Barbados taking our coverage to over 100,000 homes passed. In the Bahamas, we have completed the design phase of our plans to pass 14,200 homes.”
Profit gains 12% at Medical Disposables
Profit after tax for the six months of the financial year to September for Medical Disposables of $42.7 million rose 11.5 percent over the similar period last year. For the September quarter, profit after tax came in at $23.4 million, an increase of only $1.9 million or 9.2 percent.
“The increase in profit was as a direct result of the improved performance in sales revenue for the period ended September, 2015”, Kurt Boothe, General Manager stated in the report to shareholders accompanying the interim financials.
Operating profit rose more impressively than net profit, with a rise to $30 million from $22.5 million, an increase of 33.6 percent and for the half year, 29.6 percent to $53.8 million from $41.5 million in 2014. Increases in finance cost, foreign exchange loss and provision for taxation helped to reduce the final numbers to a moderate increase. Cash flows for the six months before interest cost rose to $57 million from $45 million in 2014.
Earnings per share rose to 9 cents per share in the quarter and 16 cents for the six months and should end around 35 cents for the year ending March 2015.
Sales revenue rose to $599 million, increasing by $59 million or 10.9 percent for the six months to September compared to the same period last year. Revenue for the six months rose 8.9 percent to $308 million from $283 million.
Gross profit for the six months ended at $166.7 million and increased by $30.6 million or 22.5 percent compared to last 2015. “This improvement was due to increased sales in all product categories, changes in the product mix and maintaining gross margin efficiency the company said,” Boothe stated. For the quarter gross profit rose 17 percent to $82.6 million from $70.46. Gross profit margin increased to 26.8 percent in the September quarter from 24.9 percent last year for the similar quarter and for the six months period 27.8 percent versus 25.2 percent.
“Total operating expenses of $113 million reflected an increase of $18.4 million or 19.4 percent over the same period last year. The increase in expenses was driven mainly by staff related costs, insurance, utilities, professional fees, information technology services and expenses related to the new property purchased earlier in the year. Staff related expenses, in particular, increased because of the strategic decision to realign the staff complement and compensation to sustain the current growth, development and expansion of the business,” Boothe further stated in his report.
Current assets amounts $587 million inclusive cash funds of $77 million and current liabilities of $253 million, including short term borrowings of $74 million. Shareholders’ equity increased to $435 million with total borrowings of $324 million.
The main activity of the company is the sale of medical disposables and supplies. The company’s shares are listed on the junior market of the Jamaica Stock Exchange since December 2013. The stock last traded at $3.50 and is up 43 percent for the year to date. it is now priced at a PE of 10, based on IC Insider full year estimated earnings.
Paramount more than doubles dividend
Paramount Trading will be paying a final dividend of 39 cents on November 23, 2015 to shareholders on record as at November 12.The ex-dividend date is November 10, 2015.
The company made profit of 95 cents per share for the fiscal year to May 2015 and 61 cents in 2014. The 2015 payment represents 41 percent of profit and equates to a dividend yield of 14.89 percent based on the price of $2.62 at the start of the year. For the quarter ending August earnings grew 27 percent to 28 cent per share versus 22 cents in the same period in 2014.
Paramount Trading paid a dividend of 15.1 cents per share payable on December 12 last year.
the company’s shares are listed on the junior market of the Jamaica Stock Exchange and last traded at $7.10.