Profit doubles for National Flour but…

National Four doubles profit but gains in Q3.

National Four doubles profit but gains in Q3.


Trinidad’s National Flour Mills reported a 200 percent jump in profit for the six months to June of $20.57 million versus only $6.79 million in 2014, but for the nine months to September, growth slowed sharply, to an increase of 103 percent, to $29 million.
The sharp fall resulted from much slower growth in the September quarter, with profit after tax of $8.5 million, just up from $7.4 million in the similar 2014 quarter. The latest quarter reflects a continuation of the slow down in profits which occurred in the June quarter, with profit margin shrinking in that quarter. Earnings per share for the quarter ended at 25 cents versus 12 cents in 2014.
Revenue climbed 15 percent for six months, and is now up only 7 percent for the nine months to $359 million as revenues fell in the September quarter, to $103 million from $121 million for the September 2014 quarter. Cost rose a little faster in the September quarter, than it did for the June quarter, year over year, administrative cost jumped 32 percent to $30.3 million.
The company generated cash flow from operations of $44 million up from $28 million in 2014 and ended with cash and equivalent of $102 million up from $40 million at the end of September last year. Borrowings grew from $113 million to $137 million and payables were up from $27 million in September last year to $68 million, while equity stands at $223 million.
FlourHelping the company, is the sharp fall in the price of wheat on the world market from a high of more than US$700 to just over US$500 to June but below US$500 per tonnes for quite a bit of the reporting period this year.
National Flour manufactures and distributes flour is listed on the Trinidad and Tobago Stock Exchange (TTSE). Earnings for the full year to December should end around 35 cents per share. The stock trades at $1.97 around 5 times earnings, a low valuation. If the company can maintain the level of profit now being generated and improve on it in 2016, the stock stands to generate a good level of appreciation. Investing in the stock is not without risk. The cost of wheat makes up the bulk of direct cost, the ability for management to adjust prices if wheat prices change can be critical to the profitability. There are also political factors to consider as a large portion of the issued shares is under government ownership.
TCL older owners screwed as profit rise

TCL 9-15Trinidad Cement achieved a 135 percent jump in profit after tax due to shareholders for the quarter to September, but the data showed that the most of the minority shareholders have suffered a massive dilution in their earnings.
The company reports $74 million for the 2015 third quarter, compared with $30 million for the same period last year, year to date profit after tax leapt 558 percent to $395 million above the $60 million reported for similar period for 2014. All shareholders get 16 cents per share for the September quarter for each share they hold, the year to date results show them entitled to $1.18 or 7.65 times the September quarters’ earnings. The year to date profit is 6.8 times the prior year’s nine months figure, a difference of 12.5 percent.
The company through a rights issue increased the share capital which diluted the earnings per share. Instead of increased earnings after the company’s debt was restructured, leading to lower debt servicing cost, the majority of shareholders will see lower earnings per share going forward even as the company prevented some shareholders from participating in the issue and withheld pertinent information from most shareholders. As a result the earning per share for 2016 is likely to be no more than 70 cents compared to 96 cents in 2015 from continuing operations, even as profit is likely to rise.
Earnings per share from continuing operations amount to 15.5 cents for the quarter and $1.186 for the nine months. Full year earnings should end up around $1.40 but this includes approximately 44 cents relating to the one off restructuring credit, thus reducing the ongoing earnings to 96 cents per share.

Caribbean Cement factory-  majority controlled by TCL

Caribbean Cement factory- majority controlled by TCL

Revenue in third quarter 2015 rose 7 percent to $550 million compared to $514 million in third quarter 2014, due mainly to a 13 percent increase in cement sales volume in the domestic markets and higher clinker export sales. For the nine months sales revenue amount to $1.64 billion versus $1.59 billion in 2014.
“This performance was largely driven by higher domestic sales volumes, and lower fuel and electricity costs at CCCL and ACCL” Wilfred Espinet Group Chairman and Nigel Edwards, a Director of the company told shareholders in a statement accompanying the interim financials. The company enjoyed a $206 million credit which is reflected mainly in the year to date results for 2015 as a result of restructuring the heavy debt in had incurred previously.
Finance cost for third quarter was $12.5 million lower than third quarter 2014 and ended at $35 million due both to the reduced interest rates from the new loans and a reduction of the principal loan balance from US$245 million to US$200 million. For the year to date finance cost fell to $145 million compared to $214 million in 2014.
Cash flow from operations amounts to $65 million I the quarter and $677 million of the nine months leading to cash at the end of the period at $302 million. The working capital moved to $340 million with current assets of $978 million and current liabilities of $633 million at the end of September. Non-current liabilities stand at $1.4 billion and equity at $1 billion.
The company shares are listed on the Trinidad and Tobago Stock Exchange (TTSE), it manufactures and distributes cement in the eastern Caribbean and Jamaica. The stock last traded at $3.50 on the TTSE on Friday October 30.

RML sheds loss maker grows profit

ReadymixReadymix West Indies (RML) achieved a net profit after tax of TT$6.3 million for the third quarter of 2015, compared with $2.6 million for the same period last year. Year to date profit after tax for 2015 rose to $13.8 million and is 34 percent above the year to date for 2014, of $10.3 million.
Earnings per share for the quarter amounts to 53 cents versus 33 cents in 2014 for the quarter and $1.16 versus $1 in 2014. The company discontinued operations in Barbados in 2014, excluding losses incurred in the discontinued business, results in earnings of 50 cents per share for the quarter in 2014 and $1.21 for the nine months.
Revenue for the quarter fell 7 percent to $57 million from $61 in 2014. It increased 7 percent for the nine months to $174 million from $162 million in 2014. The decline in sales in the September quarter was “impacted by a slowdown in the construction sector”, chairman of the company Nigel Edwards and the Group CEO, Jose Luis Seijo Gonzalez stated in a joint release with the financials.
The company generated cash flow from operations of $53 million up from $12 million in 2014 and ended with cash and equivalent of $58 million from $12 million in September last year.
RML has equity capital of $105 million, current assets of $111 million, current liabilities of $41 million and non-current liabilities of $10 million.
The company is a subsidiary of Trinidad Cement, its shares are listed on the Trinidad and Tobago Stock Exchange (TTSE), it provides premix concrete mixtures to customers in the construction sector. The stock last traded at $18.79 on the TTSE on January 6 this year but ends trading with a bid of TT17.72 on Friday October 30, putting the value at a PE of 10.

Barita scores big with 376% winner

Much have changed in the Jamaica stock market since September. All the JSE indices hit new record highs during the October. In September a listing of three sets of stock recommendations were reported on.
BILMIL-10-15With October now ended, IC Insider updated the chart to see how well each selector did. We let the readers make their own judgement. Bear in mind that only one month has so far elapsed. Suffice to say, Barita Investment scored big with their Desnoes & Geddes selection, with a gain on of 376 percent to record the biggest gain by far. IC Insider would place a hold on any buying of Cable & Wireless at this stage with the big run up in the price recently and would be cautious on Lasco Manufacturing at current prices although the stock has strong long term growth potential.
Note that the PE ratios in the table was the ratio at the time of selection, with prices having changed the current PE will have mostly moved upwards.

Witco growing profit up bit by bit

witcoRevenues for West Indian Tobacco rose moderately to $293 million from $282 million for the quarter and for the nine months to September 2015 and increase of 4 percent to $909 from $872 million in 2014, including excise taxes.
The slight revenue growth resulted in a 9.7 percent increase in profit before taxation of TT$479 million, for the nine months and profit after taxation of $354 million, an increase of 7.6 percent over 2014. For the September 2015 quarter, profit after taxation ended at $113 million an increase of 6.7 percent over 2014.
Expenses were kept below that of 2014, in the latest quarter and year to date, with only selling and distribution expenses showing a slight increase of $600,000 for the year to date.
The Board has accordingly approved the payment of a third interim dividend of $1.44 per ordinary share payable on 30 November 2015 to shareholders of record at close of business on 11 November. For the year to date dividends already paid amounts $3.17. Witco has been paying all of its profit each as dividends with a pay out of $5.51 from full year earnings of $5.81 in 2014.
The company is a subsidiary of British American Tobacco Company and is listed on the Trinidad and Tobago Stock Exchange (TTSE), it manufactures and markets cigarettes. The stock last traded at $126 on the TTSE. Earnings per share for the quarter is, $1.34 versus $1.26 in 2014 and for the year to date, $4.20 versus $3.91 in 2014 and the net book value works out at $4 per share with the equity of $336 million. Earnings per share should reach $6.25 for 2015 and would result in a PE of 20 times earnings.

Q4 Profit jumps 215% at AMG

AMG Packaging enjoyed a great year to August, with 74 percent jump in profits to $79 million over 2014 and 86 percent before expenses incurred for the new toilet tissue operation. For the last quarter of the fiscal year things were even better with a 215 percent jump to $27 million.

AMG Packaging report big gains in profit for 2015

AMG Packaging report big gains in profit for 2015

Earnings per share for the full year to August amount to 78 cents, up from 45 cents in 2014.
A sharp $4.5 million fall in fuel cost and repairs and maintenance respectively, a 50 percent cut in selling and distribution expenses amounting to $7 million, and lesser declines in wages, electricity along with an increase in revenues helped to improve gross profit, margins and the results for the year.
Gross cash flow generated from operations came in at $92 million, up from $58 million in 2014. Going forward its unclear what impact the new operations will have, barring any major losses IC Insider is forecasting $1.05 per share after tax for 2016, the first year of reduced taxation will be payable. The company paid dividends of $18.4 million during the fiscal year and in the prior year $20.5 million.
Looks like a greater stability in raw material cost and attention paid to cost in a number of areas, paid rich dividend in the past four quarters and in particular the final quarter. Cost of sales fell from $491 million in 2014 to $484 million and gross profit jumped to $149.4 million from $116 million, an increase of 28.6 percent. Revenues rose moderately by 3 percent for the quarter to $172 million and 4 percent increase for the full year to hit $633 million. While the growth in revenues may not appear electric closer look indicates a growth of around 7 percent on a quarter over quarter basis for the last 4 quarters.
Administrative expenses rose from $48.5 million to $51.4 million in 2015 and finance cost declined form $10 million to $8.7 million.
Borrowings grew to $151.6 million while cash funds rose $64 million from $22 million in 2014. The balance sheet shows $59 million deposited to purchase equipment for the new tissue operation. Current assets stood at $335 million and current liabilities at $60 million. Equity capital grew to $377 million from $316 million.
AMG Packaging is in the business of manufacturing paper based boxes for the packaging and its shares are listed on the junior market of the Jamaica Stock Exchange and last traded at $4.80 with a gain of 82 percent for the year to date.

Lasco Distributors blow out profits

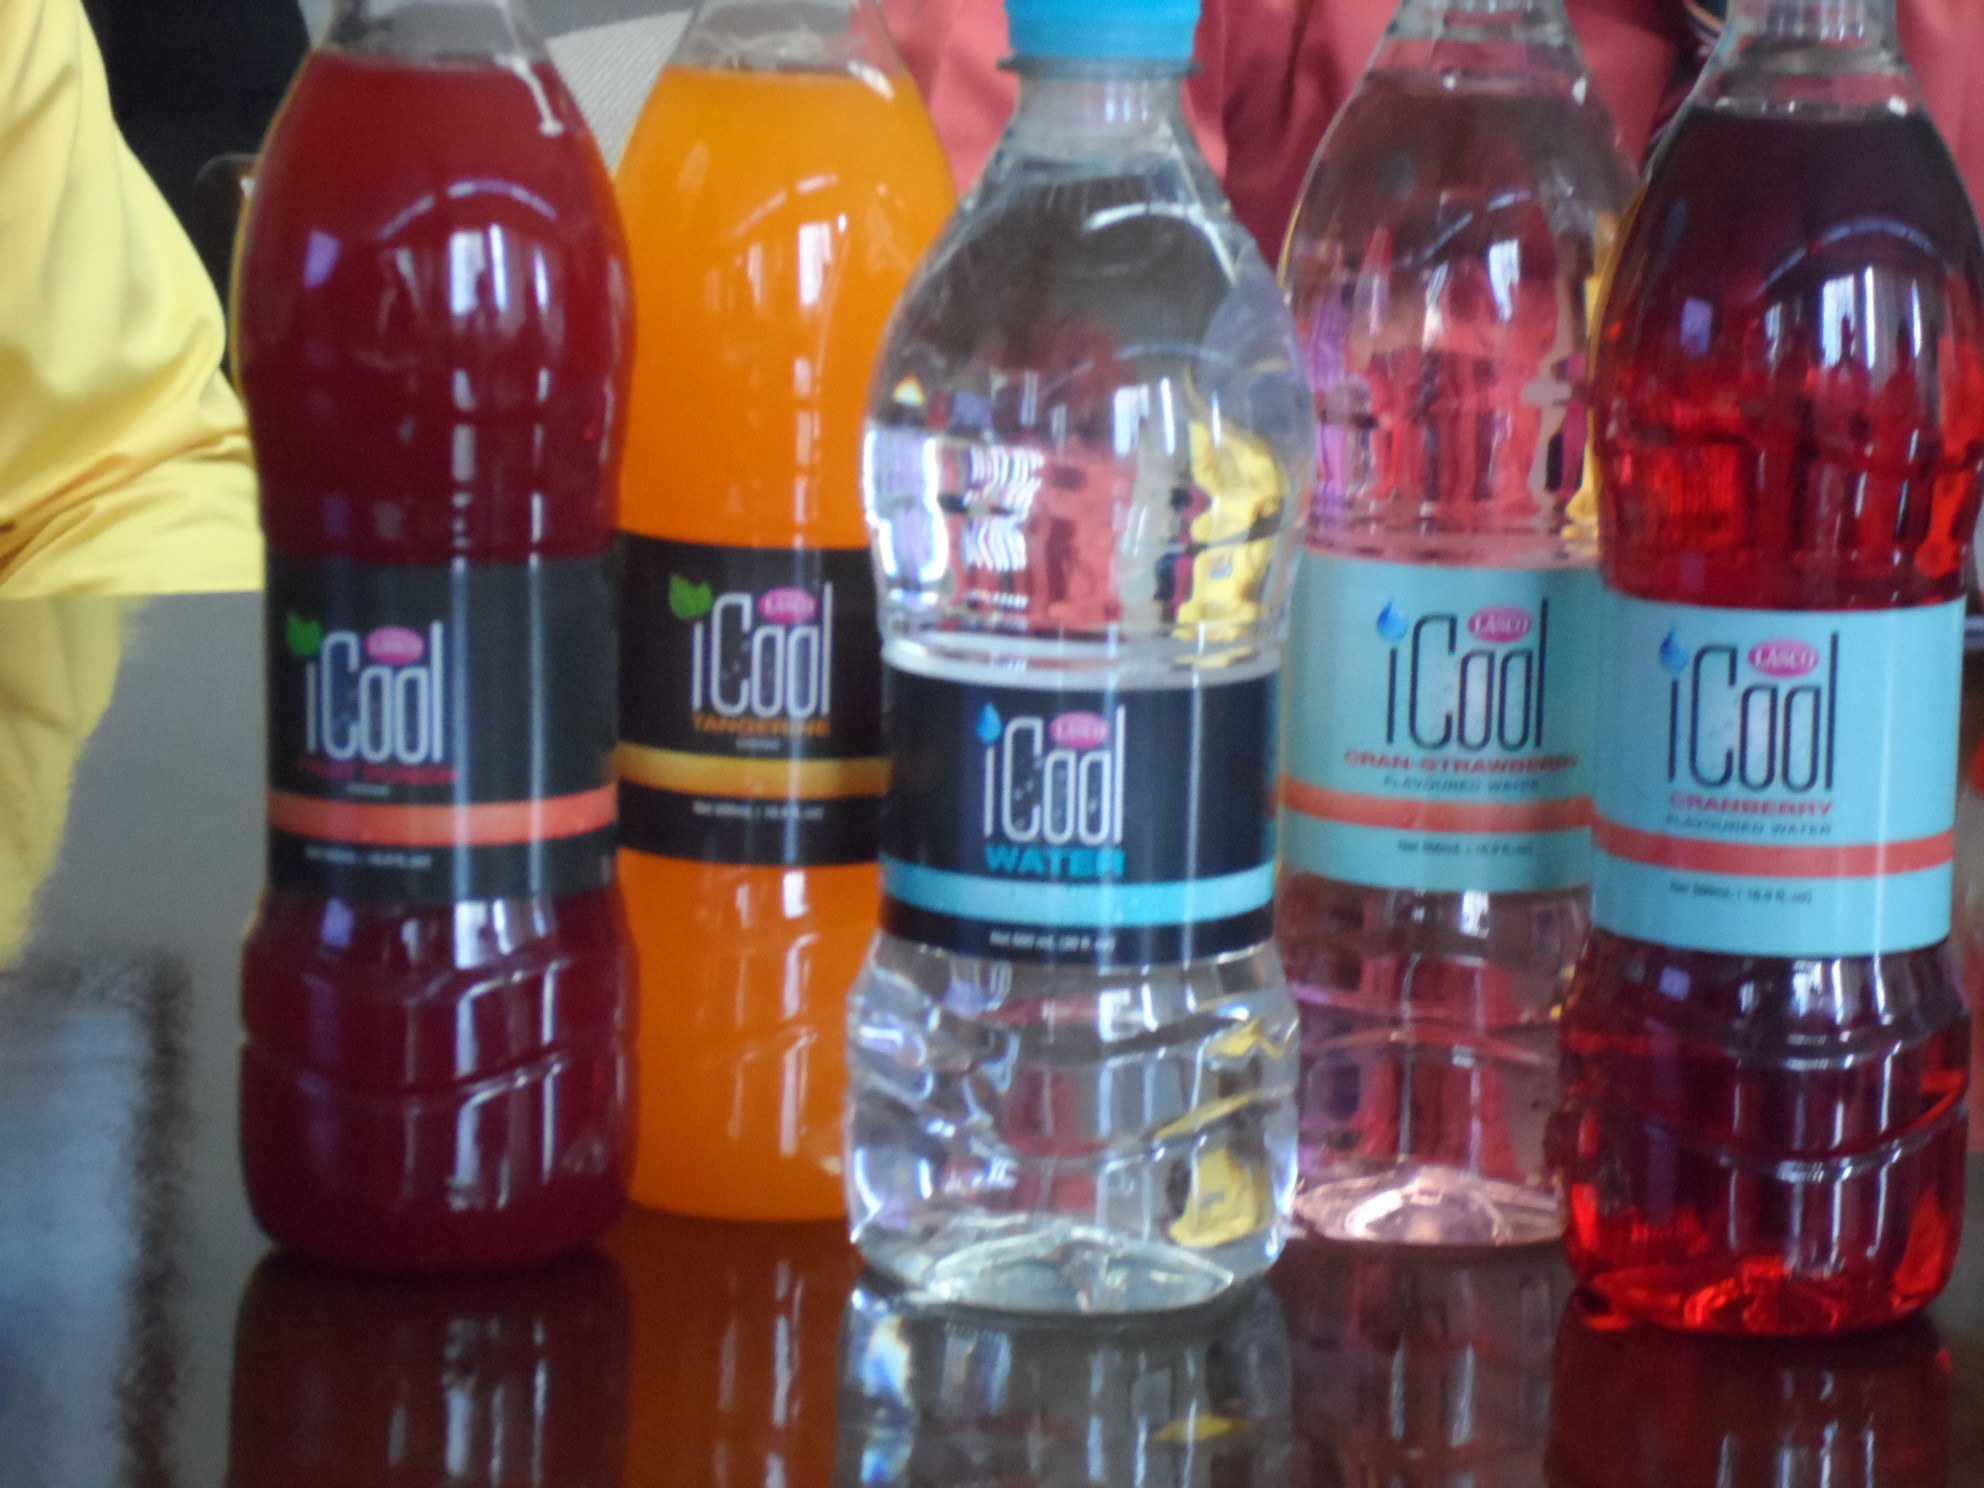
Lasco Distributors with responsibility to distribute "I Cool" drink.

Lasco Distributors with responsibility to distribute “I Cool” drink.

Lasco Distributors reported an 87 percent increase in profit after tax for the six months to September, of $379 million over 2014 and a 121 percent increase in the September quarter of $247 million over the similar quarter last year.
The Gross profit for the period was S1.1 billion, an increase of $299 million or 36 percent over the prior year. The Gross Profit margin for the quarter was $628 million, or 32 percent over the same period last year. Gross profit margin for the august 2015 quarter is 17.26 percent versus 17.5 percent in 2014 and year to date 16.2 percent in 2015 and 16.28 percent in 2014.
The huge gain came from increased revenues of 34 percent for the quarter, amounting to $6.95 billion and 36 percent for the six months of $3.64 billion.
“This growth was driven mainly by contributions from our iCool and Unilever lines of business, both of which have been doing very well”, Peter Chin, Managing Director reported to shareholders in the directors’ report accompanying the financial data.
An interesting element of the results is the 10 percent growth in revenue over the June quarter a continuation of the quarter over quarter growth evident from late in 2014 with an average of 8 percent for the last three quarters.
Earnings per stock for the six months amount to 11 cents and 7 cents for the quarter. IC Insider projects profit of 34 cents for the current year and 50 cents for the year to March 2017.
Cost were held well below the growth in revenues with Operating Expenses in the latest quarter rising to $396 million from $377 in 2014 and for the six months this year the company incurred $779 million versus $658 million in 2014 for a rise of 18 percent.
Cash flow from operations increased by 94 percent to $391 million from $202 million for the similar period to September 2014 swelling Cash and Equivalents at the end of the Period to $904,043 compared with $191,277.
The company’s shares are listed on the junior market of the Jamaica Stock Exchange. Its principal activity is the distribution of pharmaceutical and consumable items, ii distributes all of Lasco Manufacturing’s products locally.
The stock may be considered fully priced currently with a PE of 10 being one of the higher priced junior market stocks, but with strong growth expected and lower interest rates to come, investors with a long term time horizon may want to accumulate from now, bearing in mind the limited supply available.

Dolphin Cove Q3 profit gains 17%

Image courtesy of Bill Longshaw/FreeDigitalPhotos.net

Image courtesy of Bill Longshaw/FreeDigitalPhotos.net

Dolphin Cove reported a 4 percent increase in profit after tax for the nine months to September, of $412 million over 2014 and a 17 percent increase in the September quarter to $128 million over the similar quarter last year.
Cash flow from operations increased by 26 percent to $486 million, compared to $385 million for the similar period to September 2014.
Earnings per stock unit for the nine months amounts to $1.05 and 32.6 cents for the quarter and could end around $1.40 for the year, for the full 2014 year earnings was $1.12.
“The improved results were largely reflective of a 10 percent growth in ancillary revenue and better receivables collections in 2015. There was also noticeable growth in the number of customers who visited our Hanover and Half Moon Parks and the Group also benefited from the devaluation in the Jamaican dollar in the third quarter, 2015 as most of our income is earned in United States dollars”.
“Overall revenue grew by 5 percent although, as anticipated, there was a reduction in the number of hotel guests who visited the Ocho Rios Park given the temporary closure (for expansion) of one of the major hotels in this region. The resulting reduction in revenue and profit in this area was however surpassed by strong growth in the other operating segments and an increase in local business on account of our summer promotion which was introduced in September quarter, 2015”.
Stafford Burrowes and his wife

Stafford Burrowes and his wife

“Increase in operating expenses was restricted to 7 percent, for the year to date and 6 percent for the third quarter and was primarily due to additional depreciation, which resulted from the revaluation of buildings. The staff benefited from salary increments, which came into effect in the latter quarter of 2014”, Stafford Burrowes, Chairman and Chief Executive Officer and William McConnell, Chairman of Audit Committee stated in a report accompanying the interim financials.
An interim dividend of 15 cents per share will be paid in December quarter. This brings the total dividend declared to date to 45 cents and equals the same level of dividend which was declared as at September quarter, 2014.
Property, plant and equipment jumped to $2.19 billion at the end of September from $1.11 billion at the end of September last year as revaluation surplus added $930 million. Revaluation and retained profits helped to swell equity to $2.7 billion while borrowed funds stood at $240 million.
The company’s stock is traded on the Jamaica Stock Exchange and closed on Wednesday at $10 but with these results should be heading back upwards to the $13 range before long.

Election spend pushes One Caribbean Profit

One CaribSpending on election advertising in Trinidad & Tobago and new technology employed by helped One Caribbean Media to post strong profit for the September quarter with an increase in revenues of 9.4 percent to TT$147.4 million in the September quarter and with an increase of 60 percent in after tax profits of $30 million.
Earnings per stock unit for the nine months to September, is 93 cents and 43 cents for the quarter and could end around $1.30 for the year.
For the nine months, profits rose to $64.4 million from $57.8 million, in 2014 from nine months revenues of $385 million, that is down on the $402 million generated in 2014. The highest income generated period is the final quarter for the year, with increased demand during the Christmas period.
For the 12 months to December last year, revenues came in at $548 million with profit of $85 million. Helping the performance is a drop in Direct cost from $88 million in the 2014 quarter to $83 million for the 2015 period and for the nine months for 2015 to $234 million versus $260 million in 2014, administrative cost were held tightly with a small increase.
The company’s stock is traded on the Trinidad & Tobago Stock Exchange and closed on Wednesday at $22.50. the company operates radio, TV stations in Trinidad and Tobago and operates in the print media as well.

Ambush Marketing be careful

Danielle Stiebel, Associate , Myers, Fletcher & Gordon (MF&G), during her presentation on “Ambush Marketing”.

Danielle Stiebel, Associate , Myers, Fletcher & Gordon (MF&G), during her presentation on “Ambush Marketing”.

Ambush Marketing is seen as a clever marketing strategy, but it has negative effects that impede on the rights of sponsors and other corporations who are victims of such acts.
Ambush Marketing is “a promotional tactic designed to associate a company, product or service with a particular event, or to attract the attention of people attending the event, without payment being made for an official sponsorship”, attorney Danielle Stiebel of Myers Fletcher & Gordon (MF&G) said in delivering a presentation on “Ambush Marketing” at a Wednesday Morning Breakfast Seminar hosted by the Jamaica Chamber of Commerce (JCC) and MF&G recently at the New Kingston Conference Centre.
Stiebel cautioned that marketers while being creative in their campaigns must avoid infringing various event players’ rights. In like manner, she said that in order to safeguard against ambush, sponsors must prepare well drafted sponsorship agreements that adequately protect their rights and provide for sufficient remedies in the event of breach. She also emphasised the need for organisers/promoters to be more vigilant in protecting sponsorship rights through proper protective and enforcement measures.
Earlier this year there was an outcry by Cable & Wireless one of the major sponsors at Boys and Girls alethic championship in Kingston about ambush marketing by one of it’s competitors at the event raising awareness in the topic.