 The Jamaica Stocks Exchange stock rocketed from $1.57 to a record $15.50 topping the market as the best performing stock over 52 weeks with gains of 887 percent. The JSE benefitted from a big jump in profits from $8 million in 2014 to $139 million in nine months to September this year, as revenues jumped from $242 million in 2014 to $521 million.
For the quarter, profit amounts to $37 million up from $11 million in 2014, from operating revenues of $157 million versus $89 million in 2014. In addition to operating revenues, the JSE earned $16 million from investment income in the latest quarter, compared to $8 million in the September 2014 quarter and $34 million in the nine months in both years.
Earlier in the year, IC Insider stated, “the stock remains IC Insider BUY RATED and is now available at $3.50 which it last traded at, but won’t remain that way forever and investors should be buying this one for big long-term gains,” since then the stock has shot up to $15.50 for a gain of 933 percent for the year.
 For the September quarter, cost rose from $90 million to $109 million due mainly to staff cost jumping b $12 million. For the nine months, cost rose from $273 million to $340 million with staff cost accounting for $20 million of the increase and securities commission fees jumping to $37 million from $10 million in 2014.
The exchange has cash and investments of $448 million with a working capital ratio of 2.4:1 and equity of $624 million, there is no borrowed debt on the books.
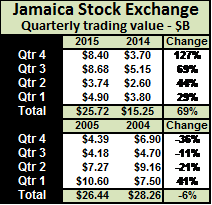
Factors that investors should be considering looking forward which will be critical to the fortunes of the stock exchange are the levels of trading that could point them to future income and profit. Up to December 4, this year, the JSE traded $8.4 billion in normal trades compared to $3.7 billion in December 2014, in the September quarter, trading amounted to $8.68 billion up from $3.74 billion in the June 2015 quarter and $5.15 billion in September 2014. The increase in the 4th quarter stock trading activity to date, is just below the 3th quarter level, in addition there will be a full quarterly income from repo business.
 In the March quarter 2015, a total of $4.9 billion was involved in trading up from $3.8 billion in March 2014. Both the December and the March quarters in 2015 have a few one off type trades, regardless the trend is pretty clear pointing to the possibility of a strong 2016. The last two quarters suggest that trading levels in dollar terms could be up around 40 percent and it could be more. That would mean a sharp increase in revenues for the exchange in addition the managing of the repo business will provide added income for the entire year compared with two months in the September quarter and 5 months for the year to December.
Back in 2004, the market traded $28 billion in regular trading activity when the Jamaican dollar was trading around $62 to the US dollar with trading in 2005 being slightly behind at $26 billion. Trading would need to get to $51-55 billion for a year to match trading levels back in 2004 and 2005.
Profit should close out the year on a high with monetary trading levels set to exceed that of the third quarter and well ahead of the fourth quarter of 2014. IC Insider is forecasting earnings of $1.40 for the 2015 not factoring the trade that could flow from the Heineken buyout of the minority shares in Desnoes and Geddes.
JSE stock up 887% could end higher
Profit break out for Scotia in 2016?
Scotia Group Montego Bay.
Net interest income after impairment losses for the year was $22.9 billion, marginally above 2014 resulting in a reduction in the impairment losses on loans by $241 million or 15.0 percent, this is “due to enhanced adjudication, monitoring and collection efforts. The Group continues to report strong growth in loan volumes during the year, particularly our Residential Mortgages, Consumer, Small Business and Commercial portfolios; however net interest margins continue to decline due to lower market interest rates and the competitive environment”, Scotia stated in their media release accompanying the financials.
Jackie Sharp – CEO Scotia Group
Total assets increased year over year by $25.9 billion or 6.4 percent to $433 billion as at October 2015 due primarily to increases of $8.8 billion or 6 percent in Loans to $154.5 billion, increase in investment and pledged assets and $9.2 billion in other assets
The group reported earnings per share of $3.19 for the year and $1.26 for the last quarter and seems poised to generate earnings around $4 for the 2016 fiscal year.
tTech offer seems a buy
 tTech a company most investors would hardly have heard about, will be going to the capital market this month, to raise approximately $50,263,900, by the issuing for subscription 25,652,000 ordinary shares to the general public and special persons related to the company at $2.50 each.
In reality only 16.4 million are allocated for the general public, a relatively small number. The Company that was formed in 2006 currently provides outsourced IT solutions to businesses currently in Jamaica. IC Insider’s preliminary assessment indicates earnings per share around 40 cents before taxation for a PE of 6.3 and would make the stock a buy.
The purpose of the offer is to provide working capital support to its operations and in order to allow the Company to augment its productive capacity and thereby to take advantage of new business opportunities as well as benefit from listing on the stock exchange and improve staff compensation by allowing them to buy the shares that are bound to increase sharply in price after listing.
The Company estimates that the expenses in the Invitation will not exceed $10 million. Subscription opens at 9 am on December 16th, 2015 and closes at 4:30 p.m. on the December 18th, 2015, subject to the right of the Company to shorten or extend the time for closing. If the Invitation is fully subscribed and is successful in raising $50,263,900, the Company will make an application to the JSE for the Shares to be admitted to the Junior Market. The company has been profitable with revenues growing at an attractive rate. The Company has adopted a dividend policy of paying 25 percent of profits each year.
All completed Application Forms must be delivered to NCB Capital Markets.
IC Insider will have a fuller report at a later date.
Cayman could be lucrative for Grace
 Grace Kennedy Money Services will be expanding operations into the Cayman Islands through GraceKennedy Money Services (Cayman) Limited (GKMS Cayman), a member of the GraceKennedy Group and authorized agent of Western Union, CEO Don Wehby announced recently.
With this new market, Grace Kennedy through its money services subsidiaries now represents Western Union in ten countries across the Caribbean, the other nine being . Jamaica, Trinidad and Tobago, Guyana, St. Vincent and the Grenadines, St. Kitts and Nevis, Antigua and Barbuda, Anguilla and Montserrat and the British Virgin Islands. The market should be quite lucrative for the Grace Kennedy group, as it is the fourth largest country from remittances into Jamaica with US$124 million entering the island from the tiny group of island, according to Bank of Jamaica data, but the market could be a challenging the going forward with concern about money laundering within the region.
Scotiabank will be partnering with Grace Kennedy and Western Union to deliver money transfer services to the residents of the Cayman Islands.
GKMS Cayman will initially have a total of four locations in Grand Cayman and one in Cayman Brac, all opening Monday to Saturday. “There is a vibrant community in the Cayman Islands and we look forward to not only welcoming our new customers into the GKMS family, but working with all stakeholders and contributing to the development of their communities,” Allen added.
It’s official, NCB to buy into Guardian
 It is now official National Commercial Bank (NCB) will be acquiring nearly 30 percent of Guardian Holdings subject to regulatory approvals, making them the largest shareholder in the Trinidad based company that was previously controlled by Jamaica Mutual Life.
The announcement now confirms the ICInsider.com report earlier in the year of NCB’s strong interest in the insurance group of companies. The move is in keeping with IC Insiders’ earlier understanding that both NCB and Proven Investments were targeting approximately 36 percent of Guardian, with the targets being – Tenetic Limited block of 35.84 million which, amounts to 15.46 percent of the company and Arthur Lok Jack’s direct holding of 6.29 percent or 14.59 million units. Arthur Lok Jack’s is listed as having a beneficial interest in Tenetic. Royal Insurance Trinidad holds 22.33 million units or 9.63 percent and RBC Trust T&T controls 4.99 percent or 11.57 million shares. The release from the Guardian shareholders indicates that IFC, who recently bought into Group, is one of the sellers, with no mention of RBC.
The acquisition of Guardian would be a complete reversal, returning the company to its Jamaican roots. Guardian was once majority owned by Jamaica Mutual Life, who sold out their holdings sometime before they ran into problems in Jamaica and folded. The Jamaican entities consider the company to be clean, well run and considerably undervalued. Guardian last traded in Trinidad at TT$13.90.
 Guardian is primarily a Life Insurance company but also owns a general insurance arm. NCB operates the well known OMNI Life Insurance Company. Part of the likely synergy in future would be a merger of general insurance companies that both entities own, with Omni to be sold to the Life Insurance arm, resulting in economies of scale. The possibility exists that an expanded general Insurance company could be listed on the stock exchanges within the Caribbean, thus spreading the risk associated therewith. Guardian’s profit attributable to equity shareholders for the nine months to September was $235 million, down from $286 million for 2014.
Net Income from Insurance Activities grew by $80 million to $533 million from $453 million in 2014, however. Investment activities generated net income of $527 million as against $629 million in 2014, a result significantly affected by the fair value losses of $66 million (2014 gains $27 million) that were occasioned by extreme market uncertainty during the month of September. IC Insider estimates that NCB could see profits rising around 40 cents per share for the 2016 financial year if the deal is finalized soon and on the assumption that the price is around the last traded price of the stock.
Caribbean Flavour(ing) future profits
 “With the price of the stock, trading at $2.55 for a PE of just over 3 and 2.3 based on IC Insider’s forecast, (is) indicative of much upside potential,” was how Caribbean Flavours was assessed back in August this year, as the stock was elevated to the BUY RATED ranking after the company released its full year results to June.
In the June posting, IC Insider stated, “The company seems poised to hit earnings of 65 cents per share, for the June 2015 financial year, making it attractive for some short-term gains, with the current price of $2.09, at a PE ratio of 3 times earnings.”
Focusing on the end results of Caribbean Flavours & Fragrances for the year to June 2015 with increased profit of 22 percent over 2014 would lead one to look elsewhere, but that would be a big error. For while the nine months to March showed profit down marginally to $39 million from $40 million, profit for the March quarter was up 20 percent over March 2014 quarter, the June quarter increased by 143 percent to $18.77 million from just $7.6 million for June 2014.
The company followed up the improved results for the March and June quarters, with another quarter of strong performance to September, with a 51.3 percent increase in net profit to $20.36 million over the $13.46 million recorded for the similar period in 2014. The improved profit flowed from sales for the quarter jumping 38.20 percent to $87.46 million, compared to the $63.29 million recorded for the same period in 2014.
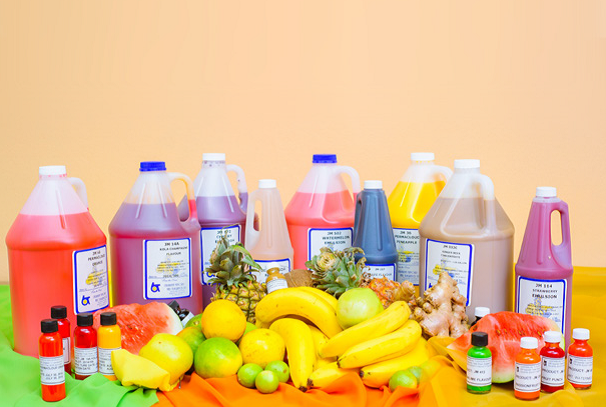
Caribbean Flavours’ produce with ingredients – the stock closed at a new high.
“The gross profit showed an increase of 28.91 percent moving from $25.487 million to $32.856 million as per our first quarter’s performance. The Company will continue to refine and improve our purchasing strategy in order to extract the necessary efficiencies and improve our cost of sales and gross profit.
The company continues to manage its administrative and general expenses within budget and compared to the 2014 quarter, there was only a 4.4 percent increase,” the report went on to state.
The future looks much brighter than the past year, for the company that manufactures and distributes flavours mainly for the beverage, baking and confectionery industries and also sells food colouring and fragrances. In responding to questions posed at the annual general meeting held on Wednesday 25 of November, directors indicated that the strong performance enjoyed in the September quarter continues into the December quarter.
“We have hardly scratched the surface of the potential market” Derrick Cotterell indicated, “we have moved into the Dominican Republic and Canada where there is much potential for growth and with renewed efforts and products the locally Jamaican market as well”. Cotterell stated that they have increased research into new products such as fragrances and this has opened up new opportunities for them. Trinidad, Cuba and Haiti are countries with potential for growth, they indicated but Haiti is said to be a difficult market to break into but they have contacts there that should make it possible. In addition to the focus on research and developments for new products and new customers the company said they were able to source some of its raw material more cheaply than before.
According to the company’s board, in their comments on the 2015 annual results “the economic environment has allowed the company to grow its revenues and profits by securing new markets for fragrances and increasing the volume of sales of flavours to existing and new customers in foreign markets. Based on the outlook for the coming year, it is expected that the company will continue to improve its profits whilst increasing its market share in the domestic and overseas markets”.
IC Insider projects profits for 2016 at $99 million or $1.10 per share with increased sales and improving profit margins and $1.50 for the 2017 fiscal year. Company is free of interest bearing debt and has net current assets of $221 million including cashfunds of $103 million.
Huge profit turn at Honey Bun – BUY RATED
 Honey Bun turned around a loss of $17 million in the September 2014 quarter into a profit of $4 million in 2015 and a profit of only $23 million into a one of $68 million for the 2015 fiscal year or earnings per share of 72 cents.
The performance and IC Insider’s forecast for the next two years, (See EPS forecast below) have elevated the status of the stock to BUY RATED.
The change came from a 22 percent rise in revenue in the quarter to $215 million from $169 million in 2014 and from a 19 percent growth in revenues for the full year, to $887 million from $747 million in 2014. The profit in the September quarter is a major achievement for the company it being the first time since 2012 when a small profit of $550,000 was realized that the company is reporting a profit.
“The company services lots of schools and so the summer months are normally reduced due to the holiday season for July and August. We will always have this challenge but we have somewhat overcome a significant portion of it by way of the development of new products that are not directly geared for schools and by targeting other markets also.
One Honey Bun’s Products
Helping the growth in profits was an improvement in gross profit and gross profit margin with the latter being 42.8 percent up from 41 percent in 2014 and from a 9.5 percent increase in administrative and other expenses, selling & distribution costs of $307 million from $280 million.
Investments, cash and equivalents rose to $92 million, net current assets stood at $102 million, borrowed funds fell from $73 million in 2014 to $51 million while equity rose to $368 million.
The company’s shares are listed on the junior market of the Jamaica Stock Exchange and last traded at $5.50, with the price being up 164 percent since 2015, and now sports a PE of 7.6 times 2015 earnings. IC Insider is forecasting earnings per share (EPS) of $1.15 for the 2016 fiscal year which gives it a PE of 4.8 and EPS of $1.70 for 2017.
The company advised that the Board of Directors will meet on Monday, December 7 to consider the declaration of a dividend. An interim dividend of 12 cents per stock, amounting to $11.3 million was paid in May this year.
Ciboney shares doubled but why?
 Ciboney traded 1,186,460 units on Wednesday at 16 cents for a 52 weeks’ high, but the stock closed with the bid at 16 cents to buy 1,813,540 shares as investor push to price up to levels not seen since 2004 when it traded as high as 32 cents. The stock has doubled since November 9 when it traded at 8 cents. On the September 24 there were trading in 4.36 million units and 5.36 on October 26 and 2.1 million units on November 16.
Why the interest in the stock of a company that reported a loss of $1 million for the quarter, ending in August and seems set to lose $4 million for the year ending May 2016? For the 2015 fiscal year, a loss of $5 million was reported and $8.7 million in 2014.
Ciboney has whittled down the funds it holds in cash and investments, to $14.5 million from $20.6 million at August 2014 and with the losses could be out of cash in another two years, unless they were able to sell the land which the company owns. The last valuation was done in January 2015 which gives a value ranging from $200 million to $215 million, but is on the books at $44 million. If the valuation of $207.5 million was fully booked, the net book value would be around 31 cents per share. So far Ciboney has not obtained a buyer prepared to pay a price close to the market value.
IC Insider has been informed that two parties have expressed an interest in acquiring the company in part. One proposal is without the land, with the land to be placed in a separate company to be formed to hold it in proportion to existing share ownership of Ciboney. The other would see FINSAC retaining the land in possible exchange for either a cash injection and or transferring the FINSAC shares to minority shareholders. The deadline for the offer is Friday this week,any agreement would be subject to a vote by shareholders. If the former proposal succeeds, cash inflows would be minimal initially and shareholders would have to wait on the sale of the land for further payment. In the second case, investors would see no cash but the share value could be between 30-40 cents, with the possibility of losses could be eliminated. There is no guarantee that any of the proposals will be accepted. In the meantime, the price of 16 cents is well under the 31 cents adjusted net book value.
Confidence Vote in Xfund & more

Hotel property owned by Sagicor Real Estate Fund
Most recent reports show that a director of Sagicor Real Estate X Fund demonstrated strong faith in the future of the company, by purchasing 121,500 shares on November 20 at $9.90. The fund reported consolidated net profit attributable to stockholders of $1.04 billion for the nine months to September or 63 cents per share with net profit for the September quarter ending at $349 million or 17 cents per share. The quarterly results include capital gains on financial assets and liabilities of $279 million and $746 million for the year to date. The net asset at the end of September amounts to $6.83 with the selling at a premium of 46 percent above net assets.
Elsewhere, at Caribbean Flavours connected parties, purchased 212,000 units of the company’s shares on November 17 at $5, the stock last traded at $6.30 and should go higher with recent results showing growth in profits.
Insiders purchased NCB shares recently.
Lasco Financial Services that is expanding into new areas, saw a connected party purchasing 393,189 shares between November 5 and 23. At Sagicor Group an Executive and two Officers collectively purchased 497,634 of the company’s shares under the Executive Long Term Incentive Scheme on November 16 and 17, but on November 18 an Executive sold 365,400 shares.
Not all insiders were buyers, as Kingston Wharves advised that connected parties sold 12,523 units of its shares on November 17 and 18, while at Mayberry Investments connected parties purchased 4,058,034 units of the company’s shares while a related party sold 3,500,000 units on November 17 and a connected party purchased 127,443 shares on November 18.
Caribbean Cream informed the stock exchange that a connected party sold 750,000 shares between October 28 to 30, while a related party purchased 2,895 shares on October 16.
Jump in Gleaner’s Q3 profits by 70%
 The Gleaner Company, producers of Jamaica’s oldest newspaper, earned increased profits for its September quarter. The North Street based institution earned $27 million profit for the quarter, 70 per cent more profit than a year ago.
The 2015 results are commendable as its revenues dipped to $777 million or 9 percent less than a year earlier in the quarter, including a fall of $26 million in investment income to $54 million for the quarter while media income fell $68 million for the same period.
For the nine-months, the Gleaner made $130 million net profit or 122 per cent more than the $58.6 million earned a year earlier. Revenues continued its downward drift by 5.6 percent to $2.38 billion, partially helped by a fall of $34 million in investment income to $90 million while media income fell $120 million for the same period
Gleaner enjoyed other operating income of $61 million and $63 million in 2014 as a result of gains on foreign exchange on investments and Finance income includes interest on loans. Consequently, the profit resulted from efficiency gains in slashing administrative and ‘other operating’ expenses during the quarter.
Interestingly, however, with the jump in profit the company ended the quarter with $93 million in cash flow down from $164 million from operation in 2014 period and ended with $37.7 million cash in the bank at September 2015 and $42 million September 2014 and $772 million in investments up from $690 million at September 2014.
 The Gleaner continues to prepare its media operations for the merger with the Radio Jamaica Group, another legacy media entity. It will create one of the largest broadcast and print media entities in the Anglophone Caribbean. Plans to merge were announced on August 5, 2015, with the merger is expected to be concluded by year-end, subject to the approval of a splintered shareholders of Radio Jamaica. There is little doubt that the Gleaner’s shareholders will not approve, with the company’s Chairman in control of a large block of the Gleaner’s shares.
Net asset at the end of September is $2.32 per share. The stock is priced at $1.90, with earnings per share of 10.76 cents for the nine months period and 2.27 cents for the quarter. The company seems on target to earn 20 cents per share, for the full year.
Gleaner’s shareholders will get the equivalent of a third of each of the RJR existing shares as well us retain shares in the remnants of the Gleaner with net assets around $1.70 per share, if the merger proceeds. But the overall gains will be well in above the current combined value of $3.53 based on the $5.20 price of RJR shares last sold at with indication of further rise to come, based on a big jump RJR’s revenues and profit in the September quarter.