
One of the branded product distributed by Paramount Trading
The improved results for the latest quarter, came from a 39 percent climb in revenues over the similar period in 2013, with revenues of $231 million versus $166 million in 2013. The latest quarter’s revenues are the highest the company has had, since listing in 2013. Gross profit margin jumped from 46 percent in the August quarter to 58 percent in November and from 49 percent in the same quarter in the 2013. For the six months to November 2014 the profit margin increased to 53 percent from 49 percent in 2013.
The company launched a new line of lubricants during the August quarter but sales are in their infancy at the time. According to a company executive in commenting on the August results, the increased sales was mostly from new customers added as well as increased sales of a product to an existing customer, who was not supplied with that product last year.
Administrative, selling and distribution cost, which fell in the August quarter came out at $33 million from last year’s $31 million. For the six months period these expenses amounted to $64 million versus $66 million in 2013. With the release of the August figures IC Insider.com had projected profit to come in around $152 million in the current fiscal year or around $1.15 per share, the latest figures suggest that earnings per share will probably be closer to $1.40. At the current price of $2.80 the stock would be priced at a PE of only 2.2 making it a very good buy, bearing in mind that that many junior listings have been valued around 8 times earnings in the recent past, and around 6 times now, with the latter PE, the price should potentially get to $8.40 at the low end and $11 at a PE of 8. The company seems poised to raise its next fiscal year earnings to a much higher level than the above forecast (IC Insider.com forecast $2 per share for 2016) so there seems to be much room for the stock to deliver high returns to investors. These figures do not reflect income or profit that should flow from the company’s acquisition of the Tradewell chemical line which they purchased from the Lasccelles group or any other acquisition that they may undertake in the near term. It also assumes that revenues which include some new customers will repeat going forward.
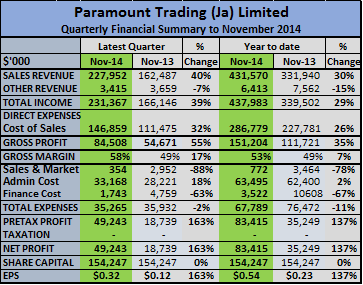 Financials| The profit to-date provided a strong 44 percent annualized return on average equity. Borrowed funds amounted to only $38 million, compared to the level of equity. Cash is up from $65 million but dividends of $23 million was paid out in December. Receivables which was at $178 million in August from $172 million at May, is down slightly to $172 in November, and represents an improvement considering the strong sales increase. Inventories at $203 million at the end of August and May, this year, jumped to $275 million in November but payables moved up moderately to $136 million from $128 million at the end of May.
The performance of the company during the quarter and for the 2014 justifies IC Insider.com elevating the stock to BUY RATED status in mid-October last year.
[…] and rising cost in the February quarter over the November quarter were the noticeable features for Paramount Trading. The result, lower profit only $26.4 million versus $49.2 million. Profit nevertheless jumped 121 […]