22% percent increased cement sales in Q3

Carib Cement  closed at a new 52 weeks' high of $12

Carib Cement closed at a new 52 weeks’ high of $12

Caribbean Cement sold 22 percent more cement on the local market I this years’ third quarter than they did in 2014 September quarter. “Domestic sales volume for the third quarter exceeded the corresponding period in 2014 by 22 percent and for the nine month period, was 9 percent above the volumes in 2014” Christopher Dehring, Chairman and Jose Luis Seijo Gonzalez, group CEO stated in a joint statement issued along with the September quarterly report.
For the nine months to September 2015, the company ended with a profit after tax of $1.486 billion. In 2014 a profit of only $25 million was realised for the nine months last year. The 2015 results translate to earnings per share of $1.75 at September. For the quarter to September, profit after tax amounted to 72 cents per share or $617 million compared with just $78 million in the 2014 quarter. If the sales trend continues, earnings per share should hit $2.50 for 2015 which includes an exceptional income of $168 million or about 15 cents per share. The company’s stock traded at $15 on Friday and now carries a PE of 6.5 times this year earnings, and seems set to move up in price with these results with the valuation of the most valued stocks on the market being at 10.
Gross cash generated by operating activities amounted to $2 billion and after repaying loans ended at $997 million in cash funds.
Revenue for the third quarter grew by $741 million or 21 percent over the same period in 2014 mainly driven by improved domestic sales volumes and increased clinker exports which compensated for the decline in cement export sales volumes. The company benefited from lower costs of fuels and energy and Interest expense that decreased by 73 percent for the quarter to only $16 million, from $59 million in 2014. For the nine months interest expenses ended at $120 million from $196 million as a result of the company’s financial restructuring initiative resulting in some prepayments of long-term debt in excess of $800 million. Depreciation and amortisation cost, however, rose from $83 million in the September 2014 quarter to $102 million in 2015 and to $296 million for the nine months from $251 million in 2014.
The vastly improved results have changed the financial structure with net working capital jumping from just $360 million surplus to $2 million at September and equity rising to $6.4 billion from $4.8 at the end of September 2014.
C&W shares may fetch over $3 in a takeover

Cable & Wireless with the old Lime brand logo

Cable & Wireless with the old Lime brand logo

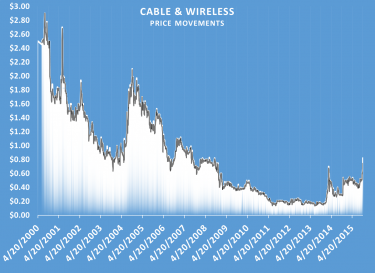
Shares of Cable & Wireless Jamaica (C&W) shot up 22 percent on Friday October 23 to 82 cents, in response to an announcement that Liberty Global, a UK based company was in discussions with CWC Communications PLC (CWC) to acquire it for a consideration in cash and shares, worth US$5.5 billion.
Cable and Wireless shares had become scarce in recent weeks, with one investor IC Insider sources indicated, was seeking 7 million shares to buy, earlier last week at 60 cents each. From as far back as the 8th of October, there were only 4 million units on offer between 55 cents and $1.21. By Thursday the supply dropped even more with trading taking place as high as 67 cents. At 12.30 on October 22, there were 453,964 shares on offer at 67 cents, with 5,000 units sold out of this amount by the close of the market. A total of 305,850 units were on offer at 70 cents, with the next at 90 cents, with 5,000 units. At 99 cents there were 233,730 units, at $1 one block of 877,723 units with the next lot of 10,000 at $1.71, the next 130,169 shares at $2 and 1.66 million units at $3.75. That not a lot for a stock that usually trade in millions of units.
Only 5,850 shares traded on Friday at 82 cents and demand swelled to more than 5 million units at the close to buy at 82 cents. Supply disappeared with only 4 offers listed, ranging for 10,000 units each at $1.20, $1.21 and $1.70 and then 2.66 million units at $3.75.
The question on investors’ minds, is where will the price settle? One broker indicated that it will trade at $1 on Monday if there is supply. With the imbalance between supply and demand, a higher price than that seems imminent. Some Investors are wondering why some buying on the buyout news of the parent when there is uncertainty if the Jamaican shareholders will be bought out as well if the deal goes through. Some are looking at the Diageo transaction with Desnoes & Geddes and speculating that the same could happen here.
IC Insider.com has the stock as BUY RATED from February 2014 on the basis of a turnaround in the financial fortunes of the company. Based on what’s happening locally the current price can be justified as the company is now in a position to be reporting profits, with rising revenues and falling cost. If the deal with CWC goes through, (that does not seem likely at the stated price) and the minority shareholders in C&W were to be bought out, IC Insider went to work to see how high the price could be, in a takeover.
CW grph 10-15C&W had major improvement in earnings in the June quarter, with EBITDA rising a very strong 82 percent. Net results saw a sharp fall to a loss of just $303 million, from a loss of $712 million in 2014 as revenues grew 13 percent to $5.45 billion, aided by a 17 percent growth in mobile subscribers and 27 percent increased mobile revenues. Operating expenses were static at $4 billion but finance cost rose to $1.1 billion from $962 million in 2014, depreciation was down and amortization up. Revenues should climbed close to $6 billion in the September quarter and is likely to result in a profit around $200 million before any allowance for tax.
In March 2015, CWC completed the purchase of Columbus International, a fibre-based telecommunications and technology services provider operating in the Caribbean, Central America and the Andean region, for a consideration comprising US$708 million in cash and 1,558 million CWC shares. This resulted in an increase in share capital of US$78 million and the formation of a merger reserve of US$1,209 million. The total consideration, $2 billion for the CWC acquisition resulted in a multiple of 7.8 times EBITDA.
The proposed price of US$5.5 billion being proposed for CWC with EBITDA of US$840 for the combined entities at March, would be 6.55 times EBITDA. Applying this ratio, puts C&W value based on EBITDA for the current fiscal year around $3.30 each. CWC communications paid much higher multiple for Columbus only a year ago which would make it difficult for CWC management to justify to their shareholders a deal that reduced the value of the group with the full benefit of the merger of the Flow operation not yet visible. The proposed buyout price would, however, be more than the market value of CWC, worth 2.6 billion pounds, or about $4 billion, based on its market capitalization on Thursday. John Malone the major owner of Liberty Global already has a 13 percent stake in CWC.

Newly listed T&TNGL rules on TTSE

NGL 19-10-15 The Class B Shares of Trinidad and Tobago NGL Limited was listed on the Trinidad and Tobago Stock Exchange on Monday and gained TT$3 to close at $23 from the offering for sale price of $20. The company saw trading in 18,000 shares valued at $414,000. The stock closed with a bid of $23 to buy 362,287 shares with none on offer, a good sign that the price is headed higher with a PE ratio of less than 10 times this year’s earnings.
The company generated an operating profit of US$15 million for the March quarter of 2015, a fall of 65.5 percent compared to the 2014 quarter. Earnings per share based on the annualised first quarter results, is 25 TT cents. A total of 75.8 million out of 116,100,000 issued shares, were offered to the public to raise $1.5 billion for the government of Trinidad and Tobago.
Activity elsewhere on the Stock Exchange, on Monday ended with 11 securities trading. At the close, there was just 1 stock closing higher, declined and 9 remained unchanged as a total of 33,337 units traded, valued at $651,432. At the close the Composite Index ending with a rise of 3.57 points at 1,150.15, the All T&T Index gained 7.08 to 1,953.33 and the Cross Listed Index was unchanged at 45.52.
Losses| Clico Investment Fund closed with 800 shares changing hands to end at $22.50, after falling 1 cent.
Firm Trades| First Citizens Bank traded 2,851 shares and closed at $35, Flavorite Foods contributed 2,200 shares in trading, to close at $4.80, Grace Kennedy had 2,502 units changing hands at $3.60, TTSE sum 19-10-15Guardian Holdings with 4,986 shares trading, closed at $13.13. Guardian Media traded 888 shares with the price remaining at $19.76, Massy Holdings traded 50 shares with the price ending at $62.46, Republic Bank closed with 28 shares trading for $112, Sagicor Financial Corporation closed with 950 shares changing hands, to end at $6 and Scotiabank ended with 82 shares trading to end at $62.50.
IC bid-offer Indicator| At the end of trading the Investor’s Choice bid-offer indicator had 4 stocks with the bid higher than the last selling price and 4 stocks with offers that were lower.

191% profit surge for Jamaica Broilers

Jamaica Broilers stock traded at $8 for a gain of 98 percent this year to date, partially spurred by 191 percent jump in after tax profit for the July quarter, to $331 million from $114 million in 2014.
JBRevenues for the quarter climbed 13 percent to $9 billion which, compared to the $7.8 billion in 2014. Earnings per stock amounts to 27.58 cents against 9.47 cents in the corresponding period last year.
Gross profit grew much faster than revenues at 32 percent to $2.28 billion over the corresponding quarter last year and gross profit margin rose to 25.54 percent from 21.88 percent in 2014. The fall in world market prices for energy and corn along with the closure of the ethanol operation would have contributed to some of the reduction in direct cost. Distribution and selling cost climbed to $248 million from $226 million and administration and other expenses rose by 17.5 percent to $1.5 billion.
Free cash flow from operations generated $851 million leading to cash and investments of $1.8 billion at the end of the quarter, down from $2.3 billion in 2014 as the company repaid just over $300 million in loans and $545 million in payables while receivables growth consumes $380 million, year over year.
Segment results show the Jamaican operations enjoying a marked improvement over 2014 with segment profit of $697 million in the 2015 July quarter, from $448 million reported last year. “We are recording increased sale volumes in poultry and feed products. In addition our focus on cost containment and improvements in the production processes for poultry and feed are bearing fruit,” the company said in its report to shareholders. The US segment show 31 percent sales growth to $2.07 billion from $1.58 billion in 2014 but slightly lower segment profit of $266 million versus $271 million while the Haitian operation performed below that of the prior year period.JB fact
The company stated that “Operations are now at an optimal level with respect to the sale of our main product –fertile eggs for the broiler industry. We expect steady growth in other product lines in this segment. In the Other Caribbean Operations, Haiti Broilers SA has increased production and sale of table eggs to 13 percent of the market, compared to 8 percent at the end of the first quarter last year. The positive effect of this volume growth has however been neutralized by significant increases in operating costs due to the depreciation of the Haitian Gourde against the US dollars during this quarter. Our move into sustained profitability in Haiti has therefore been delayed. This segment was also impacted by impairment and mark- to- market adjustments, amounting to $44 million, on certain financial assets in two of our St. Lucian subsidiaries”.
Jamaica Broilers should end up with earnings in the region of $1.30 for the 2016 fiscal year ending April compared with 86.4 cents for 2015. The PE for the stock is just over 6 at the current price of $8. The company declared the payment of an interim dividend of 10 cents per share, payable on November 13. In May this year a payment of 9 cents per share was paid.

Knutsford doubles profit

  Knutsford Express more than doubled its profit for the first quarter to August, with a jump of 109 percent to $35.7 million, from $17 million in 2014 and revenues that climbed 38.5 percent to $143 million. The increased revenue “was due to growth in passenger travel” the company stated in its report to shareholders.
Administrative and general operating expenses grew by a much slower 23 percent to $104 million than revenue. Depreciation climbed from $5.4 million to $7.55 million and finance amounts to $3.9 million and is up from $2.3 million in 2014.
Unfortunately the company has not provided information on the composition of administrative and general operating expenses. Based on the last audited financials, the largest cost items are fuel, accounting for around 19 percent of cost, labour for 34 percent and repairs around 10 percent for a total of 43 percent or thereabout.
Earnings per share is 36 cents for the 2015 quarter, putting full year earnings in the $1.60 region.
The company provides a popular coach bus service that plies between Kingston and the North and South coasts of Jamaica. Service was extended to Port Antonio from Ocho Rios earlier in 2015 but will take time to build as more persons become familiar with it. Going forward it is unsure what the opening of the highway to Ocho Rios from Kingston will mean for growth. What is sure it will take less time to cover the route with less operating cost per trip and will allow them to better compete with air travel as the time factor to and from Montego Bay and Kingston will be reduced.
The stock is listed on the junior market of the Jamaica Stock Exchange and has been trading around $6.10, for some time. These results should give the price a lift as the value is very low compared to others on the market, but management needs to improve on the inadequate manner of reporting the results, if not investors will be skeptical about the financial performance and shy away from the stock.
At the end of the quarter, shareholders equity stands at $250 million and liabilities of just $91 million and current assets of $157 million which includes cash and investments of $79 million and other assets of $61 million that rose from $21 million in May this year.
The company paid a dividend of 15 cents per share on September 15.

Paramount rolls along with more profits

Paramount office

Paramount office

Junior market listed, Paramount Trading reported another quarter of increased revenues and profit with growth of 17 percent in sales to end at $238 million and profit of $42.6 million, an increase of 25 percent for the August quarter over that of 2014. Cost of sales increased by 12 percent much slower than the growth in revenues, leading to an upward movement in gross profit margin, from 32 percent to 34 percent. Distribution cost jumped 70 percent but from a small base, to reach $710 million while administrative cost excluding depreciation, rose 36 percent to $38 million. Finance cost fell from $1.8 million to $1.3 million.
“Year over year, operating expenses as a percentage of total revenue increased 16.9 percent versus 14.9 percent as the company continued to strengthen its team and streamline operations. Paramount has a positive outlook for the rest of the year as it continues to aggressively pursue growth opportunities,” Hugh Graham, CEO & Managing Director stated in a report to shareholders accompanying the financials.
During the quarter the company generated $44 million in cash from operations and ended up with new cash funds of $69 million after reducing the level of receivables by $20 million, payables grew by $33 and Inventory rose by $15 million, putting cash and equivalent at $164 million at the end of the August.
Some of the products the company handles

Some of the products the company handles

The principal activity of the Company is importation and distribution of chemicals and other related products including “SIKA” branded hardware products, whose line of products include anchoring adhesives and sealants principally distributed to the commercial hardware market.
Earnings per share for the quarter ended at 28 cents compared with 22 cents, in the August 2014 quarter and 95 cents for the 2015 year that ended in May. IC Insider forecast $1.45 per share for the full year. The stock trades at $6.10 on the Junior market, placing the PE ratio at 4 with much room for growth in the stock price with nearly half of the junior stocks valued at an average of 8.6 times current year’s earnings with all of those above 7.7 times.
The company will be considering a dividend at a directors’ meeting to be held on Thursday, October 29. The last dividend paid, was 15.1 cents per share on December 12, last year and in December 2013, 13.5 cents. With the 2015 full year profit being up by 57 percent over 2014, investors should see an increase to about 23.5 cents per share being paid this time around.

US$194m for minority D&G owners

Red stripe botJamaican shareholders will make a windfall when Dutch based Heineken bids US$194 million for the remaining shares in the Red Stripe brewery company it now does not own.
It could result in the delisting of Desnoes & Geddes (D&G) similar to what occurred a few years earlier when Italian based Campari bought the bulk of shares in Lascelles deMercado from Trinidad based CL Group triggering a bid for the remaining shares.
Heineken earlier this week acquired nearly three-quarters of the shares in local based brewery from UK based Diageo in a deal spanning Jamaica, Malaysia and Singapore and Ghana totalling US$780.5 million.
“In accordance with the Jamaican Takeover Code, as a result of the acquisition of Diageo’s shareholding in D&G. Heineken will in due course make a mandatory offer for all shares of D&G not already owned by Heineken. If they acquire enough shares to give them 90 percent ownership, they intend to apply the mandatory offer to compulsory acquire the rest. The minority interest represents 26.7 per cent of the issued share capital of D&G, and implies a maximum total consideration of US$ 194 million. Further announcements regarding the mandatory offer will follow in due course,” stated Heineken in a release.
Desnoes and Geddes had a bid as high as $13 per share during trading today but the stock never traded and it ended with 2,744,725 units on the bid at $10.58. The stock last traded on Wednesday at $8 well below the offer price of almost J$31 for each share with the offer priced in US dollars.
Owners in Jamaica Stock Exchange will also be in on the fortunes of the deal as the exchange will end up collecting a nice payday when the local shares are transferred. Going forward the exchange will lose the annual listing fee and fees for trading the stock on the exchange.

HEINEKEN J$31 offer for D&G shares

Red Stripe tinHeineken N.V. (“HEINEKEN”) is to make an offer to acquire all of the minority shareholders shares in Desnoes & Geddes at US$0.259 per shares or the equivalent of J$31, the company stated in a release today. Udiam shall offer US$ 0.259 (the “Offer Price”) for each D&G Share. The Offer Price is the same price per D&G Share as Heineken International paid to Diageo in respect to the Acquisition.the offer represents a huge premium on the last traded price of the stock of $8 in trading today. The bid on the stock is now at $10.50.
Heineken N.V. (“HEINEKEN”) today has announced that Heineken International B.V. (“Heineken International”), a wholly-owned subsidiary of HEINEKEN, has acquired the entire issued share capital of Udiam Holdings AB (“Udiam”) from a subsidiary of Diageo plc (Diageo plc and its subsidiaries being “Diageo”) for the sum of US$420,992,826 (the “Acquisition”). Udiam owns 1,625,549,827 shares in D&G, which constitutes approximately 57.87% of the share capital of D&G. Heineken International has also acquired a small shareholding which Diageo Heinikenheld directly in D&G. The price paid by Heineken International to Diageo for Udiam, and the direct shareholding, equates to US$ 0.259 per D&G share. Prior to the Acquisition, another subsidiary of HEINEKEN already owned 434,033,141 D&G shares, which constitutes approximately 15.45% of the share capital of D&G. Following the Acquisition, HEINEKEN indirectly owns 2,059,610,670 shares, which constitutes approximately 73.32% of the share capital of D&G.
As a consequence of the Acquisition, and pursuant to Regulation 12(1) of the Jamaican Takeover Code, Udiam intends to make an offer (the “Offer”) to the shareholders of D&G for the acquisition of any and all of the shares which HEINEKEN does not, directly or indirectly, currently own (the “D&G Shares”). The Offer will be made through a formal tender offer pursuant to the Jamaican Takeover Code and applicable requirements.

Kremi’s big surge forward

Kremi Gapnt Sharp reduction in cost of sales and a 7 percent increase in revenues that ended at $271 million swelled profit in the August quarter for Caribbean Cream by more than 4,000 percent to $45.5 million and for the six months by 375 percent to $84.7 million from an 11 percent increase in sales to $560 million.
Cost of sales dropped 18 percent from $195.4 million to $161 million for the August quarter due mainly to a fall in the price or raw material input and from $378 million incurred for the half year in 2014, cost dropped to $339.4 million, lifting gross profit by 88 percent for the quarter to $110 million and by 73 percent for the six months versus that of 2014, to $221 million.
Administrative expenses climbed 37.8 percent to $102 million due mainly to implementation of sanitation measures that had to be implemented while selling and distribution expenses grew from $23.5 million to $25 million for the six months period, compared to that of 2014 and for the quarter, administrative expenses climbed by a more sedate 13.6 percent to $46 million while selling and distribution expenses grew from $12 million to $14 million.
Earnings per share amounted to 22 cents for the half year and 12 cents for the quarter. IC Insider is now forecasting earnings of 65 cents per share for the full year ending February 2016, due to the lower increase in sales in the August quarter than the 15 percent increase in the first quarter. The stock ended at a record close of $2.55 on Tuesday and has gained 240 percent for the year to date. IC Insider expects it to make further gains, as it is priced well below other stocks on the junior market that are selling above 7.6 times this year’s earnings with an average of 8.4.
A lot of the gains in profit came from the decline in raw material input, helping to push gross profit margin from 27 percent to 43 percent. Going forward increased input cost can place pressure on margins unless investment measures plan by Caribbean Cream to lower cost and create a more efficient operation are able to improve revenues and cut cost to compensate for any potential raw material cost increase that may arise. Cost increase in the medium term seems unlikely with downward pressure on input cost, the company has cash that it could be used to build up inventory at low prices if they sense the potential for prices to rise and thus mitigate against sharp price increases for the rest of the fiscal year.