Transjamaican in ICTOP10, CAB jumps 44%

The release of company results and some sharp price movements shook up the ICTOP10 listing this week, resulting in several changes in the top 10. Caribbean Assurance Brokers (CAB) topped the week, reporting record first quarter profit cheered by investors who pushed the price up by 44 percent to $2.88 and cleared the market of just about all supplies under $3. The stock sits in the number 7 spot, with potential for gains of 250 percent over the next twelve months.
CAB has been at the top of the TOP10 for several weeks going back to mid-March and now sits at the number 6 spot in spite of the substantial price gains, with ICInsider.com raising EPS to 50 cents from 45 cents. Taking over the number one spot is baker Consolidated Bakeries with Image Plus, that is in demand at number 2.
At the same time, ICInsider.com’s projection for Transjamaican Highway puts the stock into the Main Market TOP10 with projected earnings of 31 cents and a targeted price in the $6 region by early 2024 and replaces NCB Financial that got an earnings downgrade following the release of half year results showing earnings falling behind that for 2022, with a sharp fall in foreign exchange trading gains and increase loan loss provision.
Transjamaican headed the Market Watch list on April 29 this year. Then the price was at $1.77, with ICInsider.com indicating projected earnings of 24 cents per share and a short term price target of $2.40 and now the stock price is $1.85. The company released first quarter results on Friday, with profit of US$6 million.
Caribbean Assurance Brokers selling at a PE of just 7 based on historical earnings.

ICInsider.com has since adjusted earnings to 0.02 US cents per share or 31 Jamaican cents.
While the ICTOP10 Junior Market stocks had solid gains at the end of the week, the Main Market suffered several losses, with seven stocks declining.
Iron Rock Insurance jumped 22 percent to $2.29, Jamaican Teas rebounded from the previous week’s low by climbing 11 percent to $2.19 and dropped out of the TOP10 along with Everything Fresh having posted robust gains in revenues and profit for the March quarter, with investors welcoming the positive development by driving the stock up 14 percent to $1.89, with more to come. The company reported a profit of $35 million compared to just $7 million for the 2022 March quarter. IC Insider.com has since revised EPS for 2023, down to 25 cents from 30 cents previously, the combination of both of the above moves resulted in the stock moving out of the TOP10, but it still has more room for gains ahead. Lasco Distributors, one of the most undervalued stocks on the market, rose 4 percent to $2.68 but is trading at less than 6.4 times 2023 earnings of 42 cents per share and much lower based on earnings of 70 cents for fiscal 2024 has already started. After the March 2023 results are out, the EPS will switch over to the figure for 2024 and that would result in the stock holding the number 1 spot with likely gains above 400 percent. Image Plus rallied 4 percent to $2.20 and holds the number 3 spot on the TOP10.
Tropical Battery is the third stock to move out of the TOP10 with an earnings downgrade to 20 cents per share, following the release of half year results, showing a profit of $50 million, up from $30 million in the March quarter and from $87 million to $94 million for the half year. Dolla Financial, Edufocal and Dolphin Cove are this week’s new entrants to the Junior Market IC TOP10. Dolphin sits at the number 2 spot, with projected earnings of $3, following the 2022 full year results of 0.76 US cents or J$1.17 and will benefit from a sharp rebound in cruise ship arrivals, with the first 10 months last year being a fraction of what it was 2019 and the first quarter of 2020. This is in addition to increased stopover arrivals that will be greater than last year for a large part of the year.
The price of Main Market listed Key Insurance rose 8 percent to $3.40 to be the only stock of notable gains while Caribbean Producers dropped 8 percent in closing at $9.71, following release of nine months’ results that suggest that full year earnings from ongoing operations should end up around J$1.30 per share. Jamaica Broilers slipped 5 percent to $33.95 and Berger Paints fell 4 percent to $8.
Stocks are being prepped to rally, with signals that interest rates will be declining across the board sooner. Interest rates fell below eight percent on BOJ CDs and Treasury bills this past week, paving the way for a cut in the Bank of Jamaica overnight rate. That will provide more invigoration for the Jamaica stock market, with the Junior Market posting gains for a third consecutive week, even as the Main Market suffered another week of a mild decline.
The Junior Market’s long history of rising around a month before the release of quarterly results and declining shortly after results are released seems to be starting with a rise of 108 points in the market index in the previous week with more this past week, with the supply of some stocks continuing to fall sharply.
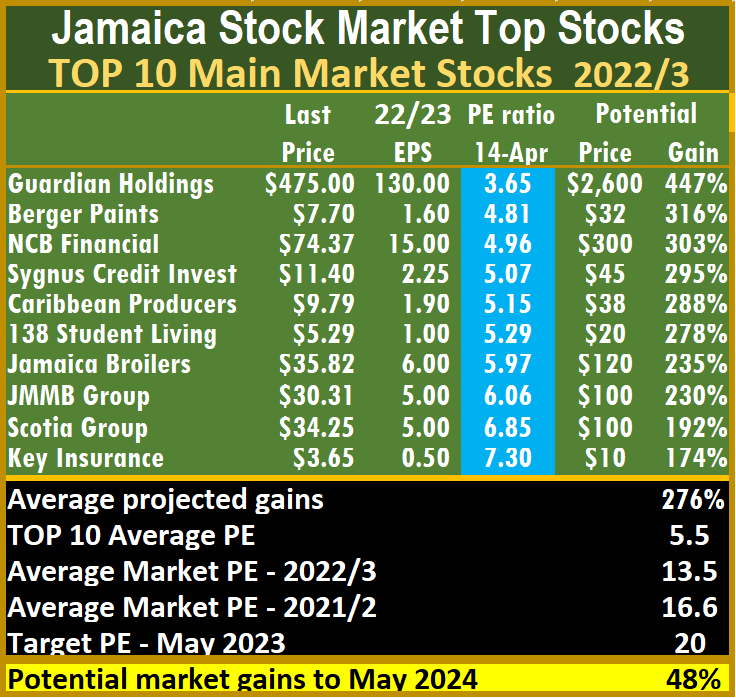
At the end of the week, the average PE for the JSE Main Market TOP 10 is 5.8, well below the market average of 13.5. The Main Market TOP10 is projected to have an average of 259 percent, by May 2024, based on 2023 forecasted earnings.
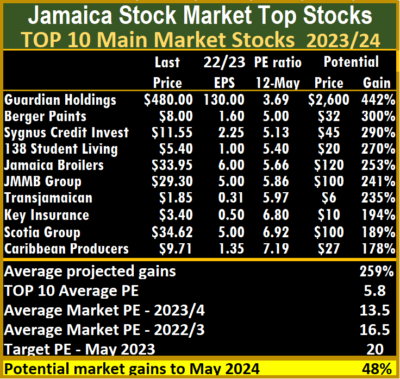
The 15 highest valued Main Market stocks are priced at a PE of 15 to 110, with an average of 27 and 19 excluding the highest PE stocks and 19 for the top half excluding the stocks with the highest valuation.
The Junior Market Top 10 PE sits at 5.8 compared with the market at 10.8. There are nine stocks, or 19 percent of the market, with PEs from 15 to 26, averaging 19 are well above the market’s average. The top half of the market has an average PE of 15, suggesting that this may currently be the lowest fair value for Junior Market stocks. Junior Market is projected to rise by 248 percent to May 2024.
The differences between the average PE ratio of the Main and Junior Markets and the overall market valuation are important indicators of the likely gains for ICTOP10 stocks.
ICTOP10 focuses on likely yearly winners, accordingly, the list includes some of the best companies in the market, but not always. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
IC TOP10 stocks are likely to deliver the best returns up to the end of May 2023 and are ranked in order of potential gains, computed using projected earnings for the current fiscal year. Expected values will change as stock prices fluctuate, resulting in weekly movements in and out of the lists. Revisions to earnings are ongoing, based on receipt of new information.

Persons who compiled this report may have an interest in securities commented on in this report.


Wisynco profit surge

Wisynco Group reported another solid quarter of profit to March 2023, from a 23.4 percent growth in revenues to $12 billion for the quarter over the $9.7 billion achieved in the 2022 third quarter and contributed to a 26.8 percent rise in nine months revenues to $36 billion up from $28.4 billion in 2022 with profit after tax of $3.66 billion 23.77 percent higher than $2.96 billion in 2022.

Wisynco headquarters

The group achieved a Gross Profit of $4.1 billion in the current quarter, the same as the preceding quarter and represents a 32.2 percent increase over the $3.1 billion of the prior year and was helped by an improvement in Gross Profit Margin of 34.6 percent which, up from 32.3 percent for the same quarter last year.
Profit before Taxation for the quarter was $1.57 billion, an increase of 43 percent over the $1.1 billion in the comparative quarter in 2022.
After the provision of $416 million for corporate taxes, Net Profits Attributable to Stockholders amounted to $1.2 billion, or 31 cents per stock unit for the quarter, 38.6 percent greater than the $831 million or 22 cents per stock unit earned for the prior year and 98 cents for the nine months up from 79 cents in 2022.
The company ended the period with cash and investments of $11.4 billion, placing it in a great position to fund the planned major factory expansion into 2024.

More expansion coming for Dolla Financial

Dolla Financial reported record profit for the 2023 first quarter that jumped 90 percent to $125 million before tax, from just $66 million last year, with aftertax profit coming in at $123 million, 128 percent higher than the $59 million reported for 2022, but the company is not satisfied, with that and plans increased borrowing to on lend and acquisition while having eyes on branch expansion.
The company borrowed $1.17 million in 2022 but used most of the available funds on hand at the start of the year, with loans granted to borrowers absorbing $550 million in the March quarter, leaving the company with just $117 million in cash funds. In order to maintain the current profit momentum the company will need to add new loans from lenders to keep funding the expansion.
In an investor briefing, the CEO Kadeem Mairs indicated that they are in the process of negotiating a US$7 million loan that will be used to fund loan expansion and acquisition that they are currently looking at. Such acquisitions will be subject to regulatory approval before they will be able to complete such transactions.
The company is also seeking to establish an 800 square foot branch in May Pen in the complex that houses the supermarket operated by Derrimon Trading.
Importantly, Mairs pointed out that 80 percent of loans granted are secured and therefore result in a low credit default.
IC Insider.com forecast is for the 2023 earnings per share to be 40 cents and is partially predicated on timely loan funding.

ICTOP10 Image Plus price jump 9%

With interest rates softening, some life has entered the Jamaica stock market, with the Junior Market posting gains for a second consecutive week, but the Main Market suffered a mild retreat following notable increases in the last week of April as several ICTOP10 stocks posted solid gains, including Image Plus that posted impressive full year results at the end of the previous week.

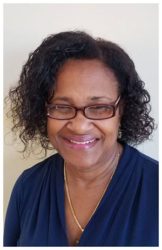
Dr. Karlene McDonnough – Chairman of Image Consultants Ltd.

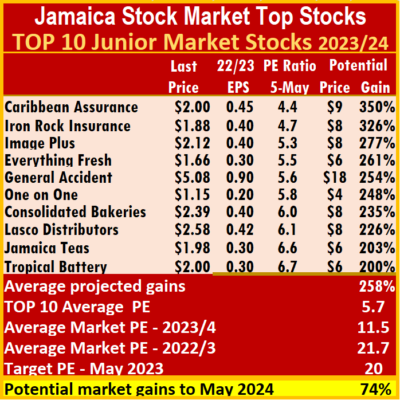
The week ended with several sizable winners in the ICTOP10 and one big loser. Lasco Distributors rose 13 percent to lead the winning stocks, followed by Everything Fresh with a strong 11 percent climb to $1.66, Consolidated Bakeries rose 10 percent to $2.39, Image Plus rallied 9 percent and iCreate rose by 5 percent to $1.47 and fell out of the ICTOP10 and is replaced by Jamaican Teas. Iron Rock Insurance fell 18 percent to close at $1.88 and General Accident slipped 6 percent to $5.08, being the only two losers of significance.
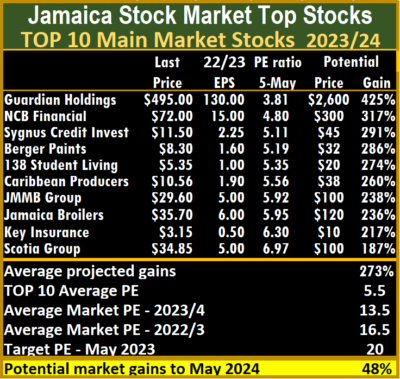
The price of Main Market listed Berger Paints rose 10 percent to $8.30, Caribbean Producers gained 8 percent in closing at $10.56, with the stocks seemingly poised to get back to the $12 region sooner than later as the supply of stocks being sold below $13 has virtually dried up. 138 Student Living popped 6 percent to $5.35, JMMB Group fell 6 percent to $29.60, and Jamaica Broilers slipped 4 percent to $35.70.
Stocks are being prepped to rally, with signals that interest rates will be declining across the board sooner. This stems from the continued slide of BOJ CDs rates since March, which saw the rate falling by 25 percent to 8 percent this past week. Lower interest rates are around the corner, which will be positive for stocks and the signs are already showing.
At the previous week’s close, Image Plus released solid full year results showing profit after tax that jumped 125.6 percent to $213 million or 21 cents per share. Based on those numbers, ICInsider.com revised earnings for the current fiscal year to 35 cents from 30 cents previously. On Monday, the company reported revised results, with the profit being even higher at $252 million, with a reduction in the amount previously booked as professional fees. Based on the revision, projected earnings were raised by the publication to 40 cents per share for the current fiscal year. The stock sits at the number three spot in the ICTOP10. The revision raises some serious questions about how such matters escaped the directors, auditors and the financial controller before the audited financial statements were released.
Dolla Financial fell out of the TOP10 at the end of the previous week and this past week released impressive first quarter results that excited investors who responded well to them by driving the price to close the week at $2.89, with the price hitting a high of $2.99 on Friday. The company seems poised to deliver ICInsider.com forecasted earnings of 40 cents, provided they obtain loans on a timely basis to on lend.
The Junior Market’s long history of rising around a month before the release of quarterly results and declining shortly after results are released seems to be starting with a rise of 108 points in the market index in the previous week with more this past week, with the supply of some stocks continuing to fall sharply.
At the end of the week, the average PE for the JSE Main Market TOP 10 is 5.5, well below the market average of 13.5. The Main Market TOP10 is projected to have an average of 273 percent, to May 2024, based on 2023 forecasted earnings.
The 16 highest valued Main Market stocks are priced at a PE of 15 to 110, with an average of 28 and 19 excluding the highest PE stocks and 20 for the top half excluding the stocks with the highest valuation.
The Junior Market Top 10 PE sits at 5.7 compared with the market at 11.5. There are 12 stocks, or 25 percent of the market, with PEs from 15 to 26, averaging 20, well above the market’s average. The top half of the market has an average PE of 16, suggesting that this may currently be the lowest fair value for Junior Market stocks. Junior Market is projected to rise by 258 percent to May 2024.
The differences between the average PE ratio of the Main and Junior Markets and the overall market valuation are important indicators of the likely gains for ICTOP10 stocks.
ICTOP10 focuses on likely yearly winners, accordingly, the list includes some of the best companies in the market, but not always. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
IC TOP10 stocks will likely deliver the best returns up to the end of May 2023 and are ranked in order of potential gains, computed using projected earnings for the current fiscal year. Expected values will change as stock prices fluctuate, resulting in weekly movements in and out of the lists. Revisions to earnings are ongoing, based on receipt of new information.

Persons who compiled this report may have an interest in securities commented on in this report.
Profit surges at Dolla

Profit at Dolla Financial for the 2023 first quarter jumped 90 percent to $125 million before tax of $1.9 million from just $66 million last year, with aftertax profit coming in at $123 million, 128 percent higher than the $59 million in 2022, the robust outcome flowed from total income of $310 million up 110 percent over $141 million in 2022.
The revenue grew from a 161 percent increase in loans to customers of $2.3 billion from $870 million at the end of March 2022. The company lent out nearly $550 million in the March 2023 quarter.
Administrative expenses jumped by 110 percent to $124 million from $59 million in 2022, while Interest expense surged 285 percent to $50 million from just $13 million in 2022 following increased loan funding of $1.6 billion by 232 percent from $481 million at the end of March last year.
Profit for 2023 equates to 6 cents in earnings per share. ICInsider.com is forecasting 40 cents per share for the year, partially on the assumption that there will be an increase in loan funding to facilitate increased lending to customers and maintain the rapid loan expansion. This is likely to push the stock into the $8 region. However, the PE ratio is 7 times current year’s earnings, with the stock price at $2.79 that it traded at on the Junior Market on Wednesday. With no additional loan funding, profits should end the year at 35 cents per share or just under $900 million.
Profit for the quarter pushed shareholders’ equity to $794 million.

Revenues & profit explode at Image Plus

Revenue and profits surged solidly for the most recently Junior Market listed Image Plus Consultants for the financial year ended February 2023, with revenue jumping a robust 40.7 percent to a record $1.094 billion, up from $777 million in 2022 but, with a slower pace of 33 percent in the final quarter of $290 million compared with $218 million in 2022 as the company that specializes in diagnostic services delivered a convincing 123 percent growth in Profit before Tax to $252 million, up from $113 million in 2022.
Profit after tax jumped 139 percent to $236 million over the $94 million generated in 2022. Results equated to earnings per share of 23 cents up from 9 cents in 2022. ICInsider.com revised earnings for the current fiscal year to 40 cents from 30 cents previously and 85 cents for the fiscal year ending February 2025.
Revenue was driven by the growth in case count of 54,840, an increase of 8,469 cases or 18.3 percent over the 2022 financial year, the company advised shareholders in a release accompanying the financials.
Gross profit jumped 39 percent to $716 million from $505 million in the previous year as the company maintained a 39 percent cost of sales for a second year.
Administrative expenses rose 14 percent to $417 million from $365 in 2022, depreciation charge climbed to $43 million versus $36 million in 2022 and finance costs remained almost flat at $7 million.
Current liabilities stood at $138 million, Shareholders’ equity grew from $267 million to $945 million, helped by an infusion of $465 million in proceeds from the IPO earlier in 2023 coupled with the growth of $213 million in the year’s profit.  Long term liabilities amount to $75 million, with current loans amounting to $39 million. Cash and investment funds totalled $492 million and helped to swell Current assets to $811 million from just $223 million at the end of the fiscal year 2022.

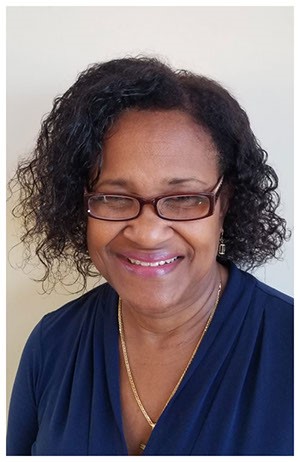
Dr. Karlene McDonnough – Chairman of Image Consultants Ltd.

Cash flow generated $271 million, but working capital absorbed $83 million as receivables Increased by $159 million due partially to greater business activity. Addition to fixed assets consumed $152 million, with Lab equipment taking $104 million and leasehold improvement $43 million.
According to management, “a new fluoroscopy unit was acquired for our Winchester location and the relocation of our Ocho Rios operations to a larger space in White River North Commercial Complex in Q3 drove growth in leasehold improvements. The significant increase in patient scan volumes resulted in a growth of $159 million in trade receivables. Management continues to actively manage these receivables and written commitments have been received from the largest payer, which gives us confidence that these receivables will continue to be honoured.”
The company incurred income tax on profit for ten months of the financial year 2023 before listing and will enjoy five years tax free status as JSE Junior Market listed company.
The stock, around $2, is attractive and can potentially deliver good returns for investors at the current price. Investors could benefit from cash dividends as the directors will meet this month to consider a dividend payment.

iCreate in ICTOP10 Image Plus EPS jumps

The markets are changing, with the Main Market up for three consecutive weeks but the Junior Market meandering for the last four weeks. Against this backdrop, there was one change to the TOP10, with iCreate coming in and Dolla Financial falling out, but Dolla and Honey Bun, that slipped out the previous week, sit immediately below the TOP10.
There were no significant winners for the past week in both markets’ TOP10 as losers dominated. The Junior market had Consolidated Bakeries falling 11 percent to $2.17 and general Accident down 10 percent to $5.40 and Lasco Distributors down 3 percent, with the stock selling at just 5.5 times 2023 estimated earnings and only 8.5 times the company’s nine month results. By any stretch, the stock is considerably undervalued and there are more profits to come in the current fiscal year.
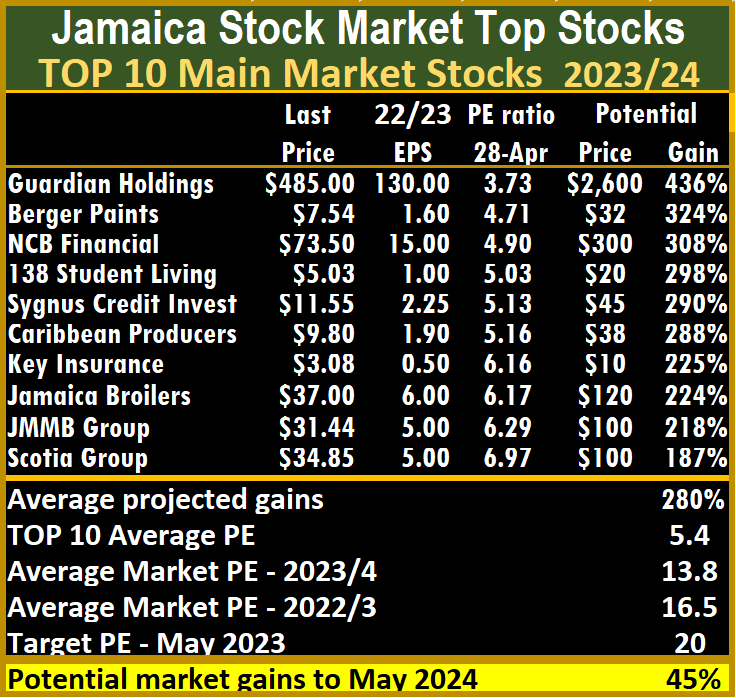
Main Market stocks had a 13 percent fall in Key Insurance after the price closed at $3.08, Berger Paints contracted by 9 percent to $7.54 and 138 Student Living slipped 5 percent to $5.03, while Jamaica Broilers rose just 3 percent to $37.
Stocks are being prepped to rally, with early signals that interest rates will be declining across the board sooner than later. This stems from the continued slide of rates on BOJ CDs since March, that saw the rate falling by 23 percent to 8.11 percent against a background where inflation since November last year is running at less than one percent per annum.
At the week’s close, Image Plus released full year results showing profit after tax jumping 125.6 percent to $213 million or 21 cents per share. ICInsider.com revised earnings for the current fiscal year to 35 cents from 30 cents previously.
The Junior Market’s long history of rising around a month before the release of quarterly results and declining shortly after results are released seems to be starting with a rise of 108 points in the market index this past week, with the supply of some stocks falling sharply.
At the end of the week, the average PE for the JSE Main Market TOP 10 is 5.4, well below the market average of 13.8, while the Junior Market Top 10 PE sits at 5.9 compared with the market at 11.6. The differences are important indicators of the level of likely gains for ICTOP10 stocks. The Junior Market is projected to rise by 257 percent and the Main Market TOP10 by an average of 280 percent to May 2024, based on 2023 forecasted earnings.
The Junior Market has 11 stocks representing 23 percent of the market, with PEs from 15to 27, averaging 21, well above the market’s average. The top half of the market has an average PE of 17, suggesting that this may currently be the lowest fair value for Junior Market stocks.
The 18 highest valued Main Market stocks are priced at a PE of 15 to 115, with an average of 29 and 20 excluding the highest PE stocks and 20 for the top half excluding the stocks with the highest valuation.
ICTOP10 focuses on likely yearly winners, accordingly, the list includes some of the best companies in the market, but not always. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
IC TOP10 stocks are likely to deliver the best returns up to the end of May 2023 and are ranked in order of potential gains, computed using projected earnings for the current fiscal year. Expected values will change as stock prices fluctuate, resulting in weekly movements in and out of the lists. Revisions to earnings are ongoing, based on receipt of new information.

Persons who compiled this report may have an interest in securities commented on in this report.

Honey Bun rises 8% to exit ICTOP10

The Junior Market of the Jamaica Stock Exchange recorded solid gains during the past week as the Main Market declined, resulting in three solid gains for the ICTOP10 Junior Market stocks and just one notable move in the performance of the ICTOP10 Main Market as General Accident added 18 percent to its value to be the best performing stock for the week.

General Accident selling supply of stocks is down sharply.

The Junior Market had one change in the TOP10 as Honey Bun moved out for a second time in weeks with a rise of 8 percent, allowing Dolla Financial to come in at number 10. Dolla is likely to enjoy a doubling in profit for the current year, having expanded the loan portfolio dramatically since taking on the billion dollar loan. Investors in the stock can look forward to healthy gains in the stock price during the year.
Main Event, one of the previous week’s top performers that exited the Top 10 with a 6 percent gain to close at $12.95, keeps on rolling on and climbed another 13.5 percent this week to $14.70, up 63.5 percent for the year to date as investors continue to applaud the company’s performance by buying up the stocks as they see more profits to come this year, with the economy fully opened up for entertainment.
The other major price movements during the week were a 9 percent rise for Lasco Distributors, that ended at $2.36 and Honey Bun, up 8 percent to $6.57. There are only two stocks with losses of two percent or less.
In the Main Market, only three stocks recorded declines, but Berger Paints was the only stock with a meaningful move, gaining 8 percent to $8.30.
Interest rates on Bank of Jamaica CDs dipped again at this past week’s auction that, which saw the average rate slipping to 8.21 percent from 8.41 percent at the previous week’s auction. Over the past five months, inflation has been running at less than one percent per annum, which has set the stage for BOJ to act quickly to slash interest rates, a positive development for the market.
The Junior Market’s long history of rising around a month before the release of quarterly results and declining shortly after results are released seems to be starting with a rise of 108 points in the market index this past week, with the supply of some stocks falling sharply.
Honey Bun’s fall from the TOP10 Junior Market list is not the end of the road for this outstanding performer with increased investors’ interest with an expected jump in revenues and profits for the first quarter with the Easter coming at the beginning of April versus the 17th of April last year as well as improvement of gross profit margin that slipped previous year. ICInsider.com expects the price to increase by up to 200 percent this year.
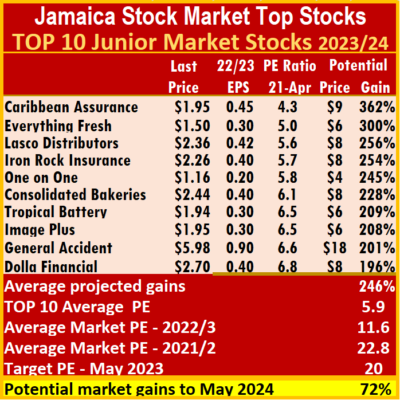
At the end of the week, the average PE for the JSE Main Market TOP 10 is 5.5, well below the market average of 13.7, while the Junior Market Top 10 PE sits at 5.9 compared with the market at 11.6. The differences are important indicators of the level of likely gains for ICTOP10 stocks. The Junior Market is projected to rise by 246 percent and the Main Market TOP10 by an average of 273 percent, by May 2024, based on 2023 forecasted earnings.
The Junior Market has 13 stocks representing 27 percent of the market, with PEs from 15 to 27, averaging 19, well above the market’s average. The top half of the market has an average PE of 16, suggesting this may be the current lowest fair value for Junior Market stocks.
The 16 highest valued Main Market stocks are priced at a PE of 15 to 114, with an average of 31 and 21 excluding the highest PE stocks and 20 for the top half excluding the stocks with the highest valuation.
ICTOP10 focuses on likely yearly winners, accordingly, the list includes some of the best companies in the market, but not always. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
IC TOP10 stocks will likely deliver the best returns up to the end of May 2023 and are ranked in order of potential gains, computed using projected earnings for the current fiscal year. Expected values will change as stock prices fluctuate, resulting in weekly movements in and out of the lists. Revisions to earnings are ongoing, based on receipt of new information.

Persons who compiled this report may have an interest in securities commented on in this report.

Honey Bun in ICTOP10 as Purity jumps 24%

The Main Market of the Jamaica Stock Exchange recorded solid gains during the past week as the Junior Market declined but that did not show up in the ICTOP10 stocks performance as Junior Market stocks ended with gains and losses with the average gains outdoing declines while the Main Market ended with modest price changes in a week when Consolidated Bakeries (Purity) was the star performer with a 24 percent rise to $2.50.

Consolidated Bakeries

The Junior Market had one change in the TOP10 as Main Event rose 6 percent to $12.95 and moved out of the TOP10, allowing Honey Bun to return after falling out the previous week.
Other major price movements in this past week were a 4 percent rise for Everything Fresh to $1.46, a 17 percent fall to $2.15 for Lasco Distributors and 4 percent decline for Image Plus to $1.95. Trading in Image Plus never resulted in more gains during the week following the previous week’s healthy move as selling continued at the same pace as the week before while buyers seem to have pulled back.
In the Main Market, Key Insurance rose 5 percent to $3.65, while Sygnus Credit Investments fell 5 percent to $11.40 as Guardian Holdings, Berger Paints and JMMB Group declined by 4 percent to $475, $7.70 and $30.31 respectively.
Interest rates on Bank of Jamaica CDs dipped again at this past week’s auction with the average rate slipping to 8.41 percent from 8.49 percent, at the previous week’s auction, with BOJ quarantining $104 billion. At the same time the foreign exchange market enjoyed buoyant flows with more funds entering the market each day than the amount dealers sold.
Another fact worth noting is that the Junior Market has a long history, with the market starting to rise around a month before the release of quarterly results and declining shortly after results are released.
Honey Bun’s return to the TOP10 Junior Market list this past week should enjoy increased investors’ interest with an expected jump in revenues and profits for the first quarter with the Easter coming at the beginning of April versus the 17th of April last year as well as improvement of gross profit margin that slipped last year.
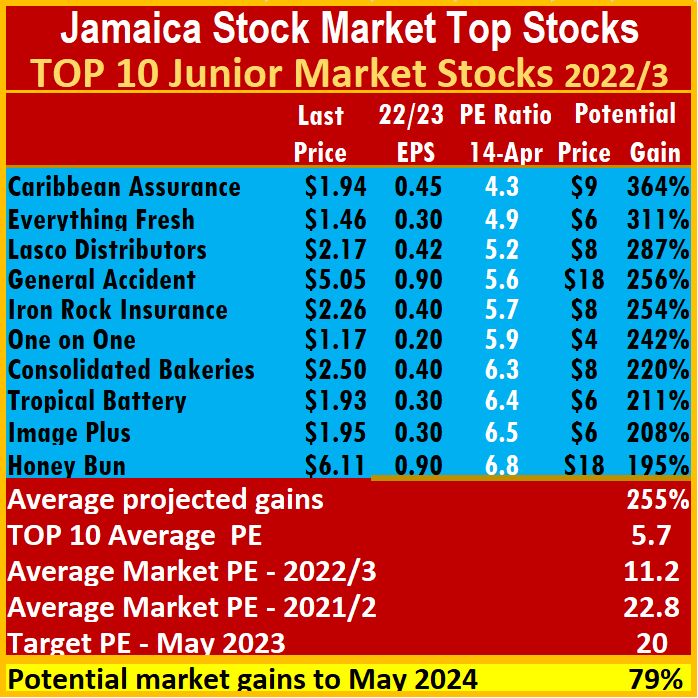
At the end of the week, the average PE for the JSE Main Market TOP 10 is 5.5 well below the market average of 13.5, while the Junior Market Top 10 PE sits at 5.7 compared with the market at 11.2. The differences are important indicators of the level of likely gains for ICTOP10 stocks. The Junior Market is projected to rise by 255 percent and the Main Market TOP10 an average of 276 percent, to May 2024, based on 2023 forecasted earnings.
The Junior Market has 11 stocks representing 23 percent of the market, with PEs from 15 to 28, averaging 20, well above the average of the market. The top half of the market has an average PE of 16, suggesting that this may be a logical value for junior market stocks currently.
The 16  Main Market stocks with the highest value are priced at a PE of 15 to 115, with an average of 31 and 20 excluding the highest PE stocks and 20 for the top half excluding the stocks with the highest valuation.
The above average shows the extent of potential gains for the TOP 10 stocks.
ICTOP10 focuses on likely yearly winners, accordingly, the list includes some of the best companies in the market but not always. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
IC TOP10 stocks are likely to deliver the best returns up to the end of May 2023 and are ranked in order of potential gains, computed using projected earnings for the current fiscal year. Expected values will change as stock prices fluctuate and result in weekly movements in and out of the lists. Revisions to earnings are ongoing, based on receipt of new information.

Persons who compiled this report may have an interest in securities commented on in this report.

Solid profit from concrete growth

Profit at Jamaica’s sole cement producer, Caribbean Cement Company was flat in the December quarter last year, with $1.48 billion earned compared with $1.5 billion in 2021, profit for the full year to December rose a solid 24 percent to a record $5.4 billion from $4.34 million in 2021.
The improved full year results flowed from an 8.4 percent rise in sales revenue to $25.8 billion, from $23.84 in 2021. Revenues were almost flat for the December quarter at $6.15 billion against $6.04 billion in 2021.
There was a notable improvement in gross profit margin that increased to 44 percent from 41 percent in 2021 as cost of sales rose by a mere 3.3 percent to $14.5 billion from $14 billion in 2021 that includes depreciation of $1.4 billion, down from $1.45 billion in 2021 and fuel and electricity that surged 37 percent from $4.1 billion, to $5.6 billion in 2022. The net effect is that Gross profit rose 15.5 percent for the year, to $11.36 billion from $9.8 billion in 2021. The moderate rise in direct cost, “was mainly attributable to the company’s decision not to undertake its planned major maintenance during the third quarter, compared to 2021,” the company stated in the release containing the results.
Administrative expenses rose close to the rise in revenues by 14 percent to $942 million in the year from $827 million while Selling Distribution and logistics expenses rose just 4 percent to $1.74 billion from $1.67 in 2021. Included in the administrative expenses are Management fees of $200 million, up slightly from $195 million in 2021 and royalty fees of $475 million with none in 2021 and write off of $120 million for non-recoverable GCT costs with none in 2021. Personnel remuneration and benefits amounted to $2.64 billion during the year, up from $2.5 billion in 2021, but actual salaries and wages were modestly lower at $1.97 billion versus $1.98 billion in 2021.
Finance cost declined in the year to $581 million from $671 million in 2021, which include a charge of $402 million during the year and $376 million for 2021 for unwinding discount on the redemption of the preference shares. The company has fully liq uidated the debt and there should be no charge in 2023 for this item
Gross cash flow generated from operations amounted to $8.8 million and was reduced by increased working capital of $5 billion to $3.8 billion. The net cash flow provided funding for the acquisition of fixed assets costing $1.26 billion, the payment of $1.26 billion in dividends. They also paid off the balance of $1.84 billion due on preference shares to Trinidad Cement.
At the end of December, shareholders’ equity stood at $20 billion with long term borrowings at a mere $608 million.
Current assets ended the period at $7.1 billion, up from $4.3 billion in 2021 including trade and other receivables of $650 million, cash and bank balances of $575 million with $5.48 billion of inventories up from $3.44 billion in 2021. Current liabilities ended the period at $6.1 billion, down from $8.5 billion in 2021. Net current assets ended the period at $1.1 billion.
Earnings per share came in at $6.33 when compared to $5.10 in 2021. IC Insider.com forecasts $7.50 per share for the fiscal year, with a PE of 7.7 times current year’s earnings based on the price of $57.50 the stock traded at recently on the Jamaica Stock Exchange Main Market with a net asset value of $23.54 and 2.5 times book value.
The company paid a dividend of $1.53 cents for the first time in 17 years in September last year.
This cost incurred for the unwinding of the discount for the repayment of the preference shares will not recur in 2023 also the write off of non-recoverable GCT cost, countering these savings will be the annual major maintenance that was not incurred in 2022, at the same time Fuel and electricity cost should fall from the Ukraine war induced spike in worldwide oil prices that has since moderated form the peak of more than US$120 per barrel to around $80 currently.
The company outlook was summarized by management, “we will ensure that our operations remain resilient by employing sound cost management strategies in this challenging economic environment.
Additionally, we expect to have a similar or better level of productivity and efficiency of the kiln in the future on completion of our planned major maintenance in 2023. During the previous quarter, the groundbreaking of our major kiln expansion project took place. This important investment will improve the self-sufficiency of the industry in Jamaica to comfortably meet growing demand, while setting the foundation to supply other export markets, effectively strengthening the external sector of our economy and essentially the country’s growth.”
The above expansion plan projected to increase the plant capacity by up to 30 percent should be completed by the second half of 2024 and will lower the unit cost of producing cement if it leads to a sufficient increase in sales volume. That won’t take place until 2025.
The stock is selling at a discount to its normal value but seems to weight down by higher interest rates and a slowdown in activity in the construction sector, but all signs point to lower interest rates in the second half of the year and continuing for a while, as such these negative factors will soon pass. With the expansion to come on stream in 2024, the stock remains a good long term buy.