Capital spend is set to expand at Caribbean Producers (CPJ) following approval of the Board, the company stated in a recent release with plans for “three major projects that will positively impact the growth and further development of the Company both locally and offshore” the release from the company stated.
Caribbean Producers
The plans include a U$1 million solar expansion project, with installation to commence in the first quarter of the 2024 financial year that starts in July, US$2.3 million modernization of the Meat Processing Plant, with work to commence in the first quarter of 2024, both projects will reduce operating cost. CPJ will be expanding its Operation in St. Lucia with a new store, with Operations to begin in the second quarter of the financial year 2024.
The proposed capital spend comes on the heels of a profitable nine months for the company recovering from fallout in revenues and profit during the covid-19 pandemic. For the three months to March, revenues rose 28 percent to US$35.7 million versus US$28 million in 2022 and climbed 24 percent to US$107 million for the year to March, over US$86.4 million for the similar period in 2022.
The March quarter saw cost of sales rising slightly faster than revenues, with an increase of 30 percent to US$25.3 million from $19.5 million, with a gross profit margin of 29 percent, down from 31.2 percent in 2022. For the nine months, it also rose faster than sales with an increase of 28 percent to US$75.3 million from US$58.8 million and resulted in a gross profit margin of 29.7 percent, down from 31.5 percent in 2022, negatively impacting profits.
According to management, “We expect growth in revenue and margins going forward will translate to improved company performance.”
Caribbean Producers
Profit before tax declined sharply for the March quarter by 65 percent from US$$1.8 million to US$636,974 after accounting for a one-time charge of US$1.45 million in the third quarter relating to GCT assessment, dragging profit down to a mere US$226,000 after tax, attributable to the company’s shareholders of and down 49 percent to US$3.6 million for the nine months compared to US$6.8 million earned in 2022. For the nine months, profit before tax declined 34 percent to US$5.2 million in the current year, from US$7.9 million for the similar period in 2022, but it declined a smaller 16 percent, excluding the one-time charge for GCT. Selling and administrative expenses rose sharply by 24.7 percent in the March quarter from US$5.2 million in 2022 to $6.5 million in what management stated was due to increased staffing to position for further growth, the increase negated the improvement in the gross profit. For the nine months, the cost in this category increased 33.6 percent to US$19.6 million from US$14.7 million in 2022. That was the area of significant cost increase that depressed profits for 2023. But profit before tax would have increased to US$2.8 million when the charge for GCT is excluded compared with US$2.6 million in March 2022 quarter and US$9 million versus US$10 million.
At the end of March, shareholders’ equity stood at US$26.7 million, up from US$22.4 million at the end of March 2022 and US$23.2 million at the end of the June 2022 fiscal year. The company continues to be heavily leveraged with borrowings of US$40.5 million, of which US$9.8 million is short term and due to be repaid within twelve months.
 Current assets stood at US$62 million at the end of March versus US$62.5 million at the end of June 2022 and just US$25.3 million as of March 2022. Cash and equivalents were US$4.9 million, up from US$3.9 million at the end of the 2022 fiscal year, with receivables at $18 million, virtually flat with the fiscal year end. Still, inventories slipped to US$39 million from US$40 million at the end of the fiscal year but are up over March 2022 at $30 million.
Current liabilities stood at US$25.4 million at the end of March versus US$46.75 million at the end of June 2022 and US$25.3 million as of March 2022.
CPJ is the dominant company within the hospitality sector. The expected continued expansion in the hotel rooms should be fertile ground for continued growth in revenues and profitability over the next few years. The company is highly leveraged, which is a huge negative, especially when business declined, as it did during the height of the COVID epidemic, curtailing sales in 2021 and 2022.
The company reported 0.02 US cents in earnings per share for the March quarter compared to 0.14 cents in 2022 and 0.33 US cents for the half year to March 2023 versus 0.62 cents in the prior year. As indicated above, ongoing earnings per share are better than the numbers suggest. The US$1.5 million written off for general consumption tax assessment is not an ongoing expense. As such, it should be excluded from earnings in valuing the company’s shares to assess ongoing earnings capabilities better. In addition, the tourism trade did not return to normal capacity compared to 2019 until the start of 2023, as such, the first two quarters of this fiscal year are based on lower business levels than is the norm and the 2024 fiscal year should reflect a better outcome as a result.
IC insider.com forecast earnings of J$1.35 per share for the June 2023 fiscal year and J$2.50 in the next fiscal year, with the stock currently at $9.46 on the Main Market of the Jamaica Stock Exchange with a value of 7 times the current years’ earnings. Investors can expect a period of continuing growth in the share price over the next 12 months as a result of continued improvement in profitability and lower interest rates in the coming months.
 A 10 to 1 split would lift the issued shares to just over 2.5 billion units which would be within a level that would facilitate a great deal of liquidity for a number of years, but the price could be back in the teens again in 2024. Even a 5 for 1 would result in an enhanced level of liquidity with just over 1.25 billion units in issue and push it to 16th Junior Market company in terms of the number of issued shares and 6th if a 10 to 1 split was to be approved. The prospects of profit jumping sharply in 2024, if achievable and seen by management as likely then a 10 to 1 split would seem to be the better option.
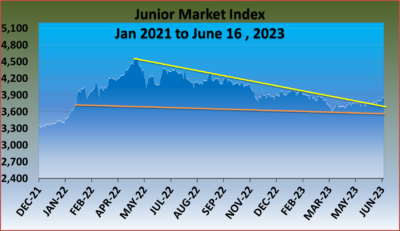 The Junior Market has broken through the downward-sloping resistance line of the wedge. The Junior Market reclaimed the 3,800 handle last week and is close to retaking the 3,900 level shortly, with the market set for a big rally in the second half of the year a position supported by technical analysis of the market. The Main Market seems to be weighed down by concerns relating to inflation and interest rates, if so the reading is wrong as inflation is well under control and interest rates will start dropping before the year ends.
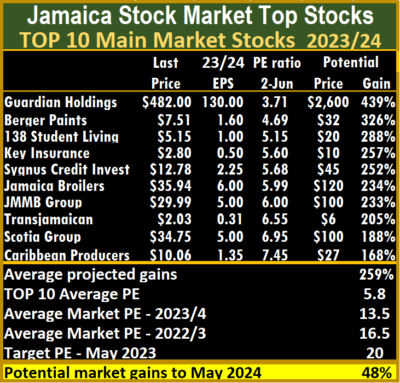
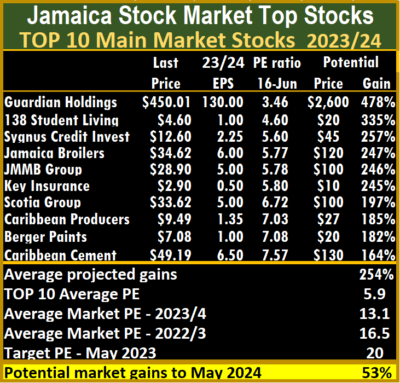 Transjamaican moved out of the Main Market TOP10, with a gain of 27 percent since entering the TOP10 and 35 percent since it was added to
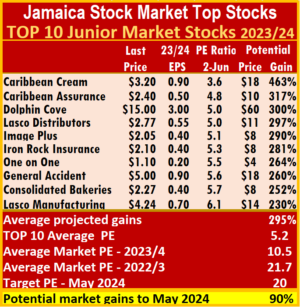
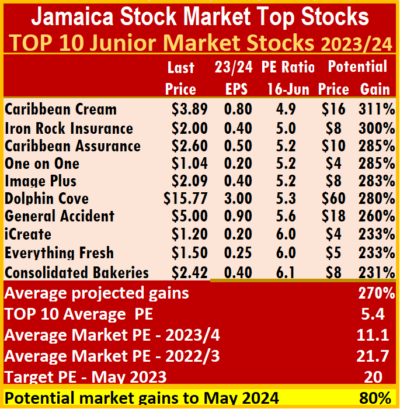 The Junior Market Top 10 PE sits at 5.8 compared with the market at 11.1. There are 11 stocks representing 23 percent of the market, with PE from 15 to 42, averaging 21 that are well above the average of the market. The top half of the market has an average PE of 16, possibly the lowest fair value for Junior Market stocks currently. Junior Market is projected to rise by 270 percent to May 2024.
 Operating Revenues rose 11 percent from $423 million to $469 million for the year ending December 2022, while Other Operating Income generated $37 million which was down 7 percent from $40 million in 2021, resulting in total income rising 7 percent to $506 million from $463 million in 2021. Profit for the year rose 32 percent to $75 million from $57 million in the prior year, with earnings per share of 30 cents up from 21 cents in 2021.

 Lasco Distributors climbed 19 percent following an 11 percent rise last week to close at $3.31 and is up 59 percent from the 2023 low of $2.08 in April. Five stocks rose 6 percent: Caribbean Assurance Brokers,
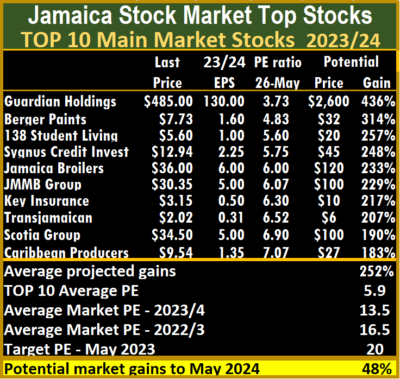
 The differences between the average PE ratio of the Main and Junior Markets and the overall market valuation are important indicators of the likely gains for ICTOP10 stocks.
 Sale revenues for the just completed year rose 20 percent to $2.5 billion from $2.1 billion in 2022. In the final quarter, revenues climbed 22.5 percent to $674 million from $553 million in 2022 and increased 17 percent over the $576 million in the November 2022 quarter. In contrast, revenues for the 2022 February quarter were 10 percent more than the $501 million generated in the November 2021 quarter. All in all, the 2023 fiscal year performance was well ahead of the year to February 2022, even as the year started with just $1.3 million in profit with cost of sales at 73.2 percent with the second quarter being slightly better with cost of sales down to 70.7 percent and profit improving to $7.2 million as both volume improvement and price adjustment to the output chipped in to help improve the bottom line.
 Cost of sales rose 16 percent, slower than sales in 2023, to $1.73 billion from $1.49 billion in 2022, with gross profit rising faster than revenues, a positive development with an increase of 31 percent to $593 million from $775 million in 2022. The cost of raw materials used in sales rose 16 percent to $1.17 billion, compared with a 33 percent rise in fiscal year 2022 over 2021. Milk solids, one of the primary raw materials, about 70 percent that is used in producing ice cream moved from an average of US$3,355 per ton in 2018 to US$5,067 in 2022 and is now $4,676 in 2023, down 9 percent. In 2022 the cost rose by 29 percent, these movements, coupled with exchange rate changes for the Jamaican dollar, would have pushed up the company’s production cost; also affecting cost would be a 7 percent movement in the exchange rate between the Jamaica dollar and the US dollar. If continued, falling commodity prices in 2023 will lower the cost for them and help improve profits. Also of note is that the price of crude oil is now 38 percent less than it was in 2023 at the start of June and that feeds directly into utility cost incurred in production, which was $166 million, 16 percent higher than 2022 and 19 percent more in Administration with $99 million versus $83 million in 2022.
 Gross cash flow generated $195 million from operating activities, up from just $53 million in 2022. Funds internally generated were augmented by loan inflows of $353 million and funds at the start of the year amounting to $145 million, which helped to fund additions to fixed assets of $541 million.
 The price of Main Market listed
 Massey Holdings, Seprod,
 Elsewhere the only other news of note was the passing of the Chairman and majority owner of the Lasco companies, the addition of two new directors at ISP Finance and the Bank of Jamaica issue of $35 billion in 28 days CDS with investors offering to buy just $35.24 billion, BOJ took up less than the amount offered with $34.45 billion being sterilized the amount offered and moved the total amount of CDs outstanding to a record $111.45 billion up from $109 billion the week before. The average interest rate climbed back above 8 to 8.24 percent.
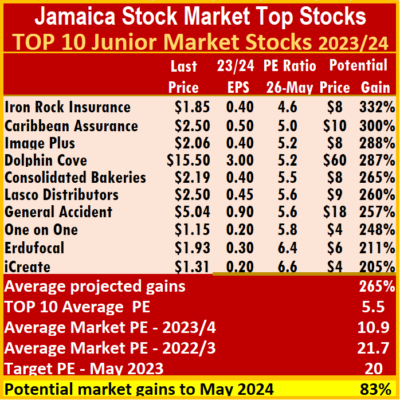 Action in the markets this past week resulted in four ICTOP10 Junior Market stocks recording significant losses of 6 to 26 percent, with only 2 with 4 percent gains. Everything Fresh dropped out of the TOP10 and iCreate returns after a brief absence. Main Market stocks were mixed, with one noted loss and two gains of note.
 Market is projected to rise by 265 percent to May 2024.
 Earning season delivered solid profit gains for several companies, but that did little to move prices substantially upwards, even as interest rates are softening. A few exceptions are CAB, Dolphin Cove, Consolidated Bakeries, Everything Fresh and earlier Image Plus and Tansjamaican Highway, which enjoyed increased buying interest that sent higher prices. Things have since cooled, as is the norm after most results were released in May, as investors await the critical second quarter number in late July into August before pulling the trigger.
 The price of Main Market listed Sygnus Credit Investments gained 13 percent to finish at $13.04 and was followed by Key Insurance, up 7 percent to $3.65 and 138 Student Living with an increase of 5 percent to $5.67, while Caribbean Producers dropped 7 percent in closing at $9.05.
 The Junior Market Top 10 PE sits at 5.8 compared with the market at 10.8 there are ten stocks or 21 percent of the market, with PEs from 15 to 24, averaging 19, well above the average of the market. The top half of the market has an average PE of 15, possibly the lowest fair value for Junior Market stocks currently. Junior Market is projected to rise by 250 percent to May 2024.