The JSE stock traded at an outlandish $13.50 & dropped 47% since.
It is not nice to watch one’s investment lose value while others grow delivering big gains at the same time. Many investors plunge into investments that will result in just that happening, as they err and refuse to let go and reinvest, to recover their loss, from gains elsewhere.
A look back at prices in 2005, reveals shocking results of costly ill-timed investments. In June 2005, investors in a bout of excess exuberance, pushed Mayberry Investments to $8.40 from a listed price of $5.05, weeks after it listed on the Jamaica Stock Exchange, 12 years later it is still to reach back to that level. That is a huge blow to investors who held on to the shares from then.
The sad thing is that many investors who wanted to sell could not, as attempts were made to control the price from a big drop as selling started to overwhelm buying a few days after nearly 40 million shares were traded around the $7-8 level. Mayberry is an outstanding example of investors making huge errors based on inadequate information and paying dearly for it.
But Mayberry’s stock is not the only one that investors underwent a long period of suffering from, they have a number of top notch companies as their friends that that performed poorly until fairly recently. Scotia Group was pushed to $33.50 in March 2005 based on results that were not sustainable as the bank benefited by a poor decision of the Central Bank to push interest rates on CDS paying interest at elevated levels for about two to three years. The banks of course made a killing when rates fell back. Added to that, Scotia effected a stock split that sent the stock flying. Well it was not until late 2016 that the price exceeded the 2005 high. JMMB Group’s shareholders saw the price of the stock peaking at $22 in April 2004 only to see it fall away and not getting back to that level until recently this year. That is not great for a stock that is not a great dividend payer.
Grace Kennedy hit a high of $123 (Now $41 after stock split in 2016), in January 2005, it has taken nearly 12 years to recover the loss and it has still not delivered much more in gains since its full recovery.
Markets tend to repeat past behaviors, over and over but sometimes they take a break from the norm. PE ratios are the end product of investors’ perception of values for stocks. There are other measures but the PE is the most widely used. When PEs are pushed well beyond where the majority of investors thing the value ought to be, they induce added buying or selling. Investors who buy when the market has pushed valuation well above what is considered the norm, usually pay a steep price for so doing. The 2005 examples are cases in point. An accepted concept is that the PE ratio should be line with profit growth. One year’s growth cannot be used by itself but investors have to try and determine that themselves.
Most of the stocks in the IC Insider’s Exuberant 10, were pushed in 2017 by excessive enthusiasm and in some cases wrong information. Stock splits helped to fuel some of the excess as well. The attached table shows the stocks that were pushed well above their appropriate values and the levels of correction since. Some may fall even more than their latest price as they can be considered overvalued based on known earnings for the current period. A few that are not on the list could see a decent fall as well, included in this latter list are Knutsford Express and Kingston Properties.
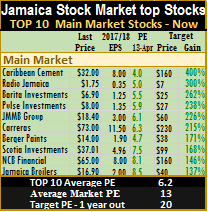
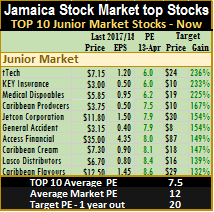 The average PE ratio of both markets are currently at an average of 12, based on this year’s estimated. At the close of the markets on Thursday, IC Insider.com’s TOP 10 Junior Market stocks continue to trade at an average discount of just under 40 percent to the Junior Market average, those in the main market are trading just below 50 percent discount, leaving several stocks with good room for growth for the rest of the year.
 Caribbean Cement continues to trade with a heavy downside bias notwithstanding the rise in price for the week to $32, with last year’s first quarter results dated April 20, this year’s results could be out in the coming week and provide direction for the stock.
 The payment of dividends is only one element to consider in investing in stocks. Investing companies that do not pay dividends should not matter seriously, in the short.
 Jamaica’s sole cement manufacturing company
 Importantly, the cement company took a charge for manpower restructuring, amounting to $421 million, a huge positive development and augurs well for improved profit margin and increased profits going forward. In addition there is a charge for excess inventory amounting to $400 million, this is one off and therefore unlikely to recur. Stripped of these costs, earnings would be up by 63 percent to $1.16 million before tax compared to $708 million in 2015 that includes one off income of $168 million for the quarter and pretax profit of $2.1 billion versus $996 million in 2015.

 When rates start reversing there is going to be some shake out. Rising interest rates and uncertainty drove down stocks value in Jamaica since 2013. Last year Interest rates started to fall and the local stock market started to respond by June last year, slowly at first, but it gradually gathered momentum and by October really started to move up and accumulating in a rise of 36 percent in the main market stocks since.
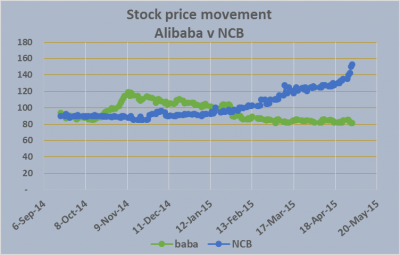 NCB returns less the effect of devaluation of the Jamaican dollar which still leaves a huge gain. On the other hand, Alibaba is now at US$81 and looks like it may well head lower while


Lasco companies batter US$ investment
Lasco Distributors closed at a new high on Thursday of $4
The prices have declined compared to when I bought them and I am concerned about the potential for further decline as the dollar continues to devalue. Should I just cut my losses and sell and convert to FX.”
The prices on June 6 last year were as follows – it took J$111.37 to buy US$1 and now its roughly $120, an increase of just 7.7 percent. Lasco Distributors traded at $1.32 then and is now at $4 for a gain of 203 percent, Lasco Financial Services traded on June 6th last year at $1.15 and gained 156 percent to trade at $2.95 on Friday last week and Lasco Manufacturing was at $1 in June 2014 and has gained 180 percent up to Friday last. It is clear from the above which investment was the better one to have made. Those stock while doing very well have not been the best performing on the local market since then. Cable & Wireless traded at 29 cents in the 2014 period and last traded at $1.05 a 262 percent gain, Desnoes & Geddes was priced at $4.25 and is now at $30, the Jamaica Stock Exchange was then priced at $1.95 and has increase by 464 percent and Caribbean Cream moved from 75 cents to $4.35 for a gain of 480 percent.
IC Insider’s response, thanks for your enquiry. As you will see our BUY RATED list contains these three stocks. Here are our views. First off the local stock market tends to go down around May until last June or July. This is not cast in stone, just a tendency. One reason for it is that investors get the full information as to what companies did last fiscal year and a glimpse for the new-year. In the case of the three Lasco companies they have just reported their full year results. The distributorship earning is the most encouraging of the three and looks like it will probably do better than the other three in the short to medium term. It will also benefit from the Salada Foods distribution which started this year, as well as from increased production to come from the expanded Lasco Manufacturing company’s operation. The information suggest that the next set of results should possibly show growth over that of 2013.
Lasco Financial seems poised for good things, but big marketing spend last fiscal year kept profits down as they went for more market share. It does look as if they will be spending on the world cup promotions which could build business, but may also keep profits pressured somewhat for a while.
Lasco Manufacturing seems cheap at $1 bearing in mind the impact that the factory expansion is likely to have on both sales and profits ultimately. Short term they will have to pick up interest cost and depreciation on the completed factory but will enjoy cost savings and ultimately increased profits.
One need to be careful of converting to foreign exchange at this stage, as the big move in the FX trade could be over. You may have to hold the stocks for a while but the investment could pay off in the medium term, more so in the case of financial and distributorship, during 2014. We would want to see he Q1 results for Manufacturing before jumping.
It is our view that the market overall, is undervalued but investors will need to be patient and the payoff is likely to huge for those who wait, the gains to be reaped elsewhere is not likely to be all that great, to cause one to jump and possibly miss the gains in the local market that is ahead.