Profit surges 159% at Paramount Trading


Profit for the third quarter ending February, this year jumped 159 percent to $24 million from $9.3 million at Paramount Trading, from a 5.7 percent rise in revenues for the quarter to $433 million from $409 million. Net profit jumped a solid 380 percent to $110 million from a loss of $39 million for the nine months period, from a mere 5.5 percent rise in revenues to $1.26 billion compared with $1.2 billion for the same period in the previous year.

Gross profit margin increased to 43 percent in the third quarter from 37.87 percent in the corresponding period in 2025 and for the year to date, rose to 43.85 percent from 35.15 percent in 2025, resulting in gross profit climbing 20.4 percent to $187 million in the February 2026 quarter from $155 million in 2025 and for the year to date it rose sharply by 31.7 percent to $554 million from $421 million, growing sharply to $32 million after tax compared to just $9.3 million in the third quarter of 2025.
Administrative, selling and distribution expenses rose 8.5 percent to $137 million in the third quarter from $126 million in the 2025 period and increased a mere 2 percent to $384 million in the nine months, from $378 million, as selling and Distribution expenses declined 58 percent to $7.2 million in the nine months ended February, from $17 million in 2025. Finance cost declined in the quarter to $20 million from $23 million in the same quarter in the prior year and from $66 million to $64 million for the nine months.
The operations generated Gross cash flow of $137 million, after working capital consumed $59 million and ended cash funds of $85 million at the end of the period and investments of $96 million.
Current assets ended the period at $1.45 billion inclusive of receivables of $516 million, cash and bank balances of $86 million. Current liabilities ended the period at $563 million and Net current assets of $887 million.
Shareholders’ equity close the third quarter amounts with $1.14 billion with long term borrowings amounting to $469 million and short-term borrowings of $84 million.
Earnings per share for the quarter was 1.6 cents and 7.2 for the nine months. IC Insider.com projects earnings of 10 cents per share for the current 2026 fiscal year, giving it a PE of 10.8 times based on the last traded price of $1.08 on the Jamaica Stock Exchange Junior Market. With the market average of 14, the stocks is undervalued. The big question, can the company keep on building on this platform? Recent history, leaves that as the real big question.
The company paid a dividend of 2.6 cents per ordinary share in December 2025.
Profits climb at NCB Group


Jamaica’s largest financial conglomerate, NCB Financial Group, reported profits for the fiscal year to September of $23 billion, attributable to shareholders of the Group or $9.59 per share, with profit of $4.2 billion or $1.73 per share for the September quarter compared with a loss of $330 million in 2024.

The group benefited from a $15 billion one-time gain on the sale of a subsidiary; excluding this, earnings would have been just $13 billion for the year, compared to $13.3 billion generated in 2024 and earnings per share from continuing operations would be $7.60, up from $5.62 in 2024.
The group declared a dividend of 50 cents per share, which will be paid in December and will bring the full year to $2.per share.

The stock is severely undervalued, with a PE ratio of only 5.2 times 2025 earnings and even less based on 2026 earnings, which ICInsider.com projects to rise. The stock, which now trades around $40 each, trades well below the net asset value of $77. Holding back the group is the stagnation in lending, with loans falling to $618 billion from $626 billion in 2024.
NCB is accorded the ICInsider.com BUY RATED award.

TransJamaican dividend yields now 6.4%


TransJamaican Highway board of directors declared an interim dividend payment of 12.92 cents per share payable on October 24, to shareholders on record as at the close of business on October 3, 2025. The ex-dividend date is October 3.

Total dividends for this year amount to 25.5 cents, with a yield of 6.4 percent, including a dividend of 12.58 cents paid in April.
The company’s prospectus in 2020 stated, “based on the projected operating profits, distributable reserves and cashflows, the Company is projecting dividend yield, averaging 5.3 percent to 8.7 percent in 2020-2025 and an average of 24.5 percent to 35.8 percent thereafter on the Offer Price”. The stock was offered to the public at $1.41 and would result in a dividend payment between 34.5 and 50.5 cents per share, starting in 2026, with a yield of 8.6 to 12.6 percent based on the last traded price of $4.
The yield is going to help push the stock price higher into 2026, along with earnings for the current year of around 50 cents per share.

Profit inches up at Scotia Group


Profit declined 7.3 percent to S5 billion at Scotia Group for the April 2025 quarter, compared to $5.4 billion in the similar period last year, as total operating revenues rose by a billion dollars to $15.6 billion from $14.6 billion in the comparable quarter in 2024.

Profit grew 7.8 percent to $9.2 billion after tax for the six months to April, over the previous year. A drop in loan loss provisions to $651 million in the latest quarter from $1 billion in the 2024 second quarter and $1 billion for the half year, down from $1.25 billion in 2024, helped to boost the group’s profit performance.
Operating expenses grew faster than revenues, climbing 23 percent, with an increase of $1.5 billion to $8.3 billion, wiping out the increase in operating income in the second quarter. Corporation taxes amounted to $2.3 billion in the quarter, compared to $2.4 billion in the prior year.

Total operating revenues for the six months ended April 2025, net of expected credit losses, grew by 9.5 percent, or $2.9 billion, to $33.4 billion from $30.5 billion in 2024. This was primarily driven by the growth in loans, which led to an increase in net interest income of $1.9 billion, or 8.5 percent, and an increase in other revenue of 13 percent.

The Group’s asset base grew by $87 billion or 12.9 percent to $764 billion as at April 2025, with loans increasing 14.7 percent to $324 billion. Since the October close of the 2024 fiscal year, loans only grew in the second quarter, at 15 percent per annum, much slower than the 16.3 percent increase in the 2024 fiscal year.

According to the Group, “loan book continues to perform well with mortgages increasing year over year by 24 percent, consumer loans by 14 percent, credit cards by 8 percent and commercial loans by 7 percent.” Deposits, an important fuel for funding loans and investments, increased 10 percent to $514 billion from $467 billion a year ago.
Scotia Group declared a dividend of 45 cents to be paid on July 17, bringing the half-year payment to 90 cents, up from 80 cents for the similar 2024 period.
Earnings per share for the April quarter amount to $1.61 and $2.96 for the half year. ICInsider.com projects earnings of $8.20 for the year ending October 2025.
The stock is ICInsider.com BUY RATED. At the last traded price of $54.91, the stock trades at an attractive PE of 6.7, well below the market average of more than 13. Most importantly, the critical aspect of the business is lending, and the ability to generate reasonable yearly increases in amounts lent out, thus driving revenue growth.

The present state of the Jamaican economy, including lower debt-to-GDP, which allows for greater fiscal space that will facilitate continued lower interest rates, should result in growth in earnings for years to come. With that, investors can look forward to increased dividend payments and stock price appreciation.

ANSA McAl delivers a TT$2.5B blow to shareholders


Shareholders in ANSA McAl are set to lose TT$2.5 billion in 2025 from their investment in the company, following the directors decision to suspend dividend payments, (currently $320 million per year) for 3 years, with the stock price dropping 21 percent from $58 to $46 up to the end of last week.

In addition to losing the $320 million per year for the next three years, shareholders have already chalked up a loss on their shares of $2.1 billion, following the announcement in March, and it could get worse, with the bid to buy the stock at $45 and the offer to sell at $46, last Friday. The dividend suspension will conserve TT$951.5 million for the three years based on $1.80 paid in 2024, 2023 and 2022, but it has had a detrimental impact on shareholders.

In addition to cash savings from the suspension of dividends, the company will save the cost of servicing the twice-yearly dividend payment and will incur less interest expense as a result of the suspension.
ANSA McAL, the majority owner of Berger Paints Jamaica, decided to suspend dividend payments due to the acquisition of a company for US$327 million, which resulted in a US$$200 million loan.
This decision was published on March 21st, 2025, in the Chairman’s statement, which accompanied the audited financial results.  According to the report, “ANSA McAL is confident that the reinvestment of dividends for this three year period will yield far greater long-term benefits – enhancing its competitive position, supporting expansion into new markets, and unlocking new growth opportunities. Moreover, ANSA McAL fully expects the result of this strategic decision to be a significant appreciation in its share price, ensuring that shareholders benefit from a stronger, more resilient, and more valuable company.”
Some shareholders do not buy the optimism expressed by the directors, at least not now. For the year ending December last year, revenue grew by 5 percent to $7.4 billion and profits climbed just over 10 percent to $571 million from $517 million in 2023. On the surface, the stock should have been rising, instead, it has fallen from a 2025 high of $61. Compounding the issue, revenue grew 9.6 percent to $1.8 billion for the March 2025 quarter. Profits for the quarter dived 50 percent to $54 million from US$107 million as finance cost surged from $10 million to $52 million.
The directors commenting on the 2024 results stated, “Beyond these outstanding financial results, we took a bold step forward in our long-term strategy by completing the largest acquisition in our 143-year history. The US$327 million acquisition of BLEACHTECH LLC, a leading US-based chlor-alkali producer, is a transformative move that positions us for even greater success.”
At the end of March, Shareholders’ equity stood at TT$8.2 billion. At the end of December last year, borrowed funds amounted to $2.6 billion, just around 32 percent of shareholders’ equity. With the leverage level so low, there seems to be no need to suspend dividends and, by extension, destroy shareholders’ investment.

Scotia profit surges 35%


Profits jumped a solid 34.5 percent at Scotia Group with $4.2 billion in net profit for the quarter that ended January, this year, for an increase of $1.1 billion over the $3.21 billion in 2024, with earnings per share rising to $1.35 from $1 in 2024.

Total revenues excluding expected credit losses for the year ended January 31, 2025, grew by $2.2 billion to $17 billion, for an increase of 14.9 percent over the prior year period, primarily driven by growth in loans leading to an increase in net interest income of $1.1 billion or 10 percent as well as an increase in other revenue of 26.2 percent.
Other income, other than interest income, increased by $1.2 billion or 26.2 percent. Net fee and commission income for the period amounted to $2.2 billion. an increase of $672 million or 42.9 percent, primarily driven by the higher volume of client transactions and activities.
Total loans increased from $275.7 billion to $313 billion, an increase of 13.3 percent over the $276 billion in January 2024 but flat with October last year. Growth over January 2024 “includes a 12 percent increase in Scotia Plan personal loans and a 24 percent increase in mortgage loans. Commercial loans also increased by 5 percent over the prior year period,” the release from Scotiabank stated
The Board of Directors approved a dividend of 45 cents per share for the first quarter, payable on April 17, to stockholders on record at March 26.

Scotia a Xmas of goodies in 2025 & beyond

Scotia Group delivered a respectable 17 percent jump in profit to shareholders in the just concluded fiscal year to October. Investors drove the price up a solid 34 percent for the year to date, in addition to dividends amounting to $1.70 as revenues climbed 15.8 percent to $69 billion from $59.6 billion in the October quarter, with profit after tax rising to $20.15 billion from $17.2 billion in 2023. For the October quarter, profit rose a solid 32 percent to $6.16 billion from $4.67 billion in 2023.


The group paid dividends amounting to $5.1 billion during the fiscal year versus $4.2 billion in 2023 a payout ratio of roughly 25 percent of the annual profit. A dividend of 45 cents per share has been declared for payment in January 2025.
Total revenues rose 16.2 percent for the October quarter to $18.4 billion from $15.84 billion in 2023.
B growth in loans the main propeller of increasing profits, climbed 16 percent for the year to $312.76 billion but rose at an annual rate of 22 percent in the second half and 29 percent in the final quarter. With lower interest rates expected in 2025, the demand for loans could grow even faster than in the final quarter, subject to demand and management’s decision to take on increased risk.
Interest Income rose 14.5 percent in the last quarter to $12.64 billion from $11 billion in 2023 and for the year it moved up 18.4 percent to $59.7 billion from $48.34 billion in 2023.
Net interest income rose 15.4 percent to $12 billion in the last quarter of this year, from $10.57 billion in the prior year and for the full year, it jumped 17.4 percent to $46.3 billion from $39.46 billion in the previous year. Net fee and Commission income went from $1.8 billion in the $2.1 billion in October 2024 quarter and increased 17.2 percent from $6.74 billion in the half year in 2023 to $7.23 billion in the current year.
Other income amounted to just $158.6 million in the October 2024 quarter, up from $67 million in the previous year and for the fiscal year, rose 25.5 percent to $661 million from $527 million. Insurance premium income jumped 51 percent to $1 billion for the latest quarter, up from $673 billion in the prior year and for the year to October grew 26 percent from $2.79 billion in 2023 to $3.5 billion.
Net foreign currency activities generated revenues of $2.48 billion up 9.5 percent from $2.27 billion in the comparative period in 2023 and for the year, revenues rose 6.4 percent of $9.3 Billion versus $8.75 billion in 2023.
Credit impairment losses jumped sharply by 71 percent to $1.26 billion in the October quarter from $740 million last year and for the fiscal year, it climbed 73.5 percent to $4.16 billion from $2.4 billion in 2023.
Segment results show third party revenues for Corporate and Commercial banking increasing 11.3 percent to $15.8 billion, with revenues of $14.2 billion in 2023. Net segment results surged 24 percent to $13.7 billion over $11.1 billion in 2023. Treasury segment generated revenues of $15.75 billion up 24 percent from $12.68 billion in 2023 with a profit of $4.86 billion in 2024 up 36 percent compared with $3.57 billion in the previous year. Investment Management Services generated a 1.7 percent growth in revenues of $3.14 billion and net results that rose just 2 percent to $1.77 billion in 2024, with revenues of $3.1 billion in 2023 and net results of $1.73 billion. Insurance Services accounted for revenues of $4.76 billion, up 13 percent over $4.2 billion in 2023 and net results of $4.8 billion up by 24 percent compared with 2023, with revenues of $4.2 billion and profit of $3.9 billion.

Staff cost fell 10 percent in the last quarter to $2.92 billion from $3.24 billion in 2023 and rose 6.3 percent to $11.8 billion in the current year from $11.1 billion last year. Other operating expenses rose 4.2 percent to $3.1 billion in the quarter from $2.99 billion in 2023 and increased 4.6 percent in the year to $13.24 billion from $12.66 billion in the prior year. Tax on assets rose 13 percent to $1.55 from $1.376 billion in 2023. Taxation rose 16 percent to $9.55 billion, for the year from $8.2 billion in 2023.
Customer deposits grew by 7 percent to $479 billion. Shareholders’ equity ended the period at $138.5 billion, up from $126.5 billion at the end of October 2023.
Earnings per share for the quarter amounts to $1.98 and $6.48 for the year. IC Insider.com projects earnings of $9 per share for the 2025 fiscal year, with a PE of 5.8 times the current year’s earnings based on the price of $52 the stock traded at on the Jamaica Stock Exchange. Net asset value ended the period at $44.50 with the stock selling at a low 1.15 times book value.
Scotia Group has the ICInsider.com Buy Rated seal of approval.

Scotia closed with limited offers


Scotia Group stock price jumped $2.91 on Thursday to close at a new 52 weeks’ high of $52.90, with investors trading 41,710 of the shares, following Tuesday’s price hike of $3.99 with the stock trading then at a 52 weeks’ high of $49.99, after investors traded 161,674 shares.  
Scotia is expected to release full year results after the market closes on Thursday and announce an interim dividend. IC Insider.com forecast is for earnings of $6.50 per share following nine months’ earnings of $4.50, with $1.75 for the July quarter.

The group paid a dividend of 45 cents per stock unit on October 18, this year and is expected to declare a similar amount at its meeting on Thursday.

Supply of the stock declined in recent weeks, but buying has been restrained ahead of the full year’s results. The accompanying chart shows the buying and selling interest at the close of the market on Wednesday.

The stock trades on the Main Market of the Jamaica Stock Exchange has gained  38 percent for the year to date.

Share buy back & dividend at Kingston Properties

Kingston Properties (KPREIT) plans to repurchase up to one half of one percent or 4.42 million shares in issue for up to two years to commence in the later part of May this year. 
According to the release, “the Board of Directors sees this use of capital as an opportunity to enhance shareholder value through the purchase, from time to time, of undervalued shares”.
The repurchase of the shares will be done using the Company’s cash flows and will be conducted on the open market through the Company’s stockbrokers. A fixed price for the repurchase will not be set but will be the market price at the time of the repurchase. In keeping with the requirements of the Companies Act of Jamaica, within 30 days of the dates of the repurchase of shares, Kingston Properties will advise its shareholders of the details of the shares purchased.
The company has 884 million issued shares that were last traded at $8.10 on the Main Market of the Jamaica Stock Exchange with a PE of 10 times last year’s earnings and a book value of $8.40.
A total of 7.5 million shares were traded over the past twelve months for a daily average of 30,000 units.
The company has also declared a dividend of 0.0566 US cents per share, payable on June 5 to shareholders on record at May 17 with the ex-dividend date of May 16, 2024.
The company reported a profit of US$4.65 million in 2023 an increase over 2022 with US$3.8 million from operating revenues of US$4 million in 2023 and US$3.5 million in 2022. Profit was boosted by gains from revaluation and gain on sale of properties of US$3 million in 2023 and US$2.4 million in 2022.

Top 5 JSE dividend paying stocks now


Companies with earnings that are consistently growing are usually the best dividend paying stocks to invest in if income is a prime objective. They will have more room to make increased dividend payments in the future.
Investors looking for the best dividend paying stocks on the Jamaica Stock Exchange should take the above factors into consideration. It is also a good factor to consider when buying stocks that are likely to increase in value over time.
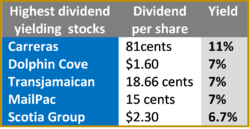
On the Jamaica Stock Exchange, the Main Market, Carreras is the king of dividend payment with a yield of 11 percent based on the latest stock price of $8 in 2023, followed by Transjamaican Highway and at 7 percent, Scotia Group at 5 percent based on the last dividend paid of 40 cents and annualised, at a then stock price of $34. What is interesting about Scotia is the traditional metric is for the company to pay between 40 to 50 percent of profits.
Scotia historically pays just above 40 percent of profit, but that seems to have been interrupted as a result of the negative impact that flowed from the Covid 9 economic dislocation. The company reported earnings of $5.54 and that would suggest an annual dividend of $2.20 which would translate to a dividend yield of 6.7 percent with 2024 likely to be higher.
The Junior Market has two stocks with attractive yields Dolphin Cove and MailPac at 7 percent each. The payout for MailPac represent a full years’ profit.
Yields may have dipped in some cases but that does not change the longer term prospects.