BUY RATED top Carib markets with 830%

The JSE stock racked up huge gains in 2015

The JSE stock racked up huge gains in 2015

IC BUY RATED stocks were top of the Caribbean markets in Jamaica and Trinidad and Tobago for 2015, with Jamaica Stock Exchange share, chalking up a massive gain of 830 percent since IC Insider elevated it to BUY RATED status.Caribbean Cement followed with gains of 640 percent, Caribbean Cream with 444 percent and Trinidad Cement with a 299 percent increase on the Trinidad market.
While it was easy to make money in Jamaica, with profits rising and interest rates falling, developments in Trinidad went in the opposite direction, with interest rates rising and profits under pressure with the economy ended in recession.
At the beginning of 2015 of the 14 junior market selections, few recorded gains and only Knutsford Express with a 17 percent increase reflecting any meaningful positive movement. Losses were large, with AMG Packaging down 39 percent, Blue Power 31 percent, Caribbean Cream 23 percent, Jamaica Teas 28 percent, Lasco Financial 37 percent and Lasco Manufacturing 32 percent. What a difference a year can make? By the end of 2015, gains were all over the place with the list having 17 companies with two being dropped. There were no losing stocks in the list that had a new addition, tTech which could be listed this week. Honey Bun was added to the listing in November and gained 9 percent since. Eight stocks have more than doubled, four gained 40 percent to 91 percent. Caribbean Cream jumped 292 percent to be the top selection in this market, followed by Lasco Distributors up 274 percent. Blue Power was removed from the list in July with a small gain.
In the JSE main market, at the start of 2015, Hardware and Lumber was the best performing stock with gains of 62 percent followed by Cable & Wireless with 47 percent and Jamaica Broilers had the worst performance with a loss of 24 percent. In all, 7 of the 15 selections were lower than at the time they were BUY RATED.
By year-end, all selections in the JSE main market were up, with Scotia Investments having a mere 15 percent increase, being the poorest performer. This stock is being moved to Market Watch as the 2015 profit performance was far too disappointing to warrant buying now, while Hardware and Lumber remains a hold. The rest, present opportunities for continuing profit making. BUY Rated fn 12-15JMMB Group ended with just 28 percent gain, but seems undervalued at the current price. While the list had a few lousy performers, the same can’t be said about a 640 percent gain in Caribbean Cement and 830 percent increase for Jamaica Stock Exchange share. In all, 9 stocks posted gains in excess of 100 percent and 4 below 100 percent but with a 50 percent increase and more.
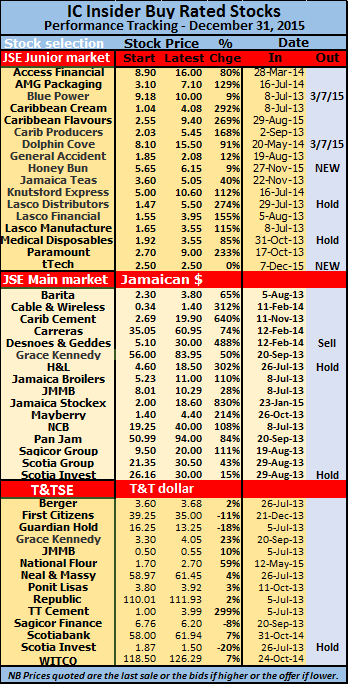
There were 13 selections in the Trinidad market with Trinidad Cement being the best performer with gains of 150 percent, the next was Point Lisas with 11 percent at the start of 2015. Five stocks suffered losses with the highest being 22 percent and the next 18 percent. For 2015 the price of Trinidad Cement is up 299 percent followed by National Flour with a 59 percent gain.
Looking ahead, the junior stocks should continue to grow, with several of the companies actively expanding resulting in profits climbing at a fast pace. There are a few stocks to be cautious of just now. Lasco Distributors selling at almost 16 times 2016 March earnings. Growth should be strong but unless investors have a long term objective they should be careful buying at current price level, the same applies to Lasco Financial that is selling at 15 times earnings. Dolphin Cove remains a hold at this time.
The Trinidad market needs to be watched at this stage, with the country needing to adjust to the lower price of oil and the recession now being endured.

Dividend triples for H&L owners

H&LShareholders of Hardware Lumber (HL) will be paid an interim dividend for the year 2015 of One Dollar and Nine cents per stock unit on January 29, this year, to shareholders on record as at the close of business on January 15.
The ex-dividend date for the payment is the January 13. The company paid 32 cents per share in dividends in 2014 and 30 cents in 2013.
The payment comes against the background of lower profits in the year to September and acquisition of the majority shares by a group of investors.
Total revenue for the nine months to September 2015 was $5.37 billion or 2.3 percent more than the comparative period in 2014. Profit after tax for the nine-month to September 2015 was $64 million, 43 percent less than the $113 million for the same period in 2014 and earnings per share of 79 cents, compared to $1.40 for the similar period in 2014.
On Thursday December 30, Grace Kennedy’s 58.15 percent interest amounting to 47,013,417 shares in Hardware & Lumber, were traded over the Jamaica Stock Exchange at $18.50 each.
The shares were bought by Argyle Industries Inc. (“Argyle”) a St. Lucian Company special purpose vehicle incorporated for the purpose of acquiring and holding the Investor’s equity interests in Hardware & Lumber.

Strong profit gains at Broilers

JBG ChickChicken meat and feed processors, Jamaica Broilers recorded an impressive 297 percent increase in net profits attributable to shareholders for the quarter ending October 2015 amounting to $408 million and earnings per share of 33.8 cents according to the interim financial results.
For the six months, profit rose a very strong 242 percent to hit $740 million with earnings per share of 61 cents. IC Insider forecast earnings for the full year at $1.30 and $1.70 for the 2017 fiscal year. Broilers generated $1.76 billion in gross cash flows from operating activities during the half year.
The stock last traded on The Jamaica Stock Exchange at $10 for a PE of 7.7 times this year’s earnings, leaving room for moderate growth based on 2015/16 results and current valuation of stocks.
Sales revenue for the October quarter rose 6 percent to $9.17 billion, compared to $8.68 billion in 2014 and by 9 percent for the half year to $18.1 billion. Gross profit for the quarter increased 30 percent to $2.28 billion, from $1.75 billion of the corresponding quarter last year and grew by 31 percent for the six months to $4.56 billion.
The “US Operations performed as expected with respect to the sale of our main product –fertile eggs for the broiler industry. The year to date segment results amounted to $538 million. Our presence in the markets remains strong, with a broad customer base and we are seeing the benefits of the US dollar hard currency earnings. We expect steady growth in other product lines in this segment. We are recording increased sale volumes in poultry and feed products, consequent on targeted marketing strategies,” the company’s management stated in their report to shareholders.
“In the Other Caribbean Operations, Haiti Broilers SA has increased production and sale of table eggs to 14% of the market, compared to 12% at the end of the second quarter last year. The positive effect of this volume growth has however been neutralized by significant increases in operating costs due to the continuing depreciation of the Haitian Gourde against the US dollars”, the management report went on to state.
JB 10-15Cost overall climbed with some increasing much faster than revenues. Distribution and selling cost rose in line with revenues with an increase of 9 percent in the quarter and year to date with cost of $260 million in the quarter and $508 million for the half year. Administrative costs, tripled the growth in revenues in the October quarter to be up by 19 percent to $$1.4 billion and increased by 18 percent for the six months to $2.9 billion. Finance cost fell in the quarter and grew slightly or the half year while interest income rose strongly.
Cash and short-term investments totalled $2.36 billion, Current Assets amounted to $11.4 billion and current liabilities at $6.8 billion, shareholders’ equity stands at $12 billion and borrowings at $6.3 billion, down from $7 million in 2014.

Grace Kennedy sells H&L interest

Grace HStGrace Kennedy has sold its 58.15 percent interest in Hardware & Lumber (H&L) with the shares traded over the Jamaica Stock Exchange floor today by broker – GK Capital Management in the amount of 47,013,417 shares at $18.50 each.
The shares are sold to, Argyle Industries Inc. (“Argyle”) a St. Lucian Company special purpose vehicle incorporated for the purposes of acquiring and holding the Investor’s equity interests in Hardware & Lumber. The investors in Argyle include a group of investors led by, ABBECO INVEST S.A. ( a Bahamian investment company), Sterling Asset Management along with its affiliates and associates and Greystone Equity Partners Inc. along with its affiliates and associates a release from Grace Kennedy said.
Grace Kennedy Group CEO, Don Wehby, stated “As previously indicated GraceKennedy’s decision to sell our shares in H&L was not an easy one, however, this divestment is consistent with our present strategy of concentrating on the food business locally and internationally and financial services in the region.” He added, “I feel very positive about the continued growth of H&L under the prospective new owners, Argyle, who are excited about the possibilities for the future.”

Rapid True Value owned by Hardware & Lumber an associate of Pan Jam

Rapid True Value owned by Hardware & Lumber an associate of Pan Jam

Total revenue for the nine months to September this year was $5.37 billion or 2.3 percent more than the comparative period in 2014. Profit after tax for the nine-month to September 2015 was $64 million, 43.2 percent less than the $112.9 million for the same period in 2014.
H&L comprises the Rapid True Value and the Agro Grace business. There are currently 10 Rapid True Value outlets across Jamaica, along with six Agro Grace Retail Centres. The company is headquartered at in Kingston.
The buyers will be required to make an offer to buy the remaining shares at the same price of $18.50.

Cargo Handlers growth slows

CAR H 2015-06-26Cargo Handlers profit for the year to September was barely higher than for that of 2014 at $136 million versus $132 million but the company had some one-off expenses amounting to $16 million. Revenues climbed to $252 million from $236 million in 2014.
The final quarter of the year saw lower revenues of $67 million, down from $79 million in the September 2014 quarter while profit fell 40 percent to $29 million from $48 million in 2014. Cargo Handlers recorded earnings per share of $3.63 versus $3.52 in 2014.
Going forward, the tax free holiday the company enjoyed from December 2010, ends in November this year and moves to 12.5 percent for the next 5 years. This will dent profits a bit, added to that, the company made $6 million in foreign exchange gains in 2015, that looks uncertain going forward with the adjustment in the value of the Jamaican dollar that now seems appropriately valued, but for likely moderate movements in 2016.
Unless there is a dramatic change in revenues, profit after tax for 2016 should grow marginally to around $145 million or $3.87 per share.
The company ended the year with $151 million in cash included in current assets of $203 million and only $15 million in current liabilities. Equity is $245 million with virtually no interest bearing debt. The stock which is listed on the junior market of the Jamaica Stock Exchange last traded at $37.50. Two dividends amounting to $2.35 per share were paid during the year.

RJR shareholders set to halt merger

Gleaner & RJR execs signing merger agreement earlier in 2015

Gleaner & RJR execs signing merger agreement earlier in 2015

The much talked about merger between the Gleaner media business and Radio Jamaica (RJR) seems headed to defeat as the large shareholders in RJR are set against the present proposed terms of the deal.
A number of the larger shareholders are of the view that the deal does not benefit them as much as it bails out a struggling Gleaner that has had great difficulty making a profit from the media business for several years now.
One point put forth is that is that print media is not an area of growth compared with the electronic media, that is seen as having good growth potential. The effect of the merger would result in a dilution of the RJR shareholders interest the disgruntled shareholder say and that appears to be the case initially. The proponents of the merger says there will be savings and added revenues amounting to $275 to $450 million that will enhance the fortunes of the new group, but only half of that will be attributable to the existing RJR shareholders.
What have not been said publicly, is that since the valuation in March, much have changed with RJR fortunes improving and Gleaner’s lagging, which would most likely change the values of each.
For the nine-months, the Gleaner made $130 million net profit or 122 per cent more than the $58.6 million earned a year earlier. Revenues continued its downward drift, by 5.6 percent to $2.38 billion, partially helped by a fall of $34 million in investment income to $90 million while media income fell $120 million for the same period. RJR was going in the opposite direction with profit jumping 227 percent in the September quarter to $30 million and 44 percent in the June quarter to $22 million from revenues that rose 24 percent in the September quarter and 7 percent in the June quarter.
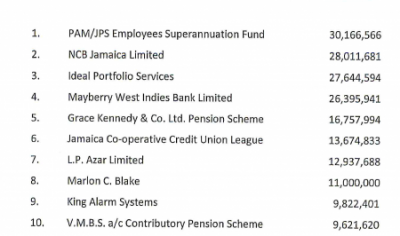
RJR's Top 10 shareholders at September 2015

RJR’s Top 10 shareholders at September 2015

IC Insider’s forecast is for RJR to make $320 million for the year to March based on existing operations and for the Gleaner to report $240 million for the year to December 2015 from all its current operations.
Apart from Gleaner offering the media assets they will contribute $665 million in cash and equivalent. While the latter could theoretically buy around 50 percent of RJR’s current outstanding shares, at existing prices under $4, supply would not allow them to do so. By pumping in the funds that is likely to be earning very low returns until they can be used in an efficient manner, will result in dilution of existing RJR shareholders’ interest.
With 75 percent of shareholding required to approve the deal, there are enough disgruntled shareholders on the RJR side to vote it down. Based on feed-back received from some larger holders, it appears that at best the principals of both companies will have to go back to the drawing board and involve the larger shareholders in the talks if they are to succeed, something Chairman of the Gleaner Oliver Clarke says he is not opposed to.
Shareholders openly opposed to the deal, account for 49 million shares or 13.7 percent others who have been opposed at least up to recently, would bring the tally to more than 21 percent.

First Citizens flat 2015 numbers

First-Citizens_logo600x250pxAs Trinidad and Tobago struggled with recession in 2015 profit for the year ended September 2015 resulted in a marginal increase from TT$627 million in 2014 to TT$630 million for First Citizens Bank, a Trinidadian based and Trinidad Stock Exchange listed bank.
The performance emanated from revenues of $1.76 billion net of $282 million in interest cost, compared to $1.68 billion net of interest cost of $315 million in 2014. For the September quarter profit fell to $148 million from $157 million reported for the June quarter.
While interest income was marginally down to $1.45 billion from $1.47 billion for the 12 months, fees and commissions rose sharply by 28 percent to $415 million from $360 million, gains on sale of financial assets, netted only $27 million versus $66 million in 2014 while foreign exchange gains, rose to $12 million from $76 million.
Driven mainly by a 19.5 percent increase in the wage bill that hit $425 million administrative expenses rose 13.8 percent to $594 million from $522 million and other operating expenses were flat at $390 million as technical and professional fell to $21 million from $38. Loan losses fell to $6 million from $13 million in 2014 but taxation climbed to $160 million from $146 million thus reducing a 4.7 percent increase in pretax profit to a virtually flat net results for the year, with earnings per share of $2.51.
Investment assets amounted to $12.3 billion up from $10.4 billion in 2014 while loans grew to by $1.6 billion in the final quarter to $17.3 billion and is up from $14.9 billion at September 2014.
With Trinidad now in recession and the price of oil under US$40 per barrel, institutions such as banks could see their income and profit under pressure in 2016 as demand for loans remain weak. The stock last traded at $35 on the Trinidad Stock Exchange with a PE of 14 and don’t seem to have much room for growth in the months ahead.

A rich 2015 for JSE shareholders

JSe online logoShareholders in Jamaica Stock Exchange (JSE) are having a wonderful 2015. The stock last traded at $1.57 in December 2014 and has since shot to $16 for a gain of 919 percent but if that was not enough the company has declared a dividend of 47 cents per share payable on December 30, to shareholders on record as at December 23. As great as the gains for 2015 has been so far for the JSE stock price is still lags some of the best gains ever recorded for the market with highest being West Indies Glass with a n astounding 3,438 percent in 1985 followed by Jamaica Flour Mills with 2,054 percent in 1984.
JSE highest gns -12-15The stock will trade ex-dividend on December 21. In July this year, the JSE paid 53 cents per share which brings the total payout to $140 million and to $1 per share making for a dividend yield to a staggering 63.7 percent based on the 2014 closing price.
The JSE reported earnings of $139 million in nine months to September this year, from $8 million in 2014 and seems set to increase profits in 2016 that should push to stock up even further with strong prospects of another year of big dividend payment.

70c for Goodyear Ja shareholders?

goodyeartyreGoodyear Shareholders could get another 70 cents from the liquidation of the company according to information gleaned by IC insider. Shareholders in Good Year Jamaica expected the liquidation of the company to have been completed long ago. The liquidators made two payments and then there was dead silence since, with no one indicating what was happening.
The liquidators sold off inventories and fixed assets but Income Tax refund of $17 million and General Consumption Tax (GCT) refund $9 million was outstanding up to 2008 with recovery having been protracted and unlikely to be fully collected due the absence of withholding tax certificates on interest income. Of $21 million claimed for withholding tax between 2000 and 2008 only $14 million is accounted for leaving $6.9 million primarily for 2003 and 2006 to 2008. Seems strange that the staff of the company have left shareholders to suck up such losses and they will end up getting all the surplus on the pension fund.
Refunds totaling $12 million up to and including 2012 were agreed with the tax authorities and the amount for GCT seems to be collectible and should amount to $16 including interest.
The liquidators indicate that they accepted the liquidation for a fixed fee of $1.5 million on the basis that the company was solvent and the winding up process would be resolved within a reasonable time. They are now requesting $18.7 million which is well above the original figure and collected $4.3 million to 2014. But looking at the details it is noted that sitting in a bank current account is $5.7 million in 2013 and $5.4 million in 2014. At the start of 2013 the current account balance was $6.8 million. The big question is why were the funds left in the current account and not placed on an interest earning account to generate interest income? It is difficult to see how the liquidators want more funds when they have fowled here and one wonders how much interest income has been lost due to poor handling of the funds.
Assuming no more funds are collected than those agreed to, the amount that is available should be in excess of $55 million before the liquidator’s fees are finalized.

tTech is BUY RATED for strong growth

TtechtTech is going to the capital market this month to raise approximately $50 million by the issuing for subscription 25,652,000 shares to the general public and special interest group with the general public being asked to pay $2.50 each for 16.4 million being made available to them.
IC Insider assessed the company’s record and forecast increased earnings for 2016 and 2016 and accorded it the BUY RATED honour.
Edward Alexander, Chief Executive Officer, in an interview with IC Insider stated that the staff of the company indicates that they will all be taking up their full allotment, if so there will be few of these shares available for the public to acquire at the IPO stage.
The Company was incorporated in Jamaica on December 1st, 2006, and is a managed information technology (“IT”) service provider, or what industry insiders refer to as a “Managed Services Provider”. That is, for the most part, the Company’s main service offering is the management of other businesses’ IT infrastructure remotely and on a pre-paid basis.
The company is growing at an attractive rate with revenues that are up 28 percent for the half year to June to $81.4 million versus expenses increasing 18 percent and only 14 percent when technical fees, services and products that are part of direct expenses are excluded.

From Left: Mr. Hugh Allen, Resolution Manager and Executive Director; Mrs. Natalya Petrekin, Service Desk Manager; Mr. Norman Chen, Technical Services Director; Mr. John Gibson, Senior IT Security Officer; Mr. Edward Alexander, CEO; Mrs. Hortense Gregory-Nelson, Finance and Administrative Manager; Mr. G. Christopher Reckord, Sales and Marketing Director. Mr. Omar Bell.

From Left: Mr. Hugh Allen, Resolution Manager and Executive Director; Mrs. Natalya Petrekin, Service Desk
Manager; Mr. Norman Chen, Technical Services Director; Mr. John Gibson, Senior IT Security Officer; Mr.
Edward Alexander, CEO; Mrs. Hortense Gregory-Nelson, Finance and Administrative Manager; Mr. G.
Christopher Reckord, Sales and Marketing Director. Mr. Omar Bell.

The 2015 performance is better than that of the full 2014 financial year, when income was up 18 percent but profit fell 13 percent before taxation and 5 percent after tax. In 2013 revenues rose 35 percent and 5 percent in 2012 while pretax profits grew 62 percent in 2011, in 2012 by 21 percent and in 2013 by 38 percent. Alexander advised that they expect revenues for 2016 to grow around 15-20 percent, at the same level they estimated for 2015. “Growth continues to be strong at a robust level since the six months to June” Alexander said.
IC Insiders’ forecast, based on continuation of good revenue growth, is for profit before tax for 2015 to end at $36 million or 45 cents per share and $27 million or 35 cents per share after tax and $64 million or 60 cents per share for 2016. This gives it a PE based on 2015 earnings before tax of 5.5 and for 2016 of 4 and compares with junior market stocks with PE of 8, with half of the market selling above the average, suggesting that the stock should enjoy a nice bounce over the next twelve months or less. The company has $51 million in cash and no borrowed funds with current liability of just $27 million, so why do they need to raise the funds? “Expansion into security services will require added equipment, software working capital for continued expansion” Alexander stated, in addition listing allows the staff to be part owners and benefit from future growth.
Ttech figs 12-15fnThere are a number of positives for the company it is in a good growth industry with potential for regional expansion, the Grace Kennedy contract and relationship could provide them the experience to take on other large regional conglomerates. They are a service-based business with high gross profit margin which is a big positive and if growth continues at current levels would contribute to a big increase in profit. A lot of the business is recurring, providing stability to the operation. The founders’ vested interest will remain strong as they will still hold relatively large percentage of the company after the IPO.
Only about 15% shares being offered to the general public the stock almost guaranteeing that it will be in relatively short supply which could drive price up quickly after listing, this is especially so being the first tech company on the JSE.
Subscription opens at 9 am on December 16th, 2015 and closes at 4:30 p.m. on the December 18th, 2015, subject to the right of the Company to shorten or extend the time for closing. All completed Application Forms must be delivered to NCB Capital Markets.