 Prices on the Jamaica Stock Exchange are on the move again as the last quarter of the year approaches. As prices rise so does the PE ratio. The top PE in the main market is at 17 while in the junior market is around 18.
Charts of both markets show them in a bullish state, with the markets hitting higher lows and higher highs, a strong indication that they will be moving higher. More than 50 percent of main and junior market stocks are priced below the markets average PE of 9.5 and 10.4 respectively.
Against this background, IC Insider’s Top 5 selection has one new listing in the main and junior market list as Grace Kennedy and Jetcon Corporation are replace by Radio Jamaica and General Accident in position 5 and 4 respectively. Jetcon hit new highs during the week and closed at $4.70 up from $4.35 at the start of the week. Radio Jamaica earnings have been upgraded to 25 cents per share with increased revenues and cost cutting. General Accident is not without risk but earnings for 2016 are up 155 percent against a battered first half of 2015 and 2016 should better the 31 cents earned for the 2015 financial year.
AMG Packaging remains at the top of the junior market list even as the price moved up while JMMB Group is atop the main market with Caribbean Cement drops to 4th with a rise of $4 during the week. Investors attempted to trade Carib Cement at $34 but market breaker stop it from standing the stock which closed at $30 traded as high as $32. There are just six offers in the market starting at $34 and worth keeping an eye on this one for more gains this week. Barita Investments traded up to $4 during the past week and could well end back at this level during the days ahead as supply declines and demand increases.
 Watch these stocks for action this week – Access Financial Services with the bid at $18.50 with no stock on offer, Blue Power with a wide gap between bid and offer, Cargo Handlers with the bid moving away from the last sale price of $86.10 with the offer at $100. Caribbean Cream with increasing demand, Caribbean Producers gaining support after poor full year results, Derrimon Trading and General Accident with bids getting stronger, Jetcon Corporation with supply and increasing interest, Medical Disposables and tTech with supplies.
From the main market the main action could come from the following, Barita Investments, Caribbean Cement, Jamaica Stock Exchange, JMMB Group, Radio Jamaica, Sagicor Group, Scotia Group, Seprod and Sterling Investments.
Stock split who is next?
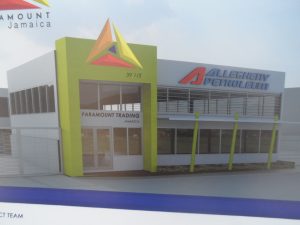
Paramount with the stock priced at $17.50 with virtually no supply seems a candidate for a stock split.
Companies on the Jamaican Stock Exchange have either announced or effected stock splits or bonuses this year, to loud applause by investors who have driven the stocks sharply upwards in response to the news.
The first to do so was Jamaican Teas with the price doubling after the announced split. Honey Bun followed with the price climbing sharply after the announcement as well as after the split. RJR did both a split and a bonus. GraceKennedy and Pan Jamaican that have seen their stock struggling for a long time at very low levels, finally getting the lift with the announcement of a stock split. Jamaica Producers effected a bonus with a similar price movement. Cargo Handlers and Jamaica Stock Exchange announced stock splits and the investors immediately responded positively to them by driving the prices up. If the trend seen with other splits holds, the prices of the stocks of the latest announcements will rise further after the split takes place.
Stock bonuses were a regular feature of the market for years until the government removed the tax incentive for them. Only the three Lasco companies split their stocks to create greater liquidity in 2014. With mostly 20 percent of junior market companies’ shares in the wider public’s hands and with some of the twenty percent closely held, supply is not always easy to come by. Splitting the stock encourages increased valuation of the companies and allows for some to be sold to the wider market, thus increasing liquidity.

Palace Amusement with a price tag of $170 and virtually no supply should be a prime candidate for a split.
There are more stock splits to come, so who are the likely candidates. One would expect that Eppley, with a $735 price tag and very limited trading activity, would be a good candidate and so would Palace, with a price of $170. Based on what has happened in the past don’t count on these two to take such action anytime soon, but the directors of these companies are going to be pressured into making a move. Management who are conscious of the valuation the market places on the stock would do the things that would boost investors’ confidence in the stock. With limited liquidity, the companies are losing out on one of the most important benefits of listing which is the constant publicity garnered from having the company’s name repeated publicly daily.
Other candidates ripe for a split include Paramount Trading, a stock that has limited supply, the company is yet to announce its annual general meeting and that seems a very good time for it to be approved. Blue Power now priced at $21 with very little supply is a prime stock for such action. Others that could well do it are Access Financial Services,

AMG Packaging with a new chairman who is stock market friendly could deliver a split sooner than later.
AMG Packaging with a change in chairmanship who is a stock market follower should land a split sooner than later and Knutsford Express in the junior market.
There appear to be few main market stocks that need to consider one but National Commercial Bank with the price struggling around $40 with good results could well do one to increase investors’ interest and so could Scotia Group and of course Montego Ice.
If stock splits are so popular in Jamaica, why is it not being used in Trinidad that only has limited trading taking place daily. Management is depriving their company of maximum exposure for the cost of listing and preventing their shareholders from enjoying a more liquid market in which to trade.
Buy stocks before the explosion
Image courtesy of suphakit73/FreeDigitalPhotos.net
Both markets have some appealing choices that offer investors a great deal of potential upside. Investors have been making big mistakes by ignoring these opportunities. The errors keep showing in junior market stocks where many wait until prices start to move before trying to buy, at which time the volumes dry up and prices have to move steeply for sellers to be induced to dispose of stocks. Recent cases in point are, ISP Finance, the stock was available under $3 but there were very few buyers, now there are many buyers with bids in the $6 region, a level at which there has been no stock offered for sale since it traded nearly 23,000 units at $6, earlier in September. Jetcon Corporation is another case, with the stock trading below the $3 level for a long time until recently, even as the profit of the company is running at almost twice the pace of 2015, now they are more investors interested at the higher prices at a time when the supply has evaporated. Caribbean Cream is yet another, with IC Insider pointing to strong increase in profits for a long time, now buyers are in at much higher prices but supply is limited. tTech is yet another example with the stock trading for a long time in the $4 region now there is virtually no supply as interest in the stocks grows.
 While some investors focus on trailing quarterly earnings as the basis for valuing stocks, they tend to miss out on companies with explosive growth in profits. There is also the tendency to ignore one off time items. The case of Caribbean Cement is an excellent one. A Brokerage house has the earnings at just over $2 for 2016, but the ongoing earnings are likely to be in the $5.50 region for 2016 and this is what they should be using to value the company. Investors seem to miss the main point. The company incurred cost for reducing labour which will show up as lower operating cost in future periods, but investors don’t seem to appreciate that fact, added to what now appears to be an economy that is growing and could grow even more making Cement, a huge buy. The same can be said for National Commercial Bank and Scotia Group that are having a great 2016.
An indication of where values could reach based on this year’s earnings can be gleaned from three stocks selling at PE ratios that are 16 to 17.5 times this year’s earnings with 11 out of the 29 junior listings having a PE of 10 times or more with, an average of 13.5. The average of the junior market is now at 10 times 2016 earnings with several stocks selling below. In the main market the top 11 stocks average PE is just over 15 with the overall average for the market at 9.
Based on close of the market on Friday the stocks to watch in the coming week are AMG Packaging that fell back sharply in the past week and is on IC Insiders top 5 junior market buys, Blue Power with limited supply. Cargo Handlers still in demand with the announcement of the 10 to 1 stock split and with the bid at $87.05 versus the last sale of $86.10. Caribbean Cream with limited supply and increased buying, Honey Bun with good demand and declining supply, but the price could be heavy with a PE of 17. The 2016 fiscal year ends this month, so investors may want to focus on the 2017 numbers as the main reason for buying. ISP Finance with no supply but with bid at $6.50 compared to last sale of $6 and with the success of the $150 million bond issue, could move if some supply appear.
Scotiabank with profit up 47% for the July quarter the stock could be very active this week.
Main market activity has been fluid, there are no indications from Friday’s trading, that there will be much change. Investors should keep an eye on Barita Investments, IC Insider’s Top stock in the main market, with bids at $3.51 at the close on Friday, compared with a last sale price of $3.25. There are currently only 5 offers on the board, amounting to 70,000 units and Scotia Group that is set to report earnings for 2016 in the region of $4 per share, after reporting a 47 percent jump in the July quarter. Investors may want to keep an eye out for Cable & Wireless that could well report decent profit for the 12 months to March next year. Note the company’s year end is set to change to December.
10 Stocks to avoid now
Junior market stocks gained 27 percent for the year to date but those in the main market have gone up just 6 percent over the same time. Seven stocks in the junior market have more than doubled two gained just over 90 percent and one over 80 percent.
 In contrast the main market highest gain is at 93 percent followed by 64 percent. The above data points to the need for selective investment decision making to get the best out of investing in the stock market. Last week IC Insider started a list of top 5 stocks in the main and junior market. This week we introduce a list of the top 5 stocks to avoid at this time as some seems fully valued based on appreciation recently or in some cases the companies are not performing well. The list will be reviewed weekly and updates published. Even these stocks appreciate in the medium term they are likely to lag gains in the overall market.
The top 5 major & junior stocks
Barita is the top IC Insider’s stock for growth over the next 12 months in the main market.
IC Insider starts a new feature that highlights the top 5 stocks IC Insider’s selection for gains over the next several months based on the latest earnings forecast for the current fiscal year for each company.Investors should bear in mind that companies with September year ends will have a head start on companies with later ending period as the earlier year end will result in two sets of results between now and early 2017, thus giving investors an early look into what 2017 earnings will look like. The stocks in the list may surprise many but detailed look at their financials paint a far better picture than the stock prices may currently be telling. These stocks are selling well below the market average and even more so against their potential.
 The two stocks at the top of both listing may surprise many, but they should not. In the case of Medical Disposables revenues are growing close to 50 percent increase as new products are added, this growth is expected to boost gross profit at levels that should out pace increase in cost. Barita Investments is undergoing change and this has driven up fee income sharply which is replacing interest income formerly generated form the repo business. Barita has built up a large pool of unrealized gain on investments which can be released to profit for 2016.
The list is likely to be updated on a weekly basis which is likely to see stocks being added or removed on an ongoing basis.
BUY RATED top Carib markets with 830%

The JSE stock racked up huge gains in 2015
IC BUY RATED stocks were top of the Caribbean markets in Jamaica and Trinidad and Tobago for 2015, with Jamaica Stock Exchange share, chalking up a massive gain of 830 percent since IC Insider elevated it to BUY RATED status.Caribbean Cement followed with gains of 640 percent, Caribbean Cream with 444 percent and Trinidad Cement with a 299 percent increase on the Trinidad market.
While it was easy to make money in Jamaica, with profits rising and interest rates falling, developments in Trinidad went in the opposite direction, with interest rates rising and profits under pressure with the economy ended in recession.
At the beginning of 2015 of the 14 junior market selections, few recorded gains and only Knutsford Express with a 17 percent increase reflecting any meaningful positive movement. Losses were large, with AMG Packaging down 39 percent, Blue Power 31 percent, Caribbean Cream 23 percent, Jamaica Teas 28 percent, Lasco Financial 37 percent and Lasco Manufacturing 32 percent. What a difference a year can make? By the end of 2015, gains were all over the place with the list having 17 companies with two being dropped. There were no losing stocks in the list that had a new addition, tTech which could be listed this week. Honey Bun was added to the listing in November and gained 9 percent since. Eight stocks have more than doubled, four gained 40 percent to 91 percent. Caribbean Cream jumped 292 percent to be the top selection in this market, followed by Lasco Distributors up 274 percent. Blue Power was removed from the list in July with a small gain.
In the JSE main market, at the start of 2015, Hardware and Lumber was the best performing stock with gains of 62 percent followed by Cable & Wireless with 47 percent and Jamaica Broilers had the worst performance with a loss of 24 percent. In all, 7 of the 15 selections were lower than at the time they were BUY RATED.
By year-end, all selections in the JSE main market were up, with Scotia Investments having a mere 15 percent increase, being the poorest performer. This stock is being moved to Market Watch as the 2015 profit performance was far too disappointing to warrant buying now, while Hardware and Lumber remains a hold. The rest, present opportunities for continuing profit making. 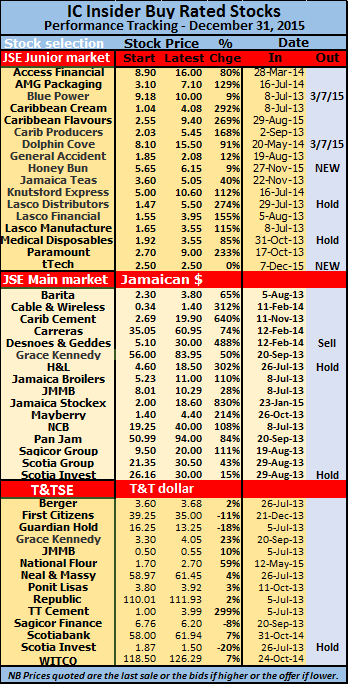 JMMB Group ended with just 28 percent gain, but seems undervalued at the current price. While the list had a few lousy performers, the same can’t be said about a 640 percent gain in Caribbean Cement and 830 percent increase for Jamaica Stock Exchange share. In all, 9 stocks posted gains in excess of 100 percent and 4 below 100 percent but with a 50 percent increase and more.
There were 13 selections in the Trinidad market with Trinidad Cement being the best performer with gains of 150 percent, the next was Point Lisas with 11 percent at the start of 2015. Five stocks suffered losses with the highest being 22 percent and the next 18 percent. For 2015 the price of Trinidad Cement is up 299 percent followed by National Flour with a 59 percent gain.
Looking ahead, the junior stocks should continue to grow, with several of the companies actively expanding resulting in profits climbing at a fast pace. There are a few stocks to be cautious of just now. Lasco Distributors selling at almost 16 times 2016 March earnings. Growth should be strong but unless investors have a long term objective they should be careful buying at current price level, the same applies to Lasco Financial that is selling at 15 times earnings. Dolphin Cove remains a hold at this time.
The Trinidad market needs to be watched at this stage, with the country needing to adjust to the lower price of oil and the recession now being endured.
Barita scores big with 376% winner
Much have changed in the Jamaica stock market since September. All the JSE indices hit new record highs during the October. In September a listing of three sets of stock recommendations were reported on.
 With October now ended, IC Insider updated the chart to see how well each selector did. We let the readers make their own judgement. Bear in mind that only one month has so far elapsed. Suffice to say, Barita Investment scored big with their Desnoes & Geddes selection, with a gain on of 376 percent to record the biggest gain by far. IC Insider would place a hold on any buying of Cable & Wireless at this stage with the big run up in the price recently and would be cautious on Lasco Manufacturing at current prices although the stock has strong long term growth potential.
Note that the PE ratios in the table was the ratio at the time of selection, with prices having changed the current PE will have mostly moved upwards.
Stacking up Barita’s stock recommendations?
Pan Jam is the top selection
“Many are trading at attractive levels with trading ratios of 6-8 times price to earnings, creating a potentially good entry point in the long term, we favour companies with strategic plans to diversify their revenue streams outside of our local economy along with a return on equity that outpaces inflation”, the Barita Investments stock market outlook went on to state. Barita also states that their analysis of 10 years of price data for a number of stocks show that October, to January is the strongest period for the JSE as such, buying before that time is a wise strategy. Those findings coincides with the IC Insider’s research that shows the market predominantly, starts rallying around June to July most years and peaks in mid-May the following year.
IC Insider picked 10 stocks from Mayberry Investments’ daily recommendations along with their PE ratios to see how they matched up with that of Barita’s and listed IC Insider’s top buys as well. Barita’s recommendation report was dated September 11 while Mayberry’s recommendations were published between the September 11 and 18. Barita did not state the PE ratio for their selections but quoted prices, presumable to buy or sell at. A number of the sell recommendation stocks have risen in price since.
 IC Insider picked 11 stocks from Mayberry Investments’ daily recommendations along with their PE ratios to see how they matched up with that of Barita’s and listed IC Insider’s top buys as well. Barita’s recommendation report was dated September 11 while Mayberry’s recommendations were published between the September 11 and 18. Barita did not state the PE ratio for their selections but quoted prices, presumable to buy at. Based on feed-back obtained from Sean Taylor, Business Development Manager at Barita, what appeared to be sell recommendations, were in fact a part of the listing of stocks to buy.One selection Pan Jamaican is common to all three while 5 stocks are picked by 2 of the 3 these are National Commercial Bank, Caribbean Cream, Caribbean Flavours, Paramount Trading and Supreme Ventures.
Derrimon Trading pumps up profit
 Derrimon Trading made major stride in improving performance in the year to June with a big surge in profit of $51 million for the six months, a $49.5 million increase over the corresponding period in 2014, with net profit of just $1.7 million. For the quarter to June, profit came in at $31 million versus a loss of $9.4 million, from revenues of $1.58 billion, 16 percent up from $1.35 billion generated in 2014.
The profit out turn for the quarter is 49.6 percent ahead of the profit generated in the first quarter. Earnings per share amount to 11 cents for the quarter and 19 cents for the half year and should ends up around 40 cents for the full year. For the year to December 2014 the company made profit of $51.6 million or 19 cents per share.
The six months results reflect revenue of $2.88 billion, an increase 6.3 percent to $171.47 million over the $2.707 billion reported for the first six months period in 2014. “The growth in revenue was primarily due to improved sales within the retail segment of the business. Gross profit reported for the period was $360 million or 36.2 percent above the $264 million reported for the same period in 2014, the improvement reported in gross profit is due to improved margins within both the distribution & retail segments of the business,” Derrick Cotterell, Chairman and Chief Executive Officer stated in his report to shareholders. For the June quarter gross profit jumped a strong 59.5 percent to $193 million and is well ahead of the 16 percent growth in revenues for the quarter.
 Operating expenses for the period was $298 million, which represents an increase of 11.9 percent or $32 million over the $266 million reported for the same period in 2014. For the June quarte, expenses rose 14 percent to $157 million from $137.6 million. “The major factors for this increase were the increase in cost for property rental, staff cost, contracted services such as trucking, and professional fees,” Cotterell stated. Finance charges increased from $21.3 million to $40.4 million or 90 percent in the six months period reported. For the quarter, interest cost amounts to $21.5 million versus $6.4 million. Associated company contributed $12 million in the quarter and $20.5 million for the half year to profit.
Finances| While the profit performance is up strongly, the same cannot be said about the company’s finances. Receivables stood at $495 million at the end of 2014, climbed to $881 million in June and inventories are up to $817 million from $604 million, payables of $1.06 billion moved from $599 million. Loan payments due within twelve months, amount to $338 million. With cash of $137 million on hand and cash flow running around $70 million per annum, the company may have to be going back to the financial market to seek funding to facilitate payment of the loans, but reduction in the amounts due from customers and inventories can deliver the cash to help fund the payments.
IC Insider is placing a Market Watch rating on the stock.
Big new income stream for JSE
 The Jamaica Stock Exchange is to receive another big shot in the arm, with a totally new source of income flowing from the decision of the Financial Services Commission that all retail repurchase agreements, must migrate to the Jamaica Central Securities Depository Trustees Services (JCSD) effective 31st of August.The total book of repurchase agreements amounts to approximately $500 billion as of March this year, the amount to be transferred may be lower has the FSC new regulations require that the minimum amount for a retail repo that is now J$500,000 and US$5,000 and is scheduled to be increased on a phased basis to $1 million and US$10,000 by December 31, this year.
Based on the fee structure the JCSD should earn around $50 million a year in fees from the securities supporting the repos. There will also be fees to be paid for each repo transaction, such transactions will be evidenced by an account held in the purchasers name at the JCSD. According to Robin Levy, Manager of the JCSD they will be trustees for the assets that back the repos, as such the dealers will no longer hold them directly in their name thus legally separating the ownership from the repo issuer during the duration of the repo agreement.
 The stock exchange group will earn an annual fee for each dealer who is registered to deal in Repo securities by the JCSD. The fee structure listed on the Jamaica Stock Exchange has the annual fee at $100,000 with 20 dealers in the country the income from this source will be small only around $2 million per year if all of them sign on. The repo registration fee is likely to be the big income generator as each transaction will incur a fee based on its value.
The JSE enjoyed a very good first quarter this year with huge increase in income, a fare bit coming from one off type transactions but in addition increased trading activities flowing from increase trading levels on the JSE this year contributed to improved profits for the year to date. The JSE stock last traded at $6.23 on the JSE on Friday to gain over 300 percent for the year to date, but with earnings per share now looking like heading towards $1.50 level there is room for another surge forward for the stock. The company’s 2015 second quarter numbers should be out this week based on the released of the June 2014 quarter results on the July 23, last year.