 Trinidad’sFirst Citizens Bank reported profit of $773 million before taxation for the year to September compared to $745 million in 2013. Profit after tax, amounted to $627 million in 2014, up 2.9 percent over the profit of $609 million of 2013.
For the October 2014 quarter pre-tax profit rose 9 percent over 2013 to reach $180 million from $165 million but profit after tax for the quarter was virtually flat at $149 million versus $145 million in 2013. The information was included in an abridged version of the bank’s results for 2014.
Citizens had assets of $34.9 billion at the end of September marginally down from the $35 million at the end of June. Since June customer deposits fell from $26.5 billion to $25.7 billion. The bank did not report details on loans at September. At the end of June this year, there was no growth in this asset which stood at $13.75 billion, slightly down on the amount at September 2013 and is hardly likely to have changed much since with flat assets.
Earnings per share amounted to $2.50 for 2014. The stock remains on the Buy Rated list with earnings per share of $2.75 projected for 2015 and a target price in the around $45.
A final dividend of 61 cents per share payable in December was declared, and it brings the total for the year to $1.18, up from $1.09 per share paid as the final dividend for the 2013, the amount was paid in January 2014.
The dividend policy of the Citizens is to distribute to its ordinary shareholders funds surplus to the operating capital and strategic requirements of the Group, as determined by the Directors, with an annual target dividend pay-out percentage range of 45 to 55 percent of net profit after-tax.
The company was listed on the Trinidad and Tobago Stock Exchange in September 2013, after a successful public share issue.
First Citizens 2014 profit up slightly
Profit climbs 21% at Margaritaville
 Revenue jumps 30.7 percent to US$1.7 million, in the first quarter, ending August and pushed up gross profit by 33.24 percent to hit US$1.267 million, as margin improved over the similar quarter in 2013, at Margaritaville Turks Ltd. It was not all good sailing for the second US dollar listed stock on the Jamaica Stock Exchange, as administrative cost climbed faster that revenues at 37.76 percent, and kept growth in profit to US$245,000, for a 21.18 percent increase.
Full year profit| For the current year, based on the growth in revenues so far, profits should climb to US$1.6 million, up from US$732,000 in twelve months to May this year and result in earnings per share of 2.4 US cents and put the PE of the stock at 4.6 making it an attractive buy currently. The standalone business depending on ships docking is not without added risk, a factor that investors should be cognizant of. The shares are not in great supply but there are offers ranging from 11 US cents to 18 cents but there has been no buying interest for weeks.
Construction of a new restaurant, is to commence in the second quarter of the financial year and end in the third quarter, to expand their offerings to customers.
Concerns| The company has little debt, but has a big jump in the amounts owing to creditors, growing from $716,000 to $973,000 while amounts owing by related companies to it, jumped sharply, from $424,000 to $987,000. This is not a good sign and there is not even an ounce of comment by management about this unusual buildup of these amounts. While all of this is happening, cash is down to only $4,000 from $58,000 a year ago.
Margaritaville is new to listing on the stock exchange, but they need to get a few things right. The prospectus stated that the shares would be listed on the stock exchange main market, the audited statement for 2014 says the same, and the current report repeats it as well. These are all incorrect as the shares are listed on the US dollar denominated market, which differs from the main market. The actual financial statement does not provide readers with the number of shares issued, this should be a part of the financial statement. The listing of the number of shares issued in the top 10 shareholders is not a part of the financials and investors should not have to look there for it.
Berger surges to the top
 Berger Paints surged to the top of the list of stocks on the Trinidad & Tobago Stock Exchange that should return the highest gains to investors, in the months ahead, with the potential to reach 500 percent.
Next in line is Trinidad Cement with 300 percent. Scotiabank has fallen to $58 from a high of $73.12 earlier this year. At the close of trading for the week, Scotiabank’s price seems set to decline further, with selling pressure still overwhelming buying interest, at the current price level. The decline so far has put the stock back in the list of top buys, with potential gain of 40 percent at the last traded price. The bank reported poor results in the first half of the fiscal year, but showed strong gains in the July quarter including good pick up in loans. This suggest that 2015 earnings should move up attractively, subject to continued growth in the loan portfolio. Importantly the PE has fallen in line with Republic Bank at around 16 times earnings and only slightly above the rest. Berger has surged based on the latest results, putting profit for the six months to September at $1.122 million, a big improvement over than the $240,000 earned in the 2013 period and almost ensuring that the full year’s earnings of $2.93 million to March this year, will be bettered by a good degree.  Berger’s profit improvement is flowing from reduced cost rather than sales growth. Sales fell slightly to $29.8 million for the half year, compared to $30.1 million in the 2013 period. IC Insider is forecasting $1.10 per share, around $6 million after tax for the current year.
Rounding out the top list of the stocks that virtually select themselves are, Sagicor Financial, Point Lisas, Guardian Holdings, National Flour Mills, Massy Holdings, First Citizens Bank, Ansa Merchant Bank, Republic Bank and Scotiabank.
The 2014 financial year for a number of the companies have ended in September, with more results to be released soon. Investors’ minds will start to focus on 2015 when the results for some of the companies will show improvement over 2014, making the stocks cheaper now than they are likely to be a few months from now when the results for 2015 starts to flow.
Trinidad Cement released their nine months results to September which point to earnings from continuing operations being 13 cents for the quarter and annualised at 52 cents per share. The agreement to supply Venezuela with 240,000 tonnes of clinker will help boost the group’s profit, while the contract is being satisfied. While debt is a negative, the present cash flow if continued, will see them out of danger within 3-4 years.
Overall the TTSE market average PE is at 14.4 with 12 stocks above this levels and 10 stocks below.
Price increase to push Witco 2015 profit
 Trinidad’s West Indian Tobacco (Witco) raised prices on cigarettes approximately 15 percent, effective October. The increase should push revenues to over $1.3 billion dollars in 2015, from TT$1.185 billion in 2013.
An increase of that level on top of one in 2013 will most likely reduce the volume of sales on the Trinidad market, where the increase was effected. The price adjustment should help boost next year’s profit and by our calculation that should hit $700 million after tax or around $6.80 per share. That would put the PE ratio of the stocks at just over 17 times next year’s earnings and should help move the stock back into the $20 region which should be helped with an expected increase in dividends in the region of the EPS.
Witco’s profit jumped 23.5 percent in the June quarter, this year to hit $127 million as revenues climbed by a smaller 15 percent, to $324 million. For the six months to June, profit is up to $224 million from $188 million, a 19 percent spurt, from revenues of $590 million versus $556 million in 2013. Earnings per share came in at $1.50 for the quarter and $2.65 for the half year. Earnings for the full year to December should reach $5.70 per share.
What’s up with Grace’s stock?
 At the close of trading on Monday, there were two lots of Grace’s stock on offer on the Jamaican Stock Market, 9,360 units at $63 and 200,000 at $65.
Over at the Trinidad Stock Exchange, the bid on the stock was the same as the last sale price, at TT$3.55 which equates to J$63, but only for 886 units. There was an offer to sell 12,300 units at TT$3.70 or J$65.50. Could the stock be set to jump? Probably.
Grace has been in the news recently with rise of 21 percent in profit for the six months to June and the purchase of a USA trading operation, La Fe Foods with revenues of US$80 million per annum, that should add nearly $9 billion to revenues in a full year.
Grace expects much benefit to flow from this acquisition, as La Fe Foods services the Hispanic market with a large population that should allow some of Grace’s branded products to find new markets. In addition, the acquisition will allow some products with inadequate margins, to be sold to a non-related distributor, to be exported by Grace to the USA market.
Paramount’s Q4 profit jumps 108%
Paramount Trading’s profit after tax jumps 108 percent in the May quarter, on a pretax basis, it was up 73 percent while revenues came in at just 5 percent higher, for the quarter.
 Profit in the May quarter after tax is $43.6 million compared with $21 million for the similar 2013 period. The improved results for the company’s final fiscal quarter, came from revenues of $199 million versus $189.6 million in 2013. The final quarter numbers are a marked improvement over those for the February quarter, when only $14.6 million in profit was reported form sales of $181 million. For the full year, Revenues amounted to $720 million from $682 million in 2013. The 2013 numbers were boosted by one off income from the amalgamation of the trucking operation – Stamina Trucking and cancelation of related party debt amounting to $21 million, this also swelled the profit by a similar amount. In 2013 the Paramount incurred taxes on profit amounting to $10 million but in 2014 there was a tax credit of $425,000.
Noticeable, was a fall in administrative cost, from $35 million in the February quarter, to only $23 million in the final quarter. Gross profit margin climbed in the three months to May to 50 percent from 49 percent in the February quarter, compared to 47.7 percent for the full 12 months. The improvement in the profit margin is a welcoming development, especially as sales have not been growing at a fast pace.
Profit is projected to come in around $125 million in 2014/15 year or around 80 cents per share from current operations. At the current price of $2.70 the stock would be priced at a PE of only 3.4 making it a buy bearing in mind that that many junior listings have been valued around 8 times earnings.
Financials| The company earned an average rate of return of 29.7 percent, on the equity of $345 million at the end of May. Borrowed funds amounted to only $52 million compared to the level of equity. Cash stands at $56 million while receivables climbed to $172 million from $146 million, a much faster pace than the increase in sales. Inventory is at $203 million and increase form $172 million at May 2013, but payables moved up from $110 million to $128 million over the same period. Inventory levels may be on the high side as a protection against the devaluation of the Jamaican dollar, the same would not be true for the increased receivables.
One Caribbean jumps to $25 – a hold
 One Caribbean is no longer a recommended Buy Rated currently based on the jump to $25 per share this week, but seems to be a hold based on the reading of the Trinidad Stock market where it looks as if it should rise some more.
Since July 5 last year when IC Insider gave the stock in the Buy Rated category it has moved up 43 percent and now enjoys a PE ratio of 17.7 compared with 12.6 last year July.
 Elsewhere Trinidad Cement slipped to $1.90 making it more attractive, even as there is talk of major changes in directorship. Massy Group continues its slow gain as well as Republic Bank but they as well as a number of others remain attractively priced for good gains in the period ahead as they are undervalued.
Why PE?| The price earnings ratio is the most popular measure investors use to compare and determine stocks values. It is computed by dividing the price of a stock by the earnings per share. It allows investors to compare the value of one company with others, in order to determine which ones are to be bought, sold or held. When the market moves markedly away from the norm it is usually time for investors to move, the PE ratio is a good tool to measure such extremes.
In looking at good buying opportunities the crude measure is to buy those stocks with low PEs compared to the market or to stocks in the same sector.
First Citizens PE more attractive
First Citizens made the sharpest price movement during the week as it dropped back sharply, ending back at $35 compared with $37.43 at the end of the previous week. The fall has raised the attractiveness of the stock giving it a 70 percent potential gain.  Elsewhere not mush change took place more, but a number of stocks continue to post higher highs during the week as they eke away at the potential gains they have been showing. The Trinidad market has several stocks that are priced at a PE that is well below the market average, this has been so from early 2013 and continues to present.
 The market has 6 stocks that are priced at a PEs that are well below the market’s average of 15, and a few close to the average, thus offering profitable investment opportunities for investors with medium term investment horizon.

The price earnings ratio| The PE ratio is the most popular measure investors use to compare and determine stocks values. It is computed by dividing the price of a stock by the earnings per share. It allows investors to compare the value of one company with others in order to decide which ones are to be bought sold or held on to. When the market moves markedly away from the norm it is usually time for investors to move. Nowhere is this truer than PE ratios.
In looking at good buying opportunities the crude measure is to buy those stocks with low PEs compared to the market or to stocks in the same sector.
Why NCB deserves a look now
 National Commercial Bank (NCB)shares may not be trading in droves recently with the price tending to trade around $17 since early May but investors may be missing a great buying opportunity with a stock that is seriously undervalued.
In Trinidad the stock closed as low as TT$1.04 recently but has moved up to $1.10 on Friday and seems poised to go higher. The bid in Trinidad on Friday close was $1.10 (J$19.20) to buy 22,933 units with an offer of 26,000 units at $1.14. On Wednesday the stock traded 69,456 units at $1.08 and gained 2 cents in the process. On Friday 21,322 traded in Jamaica at $18.01 each and 1,396,013 on Thursday between $17 and $18.03. Wednesday saw 21,595 units being traded between $17.30 and $19. One important factor is that the stock is not in great supply.
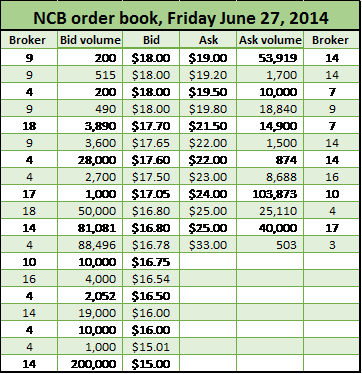 But it’s the order book on the Jamaica Stock exchange that is sending a strong message to buy coupled with is a year when the results should help stimulate the stock price higher. There are only 280,000 shares on offer in the market but the buying interest is not particularly strong. With the pickup in trading in Trinidad, the price in Jamaica could get a lift and with third quarter results to June which are due in the last week in July, that could strengthen investor’s appetite for the stock and give it a badly need push.
IC Insider forecast earnings of $5 per share for the current year, so far NCB reported earnings of $2.38. For the first 6 months of the fiscal year.
Lasco shares sell & buy FX or hold
Our response back then, thanks for your enquiry. As you will see our BUY RATED list contains these three stocks. Here are our views. First off the local stock market tends to go down around May until last June or July. This is not cast in stone, just a tendency. One reason for it is that investors get the full information as to what companies did last fiscal year and a glimpse for the new-year. In the case of the three Lasco companies they have just reported their full year results. The distributorship earning is the most encouraging of the three and looks like it will probably do better than the other three in the short to medium term. It will also benefit from the Salada Foods distribution which started this year, as well as from increased production to come from the expanded Lasco Manufacturing Company’s operation. The information suggest that the next set of results should possibly show growth over that of 2013.
Lasco Financial seems poised for good things but big marketing spend last fiscal year kept profits down as they went for more market share. It does look as if they will be spending on the world cup promotions which could build business, but may also keep profits pressured somewhat for a while.
Lasco Manufacturing seems cheap at $1 bearing in mind the impact that the factory expansion is likely to have on both sales and profits ultimately. Short term they will have to pick up interest cost and depreciation on the completed factory but will enjoy cost savings and ultimately increased profits.
It is my view that the market overall, is undervalued but investors will need to be patient and the payoff is likely to huge for those who wait, the gains to be reaped elsewhere is not likely to be all that great, to cause one to jump and possibly miss the gains in the local market that is ahead.