TransJamaican Highway 36% oversubscribed


The public issue of 1.75 billion shares in TransJamaican Highway by the government of Jamaica was oversubscribed with the offer attracting 22,000 applicants amounting to $12 billion, the Prime Minister of Jamaica disclosed in his budget presentation today.

The initial offer was increased to 2.45 billion units by an additional 750 million shares with a total consideration of $8.82 billion and resulted in a 36 percent oversubscription.
The result is that over $3 billion will be available to come into the secondary market when refunds are made.
Since the opening of the public issue, Transjamaican announced a dividend of 12.58 cents payable in April, while the stock closed trading today at $4.17.
Scotia profit surges 35%


Profits jumped a solid 34.5 percent at Scotia Group with $4.2 billion in net profit for the quarter that ended January, this year, for an increase of $1.1 billion over the $3.21 billion in 2024, with earnings per share rising to $1.35 from $1 in 2024.

Total revenues excluding expected credit losses for the year ended January 31, 2025, grew by $2.2 billion to $17 billion, for an increase of 14.9 percent over the prior year period, primarily driven by growth in loans leading to an increase in net interest income of $1.1 billion or 10 percent as well as an increase in other revenue of 26.2 percent.
Other income, other than interest income, increased by $1.2 billion or 26.2 percent. Net fee and commission income for the period amounted to $2.2 billion. an increase of $672 million or 42.9 percent, primarily driven by the higher volume of client transactions and activities.
Total loans increased from $275.7 billion to $313 billion, an increase of 13.3 percent over the $276 billion in January 2024 but flat with October last year. Growth over January 2024 “includes a 12 percent increase in Scotia Plan personal loans and a 24 percent increase in mortgage loans. Commercial loans also increased by 5 percent over the prior year period,” the release from Scotiabank stated
The Board of Directors approved a dividend of 45 cents per share for the first quarter, payable on April 17, to stockholders on record at March 26.

Omni Industries shows promise but..


Omni Industries, the first company listed on the Junior Market of the Jamaica Stock Exchange in 2024, reported results for the nine months to September, with the first full quarter after the IPO offer in May. The result for the quarter is promising, with pre-tax profit moving from $32 million to $38 million and after tax from $24 million to $38 million with the listing resulting in no taxes payable for another 5 years on profits, since listing on the Junior Market.
 

For the 9 months to September, earnings before tax amounted to $184 million and after the provision of $38 million corporate profit tax, ended with a net profit of $146 million. Based on the average number of shares outstanding, earnings per share ended at 6 cents instead of the 10.4 cents reported by the company and 1.5 cents for the September quarter instead of the reported 2.7 cents per share that was based on the 1.4 billion shares instead of approximately 2.375 billion units. For the year to December the company used the same number of shares as they used for the September results to compute per share earnings and provided no EP for 2023. Instead of EPS of a loss of 1.8 cents for the December quarter and 8.6 cents for the full year, earnings per share are actually a loss of 1-.4 cents for the last quarter with 2023 being 7 cents and 5 cents for the full year with 2023 being 6.7 cents.
The performance achieved with the Gross profit margin climbing is probably the most telling feature of the results if it is sustainable. Margins surged in the third quarter from 37 percent in 2023 to more than 50 percent in 2024, pushing the nine months to September to 47.4 percent from 37.5 percent in 2023. Unfortunately, this performance was not carried into the final quarter in December with the margin dropping to 38 percent down from 45 percent in 2023 and helped in plunging the company into a loss in the final 0224 quarter of $25 million versus a loss before tax in 2023 of $21 million, with the full year profit coming in at $135 million before tax versus $180 million in 2023.
Revenues declined by 12 percent to $427.5 million for the three months to September 2024, compared to $488 million in the same period in 2023. Revenues declined marginally, to $1.51 billion for the nine months in 2024 from $1.57 billion in 2023. The decline is “largely attributed  to adverse weather conditions, including Hurricane Beryl in early July and ongoing heavy rains impacting the island. Additionally, a cement shortage has affected the construction industry, which directly impacted our revenue streams,” the company managing director, Patrick Kumst informed shareholders in his commentary on the results.
Administrative costs rose by a third from $60 million to $80.4 million for the quarter and up 43 percent from $162 million to $230 million for the nine months. Selling expenses jumped by 30 percent for the quarter to $33.5 million from $26 million in 2023 and for the year to September, it increased by 16 percent to $111.5 million from $70 million in 2023. For the reporting quarter factory expenses rose by 10 percent to $56 million, from $51 million and increased by 9 percent to $163 million for the nine months to September from $150 million in the 2023 period.

The managing director went on to state, “this rise in administrative costs was primarily due to higher professional fees, marketing, and other expenses related to our IPO. Selling expenses year‐to‐date were driven mainly by haulage and export-related costs, while the 9 percent increase in factory expenses resulted from increased repair and maintenance costs. With our ongoing strategic retooling and new equipment acquisitions, we anticipate a reduction and improved optimization of these expenses in the near term. Finance costs for the quarter totalled $9.8 million, reflecting a 20 percent decrease compared to the same period in 2023. Year‐to‐date finance costs amounted to $29 million, a 32 percent reduction from the prior year. This decrease primarily stems from the company’s proactive debt reduction efforts, resulting in lower interest expenses for the period.”
“Retooling process has commenced, and the additional capital raised post‐IPO will be utilized to acquire further equipment. Currently, we are in the negotiation phase with suppliers, and one machine has already been commissioned as of September 2024.”
The operations generated gross cash flows of $211 million, with increased working capital consuming it, leaving a cash deficit of $153 million before capital spend of $67 million. After accounting for $239 million from the IPO the company ended with a cash flow deficit of $50 million and a reduction of funds on hand to $62 million. Loans net of new funding amounting to $40 million were repaid and a dividend of $24 million was paid out before the IPO.
Current assets ended the period at $1.2 billion, including trade and other receivables of $469 million, inventories of $661 million cash and bank balances of $61 million. Current liabilities amount to $432 million. Net current assets ended the period at $513 million.
The company ended with Shareholders’ equity of $946 million and long term borrowings at $312 million and no short term loans. Net asset value ended the period at $0.38 with the stock selling at 2.8 times book value, compared to the Junior Market average of 1.8.
Another error in the quarterly report is that the share capital is still being stated as $20.09 million in the statement of changes in equity but that has been increased by $250 million new shares that were issued in the IPO, as such the caption headed share capital should reflect the change but it is not. The company should seek the advice of a knowledgeable accountant to get the presentation and computation right as they clearly don’t have that in house.

Paul Scott set for 8 JSE listings


Another Paul Scott’s company is headed to the Junior Market and will bring the total companies listed to 9, these include Seprod, Caribbean Producers, General Accident, AS Brydens and Sons, Eppley, Epply Caribbean Property Fund, Productivity Business Solutions and Stanley Motta. Scott also has a significant interest in Lumber Depot and Transjamaican Highway in which Musson owns over 595 million shares and is the third largest shareholder.

Atlantic Hardware & Plumbing Company, a 30-year-old wholesale distribution company is offering 499,999,800 shares at $1 each for subscription. Just 200 million will be available to the public as JMMB Group is set to convert loans into shares. The shares are slated to be listed on the Junior Market of the Jamaica Stock Exchange. The company with a staff complement of 35 is located at 105-107 Marcus Garvey Drive.  The issued share capital is currently 1.95 billion ordinary units. Construct Group owns 975 million units, Lumber Depot 682.5 million units and General Accident 292.5 million shares.  The offer opens on the 27th of February and is scheduled to close on the 13th of March and will most likely close well ahead of the closing date, with only 100 million available for the general public.
The lead broker is JMMB Securities, an affiliate, the holder of a convertible bond, is entitled to exercise the conversion option for up to 300 million shares at $1 per share.
The net proceeds of $470 million will be used to repay debt, this includes the conversion of JMMB convertible bond representing 300 million units.
At the end of September last year borrowed funds surged to $1.34 billion compared to just $177 million at the end of 2023 as the company embarked on a share buyback, in a classic engineering exercise to get it to fit into the Junior Market capital size.

Revenues in 2023 amounted to $1.4 billion with a profit of $147 million before tax. Revenues declined from the 2021 and 2022 levels of $1.67 billion with profit before tax of $318 million and $290 million respectively.  Revenues of $440 million were generated in the September quarter up 30 percent from $339 million in 2023 and for the nine months to September, revenues climbed by 12 percent to $1.23 billion from $1.1 billion in 2023. Profit for the quarter before taxation was $18.7 million versus $69 million and for the year to September 2024 – $84 million compared with $236 million in 2023.
In January, this year, Atlantic sold real property on Ashenheim Road in Kingston. The net sale proceeds will be used to repay approximately $230 million of existing indebtedness. Borrowed funds should fall to around $200 million from the combination of the IPO proceeds and internal funds. Accordingly, interest cost that was $48 million in the September quarter should drop around $20 million annually.
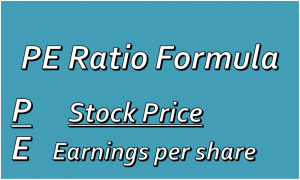
The PE ratio works out at 12.5 times earnings which is unlikely to move the stock much with the market average currently around 13 but there several that are trading above 15. This is not one those companies that has a great future ahead of it and most investors should look elsewhere for better prospects.

One Great Studio buys media company

One Great Studio a Junior Listed company announces a strategic acquisition of the business of DRT Communications, a leading public relations and media intelligence firm, for a total consideration of J$115 million, which includes a J$35 million performance-based earnout over 3 years.

Djuvane Browne, Managing Director

Danielle Terrelonge is the Managing Director and Chief Storyteller at DRT Communications, a “fully equipped marketing communications agency.” “The team is equipped to plan and execute public relations campaigns, develop content for electronic, print mediums, and websites, and manage communications projects from concept to completion,” the company states on its Linkedin site and engages between 11-50 employees.

The acquisition is in line with the company’s CEO Djuvane Browne’s objective of acquiring an advertising firm to compliment the advertisement placement of One Great Studio.

According to One Great Studio, “we’re digital natives with deep knowledge of design, technology & business. We help you generate more leads & make more sales with digital marketing, websites, web applications & mobile applications.

Acquisition doubles ISP Finance


Micro financier, ISP Financial Services has more than doubled its size by acquiring the principal balance of a loan portfolio of approximately $1.2 billion. The acquisition more than doubles the company’s loan portfolio of just over $1 billion at the end of September last year net of provision for loan losses, pushing it to $2.2 billion.

The terms of the acquisition were not stated in the release by ISP at the close of the day on Wednesday but ICInsider.com has been reliably informed that the acquisition took place using a combination of internal and external funding which a portion of the principal deferred to be paid at some time in the future.

Last year’s annual general meeting scheduled to be held on November 21, 2024, was postponed until January, this targeted date has been pushed back, but no doubt will be held drown about March or April. The portfolio is acquired from a large Jamaican owned banking group. ISP had stated in 2021 that they were in discussions to acquire a portion of the loan portfolio of Micro lender, Mundo Finance but that deal was never materialized.
The current acquisition is likely to double revenues that stood at $520 million in 2023 and were 9 percent higher for the nine months to September last year to $400 million with $118 million generated in the September quarter. The acquisition could push profits sharply higher and also with the benefit of economies of scale. Profit for the nine months last year was up 66 percent to $55 million. IC Insider.com estimates that profits could exceed $2 per share or more in a full year of operation if all goes well.

At the end of September 2024, ISP equity capital was $641 million, with borrowings of $520 million. This recent acquisition stretched the capital base considerably with the debt to capital ratio out of line with acceptable levels, accordingly, ICInsider.com expects the company at the upcoming annual general meeting to have shareholders approve an increase in the share capital with the possibility that the stock could be split ahead of a likely return to the capital market to raise fresh equity capital to needed to normalize the capital base and to fund growth in the loan portfolio.

Omni Industries overstates profit per share

Omni Industries reported incorrect earnings per share for the year to September and for the third quarter with the report with the errors remaining on the Jamaica Stock Exchange to date.

Last year May 250 million new shares were offered to the public, effectively increasing the total issued shares to 2.5 billion units. In a strange twist, the company reported an average number of shares at just 1.402 billion units, far less than the amounts originally issued, instead of approximately 2.376 billion. Accounting standards require that the average number of shares in issue is the weighted number of shares outstanding during the period. The company split the 20.9 million shares before the IPO into 2.25 billion. The effective number of shares from the beginning of January is total after the split, of 2.25 billion.  The 250 million new shares issued in May are to be taken together with the 2.25 billion units to compute the weighted average share issued in computing the earnings per share for the year to date and the total issued shares of 2.5 billion are used to compute the EPS for the quarter as there is no average as all 2.5 billion shares were issued before the quarter started.
The effect of the error is that the critically important earnings per share reported in the quarterly are severely overstated. Instead of 2.7 cents for the quarter and 10.4 cents for the nine months, earnings should be 6 cents for the nine months and 1.5 cents for the September quarter.

The company seems to have used the originally stated capital and computed the average based on that. Stock splits or bonuses do not change the equity capital of a company, all they do is to increase the number of issued shares. There is no averaging of the amounts before and after the split as the new shares in issue replaces the original amount. Only freshly issued shares will result in the need for a weighted averaging of the amounts in issue.
Almost three months have elapsed since those results were posted with the glaring error and it still remains on the website of the Jamaica Stock Exchange. This and other issues are reminders that investors are not well served in Jamaica.


Acquisition boosts Mailpac profit


Expansion by acquisition helped push net profit up a robust 66 percent in the third quarter for the Junior Market listed Mailpac, with the bottom line coming in at $114 million from $69 million in 2023. Nine months profits nevertheless declined by 10 percent to $183 million from $203 million in 2023, with revenues climbing a sharp 83 percent in the latest quarter to $732 million from $400 million in the prior year and 43 percent from $1.2 billion for the Nine months to September 2023 to $1.72 billion to September 2024.

Cost of sales jumped 81 percent to $363.7 million in the 2024 third quarter from $200.8 million in 2023 and increased 46.2 percent to $895.5 million from $612.6 million for the nine months to September 2023.
Gross profit climbed 84.7 percent to $368.4 from $199.5 in the September quarter and increased 40 percent to $829 million in 2024 from $592 million for the nine months to September. Gross profit margin improved to 50.3 percent from 49.8 percent in the 2024 third quarter versus 2023 and 48.1 percent for the 2024 year to date from 49.1 percent in 2023.
Selling and Promotion Expenses for the nine months to September 2024 increased by 37 percent to $62.6 million versus $45.7 million to September 2023. For the September quarter, promotional expenses jumped 68.6 percent to $24 million from $14 million in 2023.
Administrative and General Expenses increased 71.3 percent for the nine months to September 2024 to $513 million compared with 2023 at $299 million and for the quarter it climbed 95 percent to $200 million from $103 million in 2023.
Profit before finance costs for the nine months ending September 2024 increased just 2.8 percent to $254 million from $247 million in 2023 and jumped 75 percent to $144 million from $83 million in 2023.
Finance costs jumped 59.5 percent to $71.8 million for the year to September 2024 from $45 million in 2023 and climbed 116 percent to $30 million from $14 million in 2023.
Cash Position rose to $254 million at the end of September 2024 compared to September 2023 at $138 million, helped by inflows from operations of $229 million before dividend payment of $67 million, working and other capital needs. $56 million was added to the $199 million on hand at the end of 2023.
Shareholder’s Equity ended September 2024 at $807.6 million, up from September 2023 of $505.8 million. Equity includes $137 million relating to the acquisition of MyCart Express to be converted to shares as compensation for the acquisition of that operation. The exact conversion will be dependent on the performance of the acquired portfolio, up to March 2025.
Earnings per share for the latest quarter comes in at 5 cents, up from 3 cents last year and 7 cents for the nine months to September 2024 compared with 8 cents in 2023. Importantly, the acquisition and some changes to operations that contributed to increased profit are set to deliver higher profits in the future, accordingly, ICInsider.com projects 2024 earnings at 20 cents per share and 30 cents for 2025 and the company’s management seems optimistic about the immediate future.
“The performance of the third quarter has already started to show the expected results from the investments outlined in previous quarters. To date, we have been able to drive seamless integration of MyCart Express, the newly reorganized management team, and implement technological improvements to cut costs and drive innovation. As we continue to assess the strengths and competencies of the newly formed team and infrastructure, we anticipate significant synergistic benefits, enhanced revenue streams, operational efficiencies and increased shareholder value to result from emerging strategies. We are confident that the Company is strategically positioned for continued growth, industry leadership and sustained success in the evolving e-commerce landscape,” the Directors’ report to shareholders stated.

Scotia a Xmas of goodies in 2025 & beyond

Scotia Group delivered a respectable 17 percent jump in profit to shareholders in the just concluded fiscal year to October. Investors drove the price up a solid 34 percent for the year to date, in addition to dividends amounting to $1.70 as revenues climbed 15.8 percent to $69 billion from $59.6 billion in the October quarter, with profit after tax rising to $20.15 billion from $17.2 billion in 2023. For the October quarter, profit rose a solid 32 percent to $6.16 billion from $4.67 billion in 2023.


The group paid dividends amounting to $5.1 billion during the fiscal year versus $4.2 billion in 2023 a payout ratio of roughly 25 percent of the annual profit. A dividend of 45 cents per share has been declared for payment in January 2025.
Total revenues rose 16.2 percent for the October quarter to $18.4 billion from $15.84 billion in 2023.
B growth in loans the main propeller of increasing profits, climbed 16 percent for the year to $312.76 billion but rose at an annual rate of 22 percent in the second half and 29 percent in the final quarter. With lower interest rates expected in 2025, the demand for loans could grow even faster than in the final quarter, subject to demand and management’s decision to take on increased risk.
Interest Income rose 14.5 percent in the last quarter to $12.64 billion from $11 billion in 2023 and for the year it moved up 18.4 percent to $59.7 billion from $48.34 billion in 2023.
Net interest income rose 15.4 percent to $12 billion in the last quarter of this year, from $10.57 billion in the prior year and for the full year, it jumped 17.4 percent to $46.3 billion from $39.46 billion in the previous year. Net fee and Commission income went from $1.8 billion in the $2.1 billion in October 2024 quarter and increased 17.2 percent from $6.74 billion in the half year in 2023 to $7.23 billion in the current year.
Other income amounted to just $158.6 million in the October 2024 quarter, up from $67 million in the previous year and for the fiscal year, rose 25.5 percent to $661 million from $527 million. Insurance premium income jumped 51 percent to $1 billion for the latest quarter, up from $673 billion in the prior year and for the year to October grew 26 percent from $2.79 billion in 2023 to $3.5 billion.
Net foreign currency activities generated revenues of $2.48 billion up 9.5 percent from $2.27 billion in the comparative period in 2023 and for the year, revenues rose 6.4 percent of $9.3 Billion versus $8.75 billion in 2023.
Credit impairment losses jumped sharply by 71 percent to $1.26 billion in the October quarter from $740 million last year and for the fiscal year, it climbed 73.5 percent to $4.16 billion from $2.4 billion in 2023.
Segment results show third party revenues for Corporate and Commercial banking increasing 11.3 percent to $15.8 billion, with revenues of $14.2 billion in 2023. Net segment results surged 24 percent to $13.7 billion over $11.1 billion in 2023. Treasury segment generated revenues of $15.75 billion up 24 percent from $12.68 billion in 2023 with a profit of $4.86 billion in 2024 up 36 percent compared with $3.57 billion in the previous year. Investment Management Services generated a 1.7 percent growth in revenues of $3.14 billion and net results that rose just 2 percent to $1.77 billion in 2024, with revenues of $3.1 billion in 2023 and net results of $1.73 billion. Insurance Services accounted for revenues of $4.76 billion, up 13 percent over $4.2 billion in 2023 and net results of $4.8 billion up by 24 percent compared with 2023, with revenues of $4.2 billion and profit of $3.9 billion.

Staff cost fell 10 percent in the last quarter to $2.92 billion from $3.24 billion in 2023 and rose 6.3 percent to $11.8 billion in the current year from $11.1 billion last year. Other operating expenses rose 4.2 percent to $3.1 billion in the quarter from $2.99 billion in 2023 and increased 4.6 percent in the year to $13.24 billion from $12.66 billion in the prior year. Tax on assets rose 13 percent to $1.55 from $1.376 billion in 2023. Taxation rose 16 percent to $9.55 billion, for the year from $8.2 billion in 2023.
Customer deposits grew by 7 percent to $479 billion. Shareholders’ equity ended the period at $138.5 billion, up from $126.5 billion at the end of October 2023.
Earnings per share for the quarter amounts to $1.98 and $6.48 for the year. IC Insider.com projects earnings of $9 per share for the 2025 fiscal year, with a PE of 5.8 times the current year’s earnings based on the price of $52 the stock traded at on the Jamaica Stock Exchange. Net asset value ended the period at $44.50 with the stock selling at a low 1.15 times book value.
Scotia Group has the ICInsider.com Buy Rated seal of approval.

Expectations for Wigton 50MW expansion


Wigton Energy is one of two entities that gained approval from the Government of Jamaica in the tender process to install 100 megawatts of renewable energy for Jamaica’s national grid.

According to a release from Wigton, the company “will install a 49.83MW solar energy facility in Clarendon” which, upon completion, will result in the company almost doubling its generating capacity, with existing wind turbines accounting for nearly 60 MW.
The size plant will likely take approximately one year to come on stream in late 2025 and should cost under US$50 million, our source informed ICInsider.com
Profit could double in the first full year of the expanded operations, in the March 2027 fiscal year

Wigton closed at anew high of $1 Bids for another phase are expected to be open to the public in early 2025 covering roughly 160 MW.  Wigton is in a good position to participate in the bidding process and if successful could see further expansion and income generation.
Profit before taxation at Wigton increased 121 percent to $413 million, from $187 million in 2023 during the six months to September 2024, with net profit falling 39 percent to $310 million from $504 million in the same period last year, primarily due to an adjustment in the income tax rate from 33.33 percent down to 25 percent, resulting in a one-off tax credit recorded, 2023 compared to a tax liability in the September 2024 period. Profit before taxation for the three months, to September, more than doubled to $192 million, from $79 million in 2023, with after-tax profit ending at $143 million.
he stock value was already well ahead of the Jamaica Stock Exchange average PE of 14.4 at 23 times 2025 fiscal year earnings and climbed to 26 following the announcement.