AS Bryden’s CPJ holdings now over 75%


AS Bryden and Sons Holdings acquired another 30.4 percent amounting to 334.3 million shares of Caribbean Producers with the trade taking place on Friday over the Jamaica Stock Exchange Main Market. The acquisition takes the group’s holding to 75.3 percent a release from the Trinidad company confirmed to the Jamaica Stock Exchange.
The selling shareholders are Sportswear Producers Limited with 168,722,866 shares or 15.3384 percent of the CPJ issued capital, Thomas Tyler with 82,830,563 with 7.5301 percent and Wave Trading Limited with 82,755,239 shares with 7.5232 percent. ASB swapped 94.87 million of their shares to the CPJ sellers.

In Main Market activity on Friday, Caribbean Producers led trading with 334.34 million shares valued at $2.6914 billion, which includes the above shares at a value of $2.691 billion.
The acquisition now triggers a mandatory takeover offer that will be made within 30 days, , but they intend to keep the company listed, AS Bryden and Sons Holdings stated in the release.
Profit blown off course at overpriced Wigton


Profit surged 121 percent before corporate taxes, to $413 million, from $186 million at Wigton Energy for the six months to September 2024, net profit decreased 39 percent, to $310 million, from $504 million in the similar period last year, due primarily to a tax credit of $318 million arising from a reduction in the tax rate from one third to 25 percent that was retroactively applied to profits.

Wigton closed at anew high of $1For the latest quarter, profit jumped a solid 144 percent before tax to $192 million, from $79 million in 2023, with net profit falling to $144 million following taxation of $48 million compared with a profit of $436 million following a tax credit of $357 million in 2023.
Total revenue comprising sales and other income for the six months to September 2024, amounts to $1.42 billion, an increase of 13 percent compared to $1.25 billion earned in 2023. Management in their report to shareholders stated that “the increase in total revenue was as a result of (i) the higher production levels up to June 2024, which assisted in achieving the total production of 63.6 million kWh during the period despite the lower average availability being 74.9 percent as a result of the downtime associated with hurricane Beryl, and (ii) a provision of $239.4 million representing the anticipated business interruption insurance proceeds related to Hurricane Beryl.” Investors also need to be aware that there are seasonal variation in power generation, with the best periods being in the June quarter.
Cost of sales fell to $229 million in the September quarter from $256 million in 2023 and from $495 million in 2023 for the half year to $428 million.
General administrative expenses rose 11 percent to $387 million from $349 million in 2023 in the half year and was down slightly in the second quarter to $191 million versus $193 million in 2023.
Finance costs declined to $90 million in the September quarter from $103 million and in the half year, it declined from $210 million to $183 million.
Current Assets ended at $4.6 billion in September which includes cash and equivalent of $3.55 billion and receivables of $772 million and Current Liabilities amounts to $1.09 billion of which current portion of long term loans amounts to $869 million.
Shareholders’ equity amounted to $5.4 Billion and Long term liabilities ended at $2.6 billion.
The directors advised that “ongoing discussions with key stakeholders are centred on the repowering of Wigton Phase I located in Rose Hill, Manchester. The Company was one of two (2) entities pre-awarded by the Generation Procurement Entity (GPE) in their September 2023 tender for additional energy to the grid. The decision of the GPE as to the final award is now awaited.”
Wigton is involved in a critically important area of economic activity in Jamaica, with scope for expansion, this makes it an attractive vehicle, but the stock with a PE around 23 times current earnings is well above the market average of 14.5. The company is banking on getting approval for their bid to be awarded to supply power to the national grid. With just two entities preapproved they stand a good chance of getting approval. They have received approval for renewal of the number one wind turbine, the price of the output is yet to be disclosed.
Investors in this stocks will find greater and more compelling values elsewhere currently.

Revenues jump at Express Catering


Revenue grew an impressive 20.7 percent to US$25,590,638 from $21,198,904 in 2023, with profit before taxation falling by 37.9 percent from $2,938,003 in 2023 to $1,825,441 and profit after tax dropping 76.9 percent to $1,408,276 from $2,702,227 for the year to May 2023 at the Montego based Express Catering.
Results for the August 2024 first quarter saw revenues rising marginally to US$6.5 million compared to US$6.4 million in 2023, with net profit for the Quarter climbing 18.6 percent to US$1.0 million for an EPS of 0.062 US cents per share, compared to a net profit of US$843,114 for an EPS of 0.051 US cents per share in the similar period in the prior year, with an increase spend rate rising by 9.83 percent, the company reported. The quarterly results would have been negatively affected by a falloff in traffic passing through the Jamaica’s busiest airport during the quarter.
For the latest quarter, gross profit rose 5.4 percent to $4.54 million from $4.3 in 2023, as cost of sale declined from $2.1 million down to $1.94 million. Administrative expenses fell from $2.13 million in 2023 to $1.85 million in 2024, Depreciation climbed by 41 percent to $941,539 from $666,526, following the establishment of addition outlets at the Sangster International Airport and finance costs rose from $536 million to $641 million. There was no provision for taxation in either periods.
The performance would be vastly better had the company been compensated for lending a large sum to related group companies. Amounts outstanding continue to climb and sit at US$17 as of August according to the latest interim accounts and jumped from US$12.47 million at the end of May 2023.

For the 2024 financial year, the cost of sales rose by 14 percent, slower than the growth in revenues, with the cost climbing to $8,470,019 from $7,432,646, resulting in a Gross profit of $17,120,619, up by a respectable 24.4 percent over $13,766,258 in 2023.
Promotional expenses for the year jumped 246.5 percent to $41,449 from $11,962, while Administrative expenses climbed 50 percent from $5,883,155 to $8,819,337. Depreciation climbed by 16.2 percent to $3,153,325 from $2,714,003.
Profit before interest expenses and taxation amounts to $5,106,508 for the fiscal year to May, compared to $5,157,138 in 2023
Finance costs jumped 44.5 percent to $3,257,186 from $2,253,791, Income tax climbed 47.9 percent to $417,165 from $235,776 in 2023.
The directors in their report on the August quarter stated that “Cost of ingredients as a ratio of revenue improved appreciably for the Quarter, registering a 2.82 percentage point improvement to close at a ratio of 29.96 percent, compared to 32.78 percent for the same period in the prior year. The company successfully implemented wide ranging price increases across most concepts beginning in August 2024. We are assessing any impact on volumes and expect to see the full impact of that change in the second Quarter. The expectation is for an additional 1.5 percent improvement in the COS ratio due to the price changes.”
The directors went on to state, “In June 2024, the national minimum wage was increased by 5.38 percent. This contributed to the overall 11.39 percent increase in the salaries and wages component of administrative costs for the Quarter. Other noteworthy cost increases were in utilities and insurance. There were savings in occupancy costs due to the increase in the minimum guaranteed rent. The lease liability and the underlying right-of-use assets were already adjusted to account for the increase. There were also some savings in franchise fees as well due to the change in the spread of revenue amongst proprietary vs franchised brands during the Quarter.”
Current assets ended the period at $18.75 million including $17.4 million due from related companies and cash and bank balances of $90,853. The related companies should not be treated as current as the amount has been climbing for several years. Current liabilities ended the period at $8.3 million. At the end of August, shareholders’ equity amounts to $8 billion with long term borrowings at $40 million including lease obligations of $14 million and short term loans at $3.5 million.
The company was able to resume dividend payments. An interim dividend of US0.0306 cents per share for a total of US$501,075 was paid on August 30, 2024. A second interim dividend of a similar amount was declared for payment on October 31.
ICInsider.com projects 40 Jamaican cents per share for current years’ earnings and 65 cents for 2026, with a PE ratio of 8 at the last traded price of $3.28, compared to the market average of 12.2. The stock is undervalued but management has not treated the minority shareholders equitably and this needs to change.

Blow out profit for Iron Rock

Insurance revenues jumped 40 percent to $1.4 billion and net profit surged 150 percent to $84 million at Iron Rock Insurance for 2023 as insurance results climbed from $63 million to $120 and Investments delivered slightly higher gains of $79 million rising from $64 million in 2022, the company’s long-delayed audited financial statements show.

Operating expenses rose 14.4 percent from $104 million to $119 million as the company generated 39 cents in earnings per share for the year, up from 16 cents in 2022. ICInsider.com had a forecast of  32 cents.
At the end of 2023, shareholders’ equity stood at $748 million. Investments was $630 million, with reinsurance assets of $427 million and Insurance liabilities of $777 million.
The company improved its performance in the March quarter this year, with revenues rising by 29 percent to $401 million. Return on investments rose to $29 from $16 million in 2023. Other operating expenses climbed from $30 million to $37 million. A profit of $5.5 was realised, up from a $12 million loss in 2023, with earnings per share of 3 cents.
At the end of 2023, shareholders’ equity rose to $756 million. Investments stood at $719 million, with reinsurance assets of $312 million and Insurance liabilities of $735 million.
Iron Rock generated positive cash flows of $45 million in the quarter and $254 million for the 2023 fiscal year.
The stock was in the ICTOP10 Junior Market listing but was dropped following the suspension of trading but with projections of 55 cents per share for 2024 it will most likely be back, subject to stock price by week end.
The stock rose 12 cents on Tuesday to $2.30, with just three offers amounting to 115,000 shares, with 7,004 units at $3.30 up to $4.36.
With projected earnings of 55 cents per share, the PE ratio at the last price is just 4.2 times earnings, well below the market average of 12.4.

Profit surged 144% at the Lab

Net Profit for the half year was $49.4 million, up a b 144 percent above the $20 million generated in 2023, at Limners and Bards for the quarter profit rose 71 percent to $23 million from $13.6 million for the same period in 2023.
The improved profit flowed from reduced costs and better margins as revenues fell sharply in the Media segment, with a $100 million reduction to $206 million. Segment profit fell from $43.5 million to $31.9 million. Media was not the only area of contraction, production had a minor drop in revenues to $127 million from $130 in 2023 but delivered a $13 million fall in profit contribution to $50.6 million from $63 million in 2023. The agency segment saw profit contribution jumping $98 million from $86 million in 2023 with revenues rising from $102 million to $113 million.
For the second quarter, total revenues for the company fell 23 percent from $291 million to $226 million and declined 17 percent to $446 million from $539 million in 2023 for the half year.
Although gross profit fell in both periods, to $91.4 in the latest quarter from $100 million in 2023, down 8.6 percent and declined by 6 percent from $193 million for the six months to $180 million. Gross margin grew, with direct costs declining faster than revenues for half of the year, down 23.5 percent to $265 million from $347 million and by 29.4 in the quarter to $135 million from $191 million.
Administrative expenses fell 17 percent to $69 million in the quarter from $84 million in 2023 and declined 18 percent to $138 million in the half year from $169 million in 2023.
Selling and distribution cost expenses declined in the half year and second quarter by 36 percent to $966,245 in the half million from $1.5 million and by xxx percent in the quarter to $484,477 from $810,997 in 2023. Finance cost declined in the quarter, to $2.6 million from $3.5 million in 2023 and from $6.9 million to $5.2 million for the six months. Finance Income rose from $922,872 to $5.33 million in the quarter and for the six months, it moved from $4.5 million to $8.4 million.
Current assets ended the period at $864 million and Current liabilities at of $298 million. The company has cash and bank balances of $559 million, up from $438 million in 2023.
At the end of April, shareholders’ equity amounts to $647 million with loans payable at $106 million.
Earnings per share for the quarter was two cents and 5 cents for the year to date. IC Insider.com computation projects earnings of 10 cents per share for the fiscal year ending August 2024, with a PE of 16 times the current year’s earnings based on the price of $1.56 the stock traded at on the Jamaica Stock Exchange Junior Market. Net asset value ended the period at $0.68 with the stock selling at 3 times book value.
The company in its quarterly report to shareholders, indicates that they have ventured into the risky business of film production. The first production ‘Jenna In Law’, was officially selected to screen at the 2024 Essence Film Festival this summer in New Orleans, Louisiana.

NCB at 11 year low is it a buy yet?

Investors buying into the public offer of NCB Financial Group stock at $65 each in May are hugging up an 18 percent loss on their investment since, with the stock hitting a 52 weeks’ low of $54.66 on Monday and ending at a closing low of $55 after more than 1.5 million shares were traded, following a sizable 3 million share trade on June 17, when the stock closed at $59.
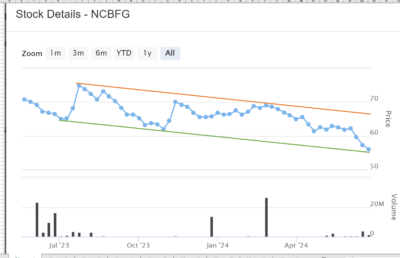
Investors in the stock whether new or not are taking the beating following the public offer that came when the stock was trading at an eleven year low going back to February 2013. The question for investors is whether the price has reached a bottom and when will a consistent rebound commence. The accompanying chart will help in partially answering the questions.
NCB is a diversified financial group, providing services in general insurance, life insurance, banking and investments management. The group is also geographically diversified with operations in Trinidad, Bermuda and Jamaica. It has a solid base that it can use to produce increased revenues and profits in the future.
Currently, the stock trades at a PE ratio of just 6.5, at a steep discount to the Main Market with an average valuation of 14, but higher than Scotia Group at a mere 6.
The major issue is whether the stock price is at or near the bottom. The attached chart offers some clues, with the stock trading at the bottom of a downward sloping channel.

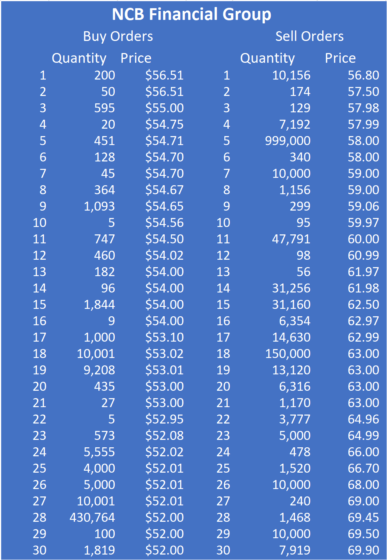
30 highest bids and offers for NCB shares mid morning on Wednesday.

30 highest bids and offers for NCB shares mid morning on Wednesday.

It may take some time for the added pressure brought on by the issue of the additional shares for which there was inadequate demand, to abate.
The price seems to have reached support at the channel bottom. The lower channel line goes back to July last year. The trend shown by the channel, between the green and the orange lines is negative, sloping downwards, suggesting that the price downturn could continue awhile longer. The stock will probably bounce off the low reached on Monday, but the demand shown by the order book is thin, suggesting the price could go lower. It would not be surprising to see the stock hitting $50 before bottoming out. If it rebounds from where it is now it’s likely to get back to $65 and probably resume its decline towards the $50 mark as buyers at $65 try to get out. Although undervalued, investors should be cautious in buying the stock around the recent price. They should probably await clearer signals that it is at the bottom.

Caribbean Assurance Brokers up 73%

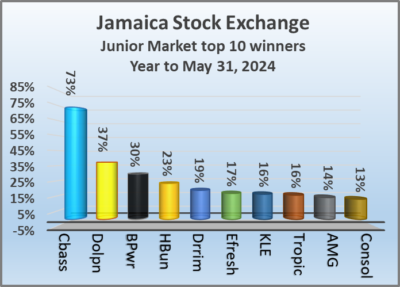
The Jamaica Stock Exchange Main and Junior Markets recorded mild declines for the year to the end of May, at the same time the Top 10 performing stocks all posted double digit gains with Caribbean Assurance Brokers landing a 73 percent increase to be the best performing stock in both markets.
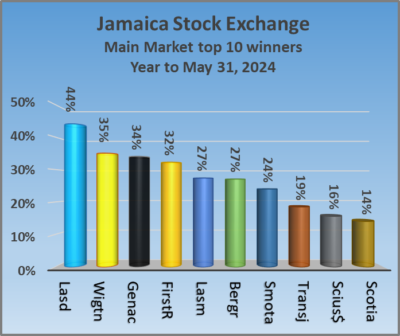
Three of the top performing Main Market stocks migrated from the Junior Market, two this year and one at the end of May last year. Lasco Distributors ended as the best performing stock in the Main Market with a 44 percent gain, followed by Wigton Windfarms with 35 percent, with demand coming in to buy based on the removal of ownership restriction and General Accident another former Junior Market stock that migrated last year, up 34 percent, with profit reported in the 2023 audited accounts beating expectations and followed by 30 percent rise in the 2024 first quarter profit before taxation. First Rock gained 32 percent and Lasco Manufacturing with improved full year results over 2023 posted gains of 27 percent.
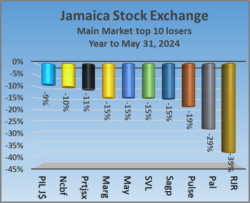
In the Main Market, Radio Jamaica is down 39 percent and Palace Amusement with a decline of 29 percent were the worst performers, the former reporting a loss for the nine months to December last year and Palace that came under selling pressure. Pulse Investment lost 19 percent and the Sagicor Group 15 percent.
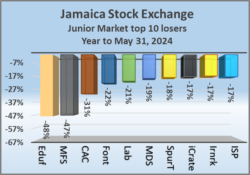
In the Junior Market, Dolphin Cove is the second best performing stock with a gain of 37 percent based on improved profit and increased dividend payment and Blue Power is up 30 percent, ending as the number three winner, following improving profit. Honey Bun with improved full year and first half year results gained 23 percent followed by Derrimon Trading up 19 percent. Edufocal fell 48 percent to be the worst performing Junior Market stock followed by MFS Partners with a fall of 47 percent and CAC 2000 down 31 percent, following continued poor results. Also declining are Fontana down 22 percent and Limners and Bards had a fall of 21 percent
Helping the performance is a big jump in the volume and value of stocks traded in the Main Market with the Junior Market suffering from reduced trading compared with last year.

Profit continues higher at Scotia Group

Scotia Group had another financially successful quarter ending April this year, with profit climbing a solid 31 percent to $5.4 billion and earnings per share (EPS) of $1.74, up from $4.1 billion in 2023, with EPS of $1.32. For the six months to April, profit rose 14 percent to $8.54 billion with earnings per share (EPS) of $2.74, from a profit of $7.49 billion in 2023 and EPS of $2.41.

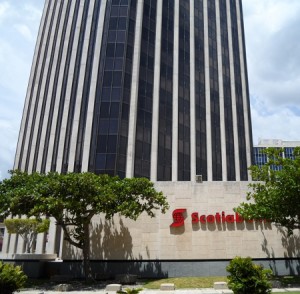
Scotia Group head quarters in Kingston.

Total comprehensive income climbed to $6.65 billion in the quarter from $4.79 billion in 2023. For the half year, it fell to $2.76 billion from $3.6 billion in 2023 as other comprehensive income suffered a loss of $5.78 billion in the 2024 period and $3.86 billion in 2023 as a result of an $11 billion increase in defined benefit obligations in 2024 and $9.3 billion in 2023.
Total revenues rose 20 percent for the quarter, to $16.9 billion from $14.1 billion and climbed a solid 18 percent for the year to date, to $33.3 billion from $28.3 billion in 2023. Interest income rose 18 percent in the April quarter to $11.7 billion from $9.9 billion in 2023 and 20.4 percent for the six months to $23.3 billion from $19.4 billion.
The critical and the single most important area of the group’s operation of lending helped to deliver a 17.6 percent increase in a net interest income of $11.24 billion in the second quarter of this year, from $9.56 billion in the prior year and, it rose 18.4 percent to $22.35 billion in the six months from $18.87 billion in the 2023 half year.
According to the group directors, “Our loan portfolio increased by $35.5 billion or 14.4 percent compared to April 2023, with loans net of allowances for credit losses increasing to $282.3 billion. Our core loan book continues to perform well with mortgages increasing year over year by 24 percent, consumer loans by 13 percent, credit cards by 15 percent and commercial loans by 8 percent.” Loans grew 2.2 percent in the January quarter over October, with the pace picking up to 2.25 percent in the April quarter over January, this year, for an annualized growth rate of 10 percent.
Deposits by the public increased by 6 percent or $27 billion to $464 billion. Investment securities increased marginally to $156.5 billion from $151.6 billion last year.
Net income from foreign currency trading, fees, commission and other income went up 22 percent from $3.6 billion to $4.4 billion in the April quarter and rose 14 percent from $7.7 billion in the half year in 2023 to $8.4 billion in the current year.
Insurance activities delivered profits of $530 million for the latest quarter, up from $493 million in the previous year. For the half year, it moved to $1.05 billion, from $1.03 billion in the comparative period in 2023. Foreign currency trading gains amount to $2.23 billion in the latest quarter compared with $1.94 billion in 2023 and for the year to date, $4.56 billion in the six months to April versus $4 billion in 2023.
Credit impairment losses jumped sharply to $1 billion in the April quarter from $665 million last year to $2 billion in the half year, compared with $1.75 billion in 2023.
Segment results show Retail Banking with revenues of $11.06 billion compared with $10.1 billion in 2023 and delivered segment profit of $1.6 billion versus $2.1 billion in 2023. Corporate and Commercial banking had a 13 percent growth in third party revenues to $7.9 billion and net segment results of $7.2 billion compared with revenues of $6.9 billion in 2023 as net results surged sharply over the $5.2 billion in 2023. Treasury generated revenues of $7.7 billion up from $5.8 billion with a net position of $1.13 billion in 2024 compared with $1.03 billion in the prior year.
Investment Management Services generated revenues of $1.5 billion and a net result of $780 million in 2024, with revenues of $1.56 billion in 2023 and a net outturn of $806 million in 2023. Insurance services had a mild increase in revenues to $2.08 billion in 2024 as net results slipped to $2.05 billion, compared with revenues of $2.45 billion in 2023 and net segment results of $2.15 billion.
Salaries and staff benefits rose 12.8 percent to $2.96 billion from $2.63 billion in 2023 and for the half year, it rose by 13 percent from $5.23 billion to $5.9 billion. 

Scotia Group traded at a $58 on Friday.

Other operating expenses fell marginally from $3.28 billion to $3.23 billion in the quarter and increased slightly in the nine months to $6.7 billion from $6.55 billion in the previous year. Overall, total operating expenses moved from $6.57 billion in the second quarter last year to $6.78 billion. For the six months to April, it moved by 7 percent to $15.46 billion from $14.4 billion in 2023.
Taxation on profit amounted to $2.38 billion in the April quarter up from $1.89 billion in 2023 and it rose 15 percent to $4.47 billion in the half year from $3.89 billion in 2023.
Shareholders’ equity ended the period at $127 billion, up from $108 billion at the end of March 2023.
IC Insider.com computation projects earnings of $6.50 to $7 per share for the fiscal year ending October 2024, with a PE of 6.5 times the current year’s earnings based on the price of $44.41 the stock traded on the Jamaica Stock Exchange. Net asset value ended the period at $4.78 with the stock selling at xxx book value.
The company declared a dividend of 40 cents which in line with payment in  April versus 35 cents in July 2023.

428% dividend hike jolts stock price

Caribbean Assurance Brokers announced a 428 percent jump in dividends to 14.11 cents from just 2.67 cents paid last year. This year’s dividend is payable on September 16, with an ex-dividend date of August 15 and the announcement pushed the stock up 22 percent in a day and 73 percent for the year to date.
The dividend yields 4.8 percent based on Thursday’s closing price of $3.15 and four percent based on Friday’s closing of $3.83, almost twice the junior Market average of 2 percent.
The increase follows a jump in profits for 2023 to $123 million or 47 cents per share after a charge of $17 million or 6.5 cents per share for doubtful debt which was reversed in the first quarter to March this year with a profit of just $3 million after the credit impairment loss was revered and compares with a profit of $17 million in 2023.  Net profit for 2022 was $78 million or 30 cents per share.
Also announcing dividend payment is Salada Foods with an interim dividend of 6.4 cents per stock unit, payable on July 4, 2024, with an ex-dividend date is June 14.

Dolphin Cove the dividend king

The dividend yield on the Junior market listed Dolphin Cove is 10 percent based on Wednesday’s early traded price of $24 and dividends of $2.40 payable since October last year.

Dolphin Cove price paying 60 cents dividend in June.

Dolphin’s shareholders have much more than the high yield to cheer about, with the stock gaining 68 percent in value over the past twelve months in a market that has delivered no increase during the same period. The company reported profit declining from US$1.57 million for the first quarter last year to $1.38 million in the March 2024 quarter with revenues of US$4.9 million up from US$4.85 million with operational expenses jumping by US$300,000. For the year to December 2024, the company reported sales of US$17 million from $15 million in 2023. It generated a profit of US$4.2 million before booking a cost of US$1.13 million in penalties and interest on GCT relating to an earlier period compared with $2.97 million in 2022
The returns for Dolphin are far ahead of a 7 percent yield for Mailpac but in line with Carreras at 10 percent yield and Transjamaican Highway at 6 percent. Scotia Group another high dividend payer is currently 4 percent but that is expected to rise as the year progresses and dividends are increased with rising profit and a return to the traditional pay out ratio of more than 40 percent of profit.
The real virtue of Dolphin over Carreras is that the former continues to record growth while the latter has has little or no growth for years.