Scotia hikes dividend on profit rise

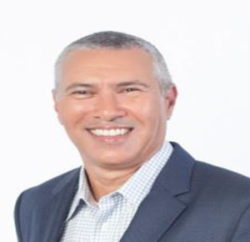
Jackie Sharp - CEO Scotia Group

Jackie Sharp – CEO Scotia Group

Scotia Group raises dividend with the Board of Directors approving a final dividend of 45 cents per stock unit in respect of this financial year, which is payable on January 18, 2017 to stockholders on record as at December 27, 2016.
The proposed payment brings the total payment for the year to $1.71 and represents a 6 percent increase in dividends year over year and a dividend payout ratio of 47.08 percent of profit. The final payment means that the 2017 payout should be no less than $1.80, with the proposed payment setting the stage for future quarterly payments. Scotia Group released results with earnings per share ending at $3.63 compared to $3.19 for 2015.
At the same time Scotia Investments held dividends at 45 cents per share the same amount they have been paying in recent times although the company report net profit of $1.35 billion for the year ended October compared with $1.02 billion for the prior. The 2016 profits rose by 32 percent or $325 million net income of $537 million for the quarter ended October, up from $288 million the quarter ending October 2015.
Strong gains of $527 million in fee income, foreign exchange trading gains and gains on financial assets were the main contributing areas that gave rise to the increased profit for the year, for Scotia Investments with earnings per share of $3.19.
Quick about turn at Key Insurance

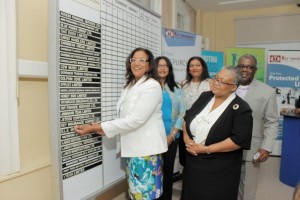
Natalia Gobin-Gunter Chairman and Deputy Managing director inserting name strip to indicate listing of Key Insurance on the junior market.

Natalia Gobin-Gunter Chairman and Deputy Managing director inserting name strip to indicate listing of Key Insurance on the junior market.

Key Insurance recovered from a loss of $21 million in the June quarter to a profit of $84 million in the September quarter, up from a loss of $284,000 in the 2015 third quarter and also reversed the loss in the six months to June this year of $18 million.
The second quarter was negatively affected by an Insurance claims of $747 million compared to just $82 million in 2015 for the same period. In the September quarter the insurance company benefited from a positive turn around for claims.
The claims experience in the second quarter forced the company’s management to review the insurance claims and reserves quarterly rather than annually in the past. The end result is that claims seem to be back to normal in the third quarter with a net recovery in claims of $228 million as opposed to an expense of $193 million expensed in 2015.
Nine months profit ended at $66 million compared to $68 million for the 2015 period and seems set to reach $120 million for the full year, for earnings per share of 35 cents. At this level of earnings, the stock has a PE of 6, the lowest in the junior market.
Key generated net premium income of $166 million up 25 percent over 2015 and $451 million for the nine months, an increase of 28.5 percent. Administrative expenses rose from $77 million in the 2015 third quarter to $100 million in 2016 and for the nine months to $281 million from $220 million.
The stock last traded at $2 on the junior market of the Jamaica Stock Exchange.

Cargo Handlers updates results

CAR H 2015-06-26Cargo Handlers updated their results for the full year to September following IC Insider’s posting of a report that the company reported results with errors relating to the number of shares used to compute earnings per share.
Cargo Handlers posted their full year profit of $154 million after tax, up from $136 million in 2015 and $30 million for the fourth quarter versus $29 million in 2015. The company originally reported earnings per share as 40 cents for the quarter and $3.30 for the 12 months, based on what they showed as a weighted average number of shares held during the period.
The company split its stock into 10 units for each one held, subsequent to the year-end and would not result in computing the average number of shares in issue. With a stock split or stock bonus the earnings per share is to be computed on the full amount of shares issued at the time of the financial report and the historical earnings per share would be revised based on the new issued shares in issued.
The updated report now shows earnings of 79 cents per share for the last quarter and $4.11 for the full year. The company’s stock last closed at $11.80 on the junior market of the Jamaica Stock Exchange.

Seprod profit up & dividend jumps

Seprod announced a dividend of $2.63, driving the stock to a  new 52 weeks' high of $30.

Seprod announced a dividend of $2.63, driving the stock to a new 52 weeks’ high of $30.

Seprod looks set to pay out all of their 2016 profit in dividend in November, with a payment of $1.36 billion. Chairman Paul Scott told IC Insider that the payment was due to gains made from the sale of shares previously held in Grace Kennedy, giving rise to investment gains of $874 million to September.
The board approved a big pay out of two dollars and sixty-three cents ($2.63) per share on November 28, to all shareholders on record as at November 18. The stock will trade ex-dividend on November 16. The dividend will consume $1.36 billion of the company’s cash and investments which stood at $3.9 billion at the end of September.
Seprod reported profit before losses attributed to minority shareholders in its subsidiary of $127 million for the September quarter versus a loss of $66 million in 2015 and $943 million for the nine months period compared to $375 million in 2015. Earnings per share amounts to 39 cents for the last quarter and $2.09 for the nine months as sale revenues declined to $11.1 billion for the nine months from $11.2 billion in 2015 but with the last quarter rising by 10 percent to $3.5 billion.
According to Scott the future looks bright going forward. “We are breaking even in the sugar operations with 11,000 tonnes of sugar produced last crop, Seprod Group.
Seprod banking on growth in its dairy operations making big contribution to profit.

Seprod banking on growth in its dairy operations making big contribution to profit.

before interest charges and expectation of 16,000 tonnes of sugar being produced in 2017, which should be profitable,” Scott told IC Insider. There is also the expectation of higher price for sugar in 2017 than in 2016. The added tonnage if achieved could result in around $300 million more in revenues with most of it flowing to the bottom line of a The next three years should see a slate of new products being produced with the dairy operations being a major contributor to this thrust with the local and Caribbean markets being targeted. Seprod in it unassuming style quietly produced some of the better returns to shareholders of listed companies, in the last 5 or so years has seen profit stagnated with the tightness in the economy and gig losses in the sugar operation. Recent results and pick up in economic activity locally and with the rate of exchange of the Jamaican dollar having adjusted against the back ground of relatively inflation has given the company a competitive edge in a number of areas which it seems poised to take advantage of in growing the business.
The stock last trade at $27.50 on the main market of Jamaica Stock Exchange and looks like a buy for the further.

Record profit for National Commercial Bank

NCB con springNational Commercial Bank ended its financial year to September with record profits helped by strong loan growth and big loan recovery of loans that were previously quarantined as doubtful.
The big Jamaican bank posted profit after tax and minority interest of $5 billion for an increase of 34 percent over the similar period in 2015 and a rise of 27 percent for the full year to $15.6 billion.
Earnings per share ended at $2.03 for the fourth quarter and $6.35 for the year. NCB recovered bad loan resulting in a positive flow of $291 million in the last quarter reducing the full year charge to $612 million compared to $1.8 billion in 2015.
Revenues net of interest expense rose 12 percent to $13.6 billion for the quarter and 9.6 percent to $52 billion for the full year. Net interest income grew 8.3 percent for the year to $28.1 billion. NCB results of a boost from Associated company profit, that rose from $122 million to $443 million in the September quarter and to $832 million from $434 million in 2015.
Loans, the critical contributor to revenue growth grew a strong 14.3 percent for the year to reach $189 million while investment securities declined modestly.
The group declared a dividend of 90 cents per share bring the full year payment to $2.25. The stock which remains IC Insider Buy Rated, last traded on the Jamaica Stock Exchange at $45.50 and is in strong demand with limited supply.

JSE feeds public with erroneous info

CAR H 2015-06-26 001Jamaica Stock Exchange is one of Jamaica important financial institutions. It is responsible for billion of dollars of investments. Investors rely on it to be transparent and to provide accurate and timely information on which investment decisions can be made. Why does the feed the public with erroneous information, and leave it out in the public without moving speedily to correct same?
Cargo Handlers posted their full year results to September, with profit of $154 million after tax, up from $136 million in 2015 and $30 million for the fourth quarter versus $29 million in 2015.
All of the above is fine but the company is reporting earnings per share as 40 cents for the quarter and $3.30 for the 12 months, based on what they have erroneously claimed are based on the weighted average number of shares held during the period. That of course is nonsense. The company split its stock into 10 units for each one held, subsequent to the year-end, hence there were no additional shares issued up to September. Even if the stock split occurred during the financial year, the split would not give rise to computing the average number of shares in issue. With a stock split or stock bonus the earnings per share is to be computed on the full amount of shares issued at the time of the financial report. Only when fresh capital is introduced from outside the company, would the weighted average number of shares be computed.
JSE signThe earning per share is in fact 80 cents, for the 2016 last quarter and $4.16 for the 12 months. Unfortunately, the Stock Exchange posted the results with the error from Monday and they are still on the website with no change to date and no note to inform investors of the error. If the Jamaica Stock Exchange wants to be taken seriously it needs to do better than this.
Cargo Handlers last quarter’s net position flowed from a 17 percent rise in revenues to $78 million and 29 percent increase for the full year to $324 million. Other operating expenses rose 19 percent for the quarter to $39.8 million and for the full year 28 percent to $132 million.
The numbers may not show it fully, but growth may have slowed considerably, as such growth in profit in the medium term could be quite moderate as can be gleaned from the movement in the quarterly results. At a price of $12 per share, with 375 million units issued the stock price is a tad rich currently with one of the highest junior market PE ratios at 30 times the 2016 earnings. Expectations of investors in the stock have to be that the December quarter’s earnings will rise close to 50 percent, to justify the current price. That level of profit increase looks steep.

Sagicor Group profit climbs 49%

Sag bnk logoSagicor Group net profit attributable to Stockholders jumped 49 percent to $3.1 billion for the September quarter and 27 percent to $7.39 billion for the nine-month to September, over the similar period in 2015.
Improvement in realized gains from securities trading played a big role in the increased profit with investment income rising 43 percent or $1.6 Billion in the quarter to $5.5 billion and a rise of 20 percent or $2.6 billion to $15.56 billion for the nine months to September.
Earnings per stock ended at 79 cents for the quarter and $1.89 for the nine months compared to $1.49 in 2015 and could end around the $3 region by the end of the financial year. Return on average Stockholders’ Equity was 19 percent compared to 17 percent.
“Our core Insurance and Banking businesses produced good results. The overall performance was principally driven by good business growth across all lines, greater than expected capital gains on sale of securities and favourable benefits experience“, management stated in their report to shareholders.

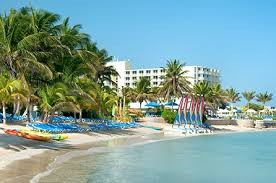
Rose Hall hotel owned by Sagicor Real Estate fund

Rose Hall hotel owned by Sagicor Real Estate fund

Revenues for the quarter rose 25 percent to $16.3 billion versus $13.1 billion in 2015, for the nine months, revenues came in at $45.33 billion, better than prior year by 14 percent. Revenues include net premium income of $25 billion rising from $22.35 billion in 2015. Realized capital gains from securities trading of $3.29 billion, were substantially up on prior year.
Administrative expenses of $10.8 billion, were 13 percent more than in 2015, well below the rate of growth in revenues. “The cost increase was driven by higher staff costs, expenses relating to our expanded credit cards program and other non-recurring items,” management said in their report to shareholders. For the September quarter, administrative expenses rose 11 percent to $3.7 billion
Sagicor Group comprises a number of companies offering financial products and services, including life and health insurance; annuities; pensions administration; investment services; commercial banking; investments banking; captives management; property management and real estate sales and rentals.
The company shares are listed on the Jamaica Stock Exchange and last traded at $23.18 and is undervalued.

LASCO Manufacturing profit jumps 45%

Lasco canProfit jumped 45 percent to $363 million for the quarter ending September this year, from $250 million in the September 2015 quarter for LASCO Manufacturing from revenue of $2.2 billion, an increase of 29 percent over the 1st quarter, this year and 35 percent over the June quarter of 2015.
For the six months period ended September 2016, LASCO generated a net profit of $587 million, 18 percent above the previous year’s profit of $497 million.
Revenue increased 28 percent to September 2016 to $4 billion, over the same period last year resulting from increased production as part of the expansion of the manufacturing plant. Gross margin of $1.3 billion, was achieved compared to $1 billion, the previous year.
Expenses for the six months rose 23 percent to $585 million, compared to the same period last year, due mainly to increases in marketing and equipment maintenance expenses.
Lasco new drnks“Production at the Liquid Plant continues to grow steadily, and we will further increase our capacity to meet the market demand for our iCool line of beverages, by ramping up production with the installation of additional equipment by the end of the financial year. We continue to be optimistic and confident about the future for this product line with substantial profits to be realized” Robert Parkins, Managing Director, stated in a release with the results.
Perkins went on to say “The new Dry Plant at White Marl is now fully operational, and together with the existing Red Hills Road Dry Plant recorded an increase of 24 percent in profits over last year at the end of the 2nd quarter. New products will be introduced by the end of the year to enhance the product line which is projected to continue to realize significant sales and profits.”
“The Statement of Financial Position shows Property, Plant and Equipment moving from $3.5 billion, at the beginning of the financial year to $4.6 billion at the close of the 2nd quarter. This is due to approximately $1 billion, of assets associated with both the liquid and dry plants being transferred during the period from work in progress as a result of continuing commissioning of these operations.”
The company reported cash flows from operations of $1.5 billion including more than $600 million released from working capital of which $1.17 billion was spent on expanding the plant.
IC Insider is forecasting $1.8 billion in profit or 45 cents earnings for the full year to March next year and $3.7 billion or 90 cents per share for 2018. Lasco last traded at $5 on the junior market of Jamaica Stock Exchange.

Lawsuit may cost CAC $200m

Steven Marston, Chief Executive Officer

Steven Marston,
Chief Executive Officer

CAC 2000 (CAC) could be facing a $200 million charge to the 2016 financial results arising from the successful claim X-ray Diagnostics against the company.
CAC in a release to the Jamaica Stock Exchange stated that the court ruled in favour of the Claimant and awarded damages of US$372,100 and J$568,187 plus loss of profits of $7,077,874. Interest at commercial rates and legal fees were also awarded.
CAC further advised that on application, the court granted a stay of execution of 42 days and that its legal counsel is reviewing the judgment but, in the interim, the company will be providing for these amounts less the insurance amount of $20 million in the 2016 accounts.
IC Insider estimates that the company will likely be hit with a total cost of US$1 million and J$100 million before the insurance coverage when interest and legal fees are factored in.
The judgement resulted from a claim in negligence and or breach of contract as a result of a fire that occurred at the Claimant’s premises on May 11th, 2003. The Claimant prevailed at first instance in the Supreme Court with CAC appealing the judgment on account of the trial judge in the Supreme Court excluding the testimony and or report of the Company’s expert from the evidence. The Court of Appeal held that the exclusion of such evidence “created an unnecessary imbalance which was not in the interest of justice.”
CAC logo 12-15CAC reported a loss of $9 million after tax for the July 2016 quarter and profit of $31 million after tax for the nine months period, compared to $39 million for the July 2015 quarter and a profit of $71.6 million for the nine months to July 2015.
The net results came from sales revenues of $679 million for the nine months period compared to $674 million for 2015 and $198 million for the July quarter versus $259 million in 2015. The company saw a large climb in administrative cost of 42 percent for the nine months in 2016 and 57 percent for the quarter.
CAC successfully raised $120 million before cost of approximately $10 million in its initial public offering in December 2015. The stock traded traded on the junior market of the Jamaica Stock Exchange at $6.30 on Monday.

Stunning 47% increased Scotia profit

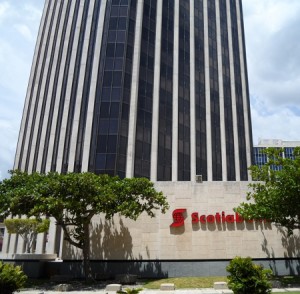
Scotia hq 25 9-14 Scotia Group reported a stunning in net earnings jumping 47 percent for the third quarter to $3.3 billion over the 2015 July quarter. For the nine months, net earnings jumped 36.7 percent to $8.2 billion. Total comprehensive income for shareholders of the group ended at $9.3 billion for the nine months ended July 2016 up 10.5 percent from $8.8 billion.
For the third quarter, total comprehensive income of declined from $4.4 billion to $3.66 billion.
The results translate to earnings per share of $1.07 cents in the July quarter and $2.64 for the nine months, with full year’s earnings set to end around $3.90 and would put the PE at 7.8 versus an average of 9 based on estimated 2016 earnings for the main market valuation.
President and CEO of the banking group, Jackie Sharp, in a report to shareholders, commenting on the performance stated, “We continue to show strong performance this year, resulting from the execution of our strategic initiatives to grow revenues and reduce operating costs. All business lines showed good volume growth year over year, as we continued to meet our customer’s diverse needs. Our loan portfolio, after allowance for impairment losses, grew by $15.2 billion or 10.2 percent year over year. Customer Deposits also increased by $42.4 billion or 20.8 percent year over year. Funds under management in our wealth business grew by $15.9 billion or 14.9 percent year over year.”

Jackie Sharp - CEO Scotia Group

Jackie Sharp – CEO Scotia Group

“Total revenues excluding impairment losses on loans for the nine months ended July 2016 was $28.8 billion, representing an increase of $2.46 billion above prior year. The positive movement was achieved through increased volumes and improved non-interest revenue, which cushioned the impact of reduced margins. Net interest income after impairment losses for the period was $17.6 billion, $670 million above the same period in 2015. This was due to an increase in net interest income of $745 million, resulting from growth in loan volumes, particularly our Retail loans, Residential Mortgages and Small Business portfolios, coupled with lower levels of wholesale funding. Impairment losses on loans increased by $75 million when compared with the same period last year.
Other revenue for the nine months ended July 2016 amounted to $10 billion, an increase of $1.7 billion or 20.6 percent compared to the same period last year. This was due to growth in net fee and commission income from increased transaction volumes on our deposit and payment services, credit card and merchant service business segments, as well as higher foreign currency gains.”
Sharp went on the further state “Operating Expenses amounted to $15.6 billion over the nine months ended July 31, 2016, a decrease of $464 million or 2.9 percent compared to prior year. Salary related expenses declined by $400 million, which offset higher operating expenses of $276 million. There was also a decline in asset tax of $330 million.”
Loans, after allowance for impairment losses amounted to $163.9 billion as at the end of the 2016 quarter, while nonperforming loans totalled $4.4 billion, representing 2.7 percent of total gross loans down from 3.1 percent last year. Total customer liabilities represented by deposits, securities sold under repurchase agreements, and policyholders’ funds grew to $350 billion, an increase of $35.3 billion or 11.2 percent compared to July 2015. A significant portion of the growth was reflected in core deposits, which grew by 20.8 percent year over year the company stated.
The stock that traded at $30.50 on the Jamaica Stock Exchange is undervalued and importantly with strong growth in the third quarter and increased growth in the loan portfolio as well as a pickup in economic growth in Jamaica augurs well for strong growth in profits going forward. Note need to be taken of a possible fall in foreign exchange gains an area that grew sharply in the July quarter by 127 percent to $1.17 billion.
The group declared another dividend of 45 cents per share and seems set to pay total dividend for the fiscal year of $1.80 providing an attractive yield of 6 percent.