 Jamaica Broilers sales revenues increased 12 percent over the $8.9 billion the group generated in 2015 to reach $10 billion for the first quarter ending July this year. Profit after tax from continuing operations fell to $401 million from $420 million in 2015.
The profit performance resulted from gross profit that grew in line with sales with a 12 percent increase in for the quarter to $2.7 billion, from $2.4 billion in the corresponding quarter last year and an increase in finance and other income of $178 million up from $123 million in the company’s 2015 first quarter.
Directors in their report to shareholders state that the “Jamaica Operations reported a normalised segment result (after adjusting for the effects of the disposal of subsidiaries) of $641 million compared to $783 million reported last year. This was a result of increased levels of poultry imports and increased input costs. The US Operations continued to grow steadily and reported a segment result of $297 million, which was a 14 percent increase over the prior years’ $261 million. This quarter’s results include for the first time the operations of the new subsidiary International Poultry Breeders Hatcheries Inc., based in Iowa.”
“In the Other Caribbean Operations segment, the increased production of table eggs in Haiti Broilers SA is now reflected in the profits being reported for the quarter. The normalized segment result, after adjusting for the effects of the disposal of subsidiaries, amounted to $74 million which was $49 million or 196 percent above the $25 million reported last year.”
 Distribution costs, grew much faster than sales, with an increase of 29 percent over the previous year, to $321 million from $248 million while administration costs moved up by 20 percent to $1.79 billion from $1.49 billion in 2015.
The profit out turn resulted in earnings of 33.08 cents per share for the quarter. IC Insider expects that with continued growth in sales revenues investors should see increased profit for the current year which will be aided by improved economic activity in the markets the group operates in.
At the end of the quarter, shareholders’ equity stood at $12.7 billion while loans grew from $6 billion in July 2015 to $6.9 billion in 2016 while cash funds and investments ended at $1.7 billion in 2016 versus $1.8 billion in 2015.
Jamaica Broilers’ shares are listed on the Jamaica Stock Exchange and last traded at $14.52 at PE ratio of 11 times last fiscal year’s earnings.
Dip in profit at Jamaica Broilers
Stock split coming for JSE
 Jamaica Stock Exchange (JSE) advised after trading closed on Thursday that the Board of Directors will be considering a stock split at a board meeting scheduled to be held on Wednesday, September 21, 2016. With only 140 million shares issued and 90 million being held by brokers members there is a strong possibility for a 5 for 1 stock split to allow for greater liquidity.
JSE reported of profit of $32 million for the June quarter versus $15 million in 2015 and $158 million compared to $102 million for the six months to June 2015. The improvement in net profit flowed from a 52 percent rise in revenues to $188 million for the June 2016 quarter compared with $124 million in 2015 and $525 million for the half year to June for a rise of 37 percent versus $382 million in 2015. Earnings per share for the half year ended at $1.12 versus 73 cents in 2015. The JSE had a big month of trading in August with some special trades that took place thus swelling the volumes and value to $6.6 billion for July to August compared to $6.5 million for the June quarter.
Expenses in the June quarter rose less than the growth in revenues at 40 percent and for the half year by 26 percent. Increase in salaries related cost was the major area of cost increase rising faster than the increased revenues. Salaries and related cost jumped 65 percent in the June quarter compared with a 52 percent gain in revenues for the quarter and 44 percent increase in wages for the half year to June, 7 percentage points higher than revenue growth. Wages accounted for 55 percent of total cost in the quarter and 46 percent for the six months period for all of 2015 the ratio was 43 percent.
 Segment results show a sharp jump in both revenues and profit for the Exchange Operations and that of Trustees Services for the half year. Exchange operations revenues grew to $326 million from $233 million in 2015 resulting in pretax profit of $151 million from $84 million in the six months to June 2015 while Trustees Services saw revenues shooting to $114 million from $46 million and with profit of $64 million from $18 million in 2015.
The stock traded on Thursday at $24.10 delivering a huge gain for investors who bought shares in the public offer in June 2013 at $2.85 per share. Some investors have done even better in buying the stock below $2 per share after it was listed.
ISP Finance revving to expand
ISP Finance plans to issue $150m in bonds in September.
The issue opens at 9 am on September 1 and will close at 4:30 pm on September 22, 2016. The Company will have the option to prepay the bonds at par before the due date. ISP reported revenues of J$52 million, a 7.2 percent increase over the J$49 million record in the second quarter of 2015, according to its unaudited financial results for the second quarter ended June, this year. Gross profit amounted to J$49 million compared to J$44 million in the comparative quarter in 2015. Net profit for the June quarter came out at J$11.7 million representing a 240 percent the $3.4 million generated in 2015, however, the company reversed $7.9 million in the June quarter, cost relating to the IPO, which it expensed in the first quarter, thus inflating the second quarter profit. For the six months to June revenues grew to $106 million from $99 million in 2015. Net profit for the six months ended at $8.6 versus $3 million in 2015.
The increase in the company’s revenue in the 2nd quarter of 2016 resulted from increased business activities, while the decrease in interest expenses in the 2nd quarter of 2016 was due to repayment of a loan to commercial bank.
At the end of December 2015, the company’s loan portfolio, before loan loss provision stood at J$304 million and grew marginally to J$305 million at the end of June. After loan loss provision of $70 million, it stood at $234 million as of June this year versus $241 million at December and is up from the $225 million at the end of March 2016. Cash on hand stood at $67 million while the amount borrowed fell to $127 million including overdraft balance of $38 million from $328 million at the end of 2015.
The funds being raised could propel loan growth significantly and with it profits particularly in 2017 as the funds would be available for a full year compared to a few months for 2016. Importantly, more funds will be available for the busy Christmas period. IC Insider forecast earnings for 2016 at of $59 million or 57 cents per share with earnings jumping sharply higher in 2017, if most of the bond funds are received and are on lent.
The company is not without risk and success will be highly dependent on management’s ability to make proper credit assessment and police tightly loan repayments by its clients.
Undervalued JMMB Group
JMMB Group traded 1,790,063 shares but fell 34 cents to $9.50 on Monday.
Total comprehensive income for period, amounted to $1.14 billion versus $894 million in 2015 and is a factor worth paying attention to as it gives a better indication of the performance of the group than the regular profit out turn.
The JMMB Group reported net operating revenue of J$3.42 billion for the first three months of the new fiscal year, reflecting a 9.9 percent increase compared to the corresponding period in 2015 and was due mainly to positive growth in net interest income, fee and commission income and foreign exchange margins from cambio trading.
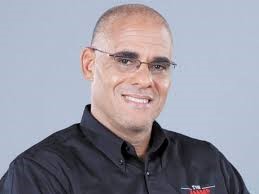
Keith Duncan, Group Chief Executive Officer of JMMB
Operating revenue grew in all the territories with 26 percent of operating revenue generated outside of Jamaica. Nevertheless, the Jamaican entities continued to post positive performance. In Trinidad and Tobago, the Group’s operations continued to move in a positive trajectory, reporting a 32 percent or J$150.2 million growth in operating revenue at J$614.6 million. The operations in the Dominican Republic also posted growth in operating revenue; up 22 percent or J$49 million to J$275 million.
 Operating expenses rose 14 percent to $2.58 billion a bit faster than a 10 percent rise in overall revenues net of interest cost, but if one off gains are adjusted for, revenues would have grown by 31 percent, much faster than operating cost.
JMMB Group’s asset base totalled J$245 billion, up J$22 billion or 10 percent relative to a year ago. The growth was due primarily to larger investment and loan portfolios. The investment portfolio increased by J$20 billion or 13 percent to J$171 billion. In addition, loans and advances, net of provision for credit losses was J$40 billion, up 21 percent or J$7 billion. Growth in the asset base was funded by customer deposits and repurchase agreements. Customer deposits increased by J$6 billion or 15 percent to J$46 billion, while repurchase agreements were 7 percent higher at J$156 billion.
Another big quarter for Jetcon
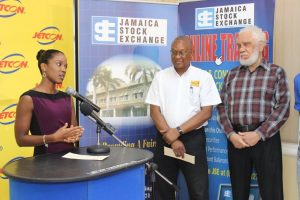
Sanya Goffe addressing the audience at the listing of Jetcon’s shares in March.
The company accounted $4.7 million in tax, in the first quarter but none in the second quarter, with the shares listing on the junior market in March, this year. Earnings per share ended at 12 cents versus 8 cents for the June quarter and 21 cents for the six months to June compared with 12 cents for 2015.
Having been listed on the junior market our profit will be tax free for 5 years. With just half the year completed, profit is 9 percent off from the after-tax profit of $40.3 million reported for the full 2015 financial year and the company seems poised to surpass the 2015 earnings in the September quarter, if recent trend for 2016 to date continues.
Revenues climbed 39 percent for the quarter to $194.9 million and 45 percent for the six months to $342.9 million. Gross profit margin declined to 18.54 percent from 19.24 percent in the quarter and 19 percent for the six months versus 18.38 percent in 2015. Sales are usually greater in the second half of the year than in the first half.
 In a release by directors accompanying the financials, the company stated that “Administrative and other costs rose by approximately $5.2 million due to listing on the market which accounted for $2.5 million while salaries adjustments accounted for $2.7 million of the increase. Part of the increase in salaries is directly tied to the increased sales that took place.”
“Sales in June were the highest for the half year with sales for July is ahead of June in volume and sales revenues. Bookings which have been ahead of 2015 for each month this year continues to be positive.”
Inventories stood at $236 million at the end of June, compared to $125 million in June 2015 and $84 million at the end of December last year. Supplies peaked in June and is slated to start to decline by the end July onwards to the end of the year as deliveries to customers exceed new inflows of cars. Payables increased as a result of increased purchase of motor vehicles.
Expansion for Paramount
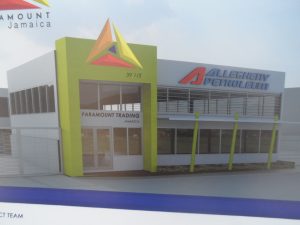
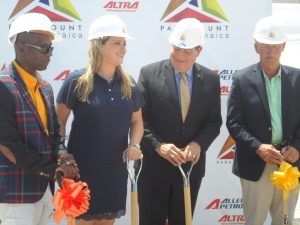 Allegheny Petroleum and junior market listed company, Paramount Trading joined forces to establish their jointly owned lubricant plant to be housed at 39 Waltham Park Road the same site as Paramount other operating facility.
The plant for which ground was broken in July, is expected to replace imports amounting to approximately US$4 million now being supplied directly by Allegheny Petroleum, according to Hugh Graham, Managing director of Paramount.
Establishing operations in Jamaica, adds more value and will allow for a greater customer reach and create greater margins than that which applies to imports. The initial investment is US$4 million and includes the warehouse, equipment, software and lab testing equipment. The venture will have the capability to test lubricants in use for customers in Jamaica rather having to send samples overseas for testing. There are plans to expand product range in the future and provide products for exports. The plant is expected to start production in January next, Graham confirmed with IC Insider.
According to Graham in 2012, when they listed on the junior market, Paramount had 36 workers and now has 76 employees and the number will increase to 100 employees, with the latest expansion.
The ground breaking ceremony was addressed by Minister of Finance, Audley Shaw, who indicated that this venture vindicated the decision of the government to provide the tax incentive for the junior market as well as the economic policies being pursued that is geared to encourage more production of goods in Jamaica as opposed to relying on direct imports.
Robin Levy, assistant general manager of the Jamaica Stock Exchange indicated that the company has done well since it has listed and said “since listing in 2012 the company has gone on record higher revenues and tripled profit with the stock price rising from $2.45 to just under $11.” Since the ground breaking, the stock traded at $11.50 and now has a bid at $12.
In the year to May, the company posted an 18.5 percent increase in profit, to reach $173 million, from sales revenues of $1.02 billion with other income accounting for $39 million for the year, up from $869 million versus $16 million in 2015, respectively. Administrative, selling & distribution cost rose sharply by 34 percent to $181 million as the wage bill and rental expenses grew appreciably.
 While profit grew in the year, segment results show mix out turn for each division. For 2016, Chemicals grew revenues by 12 percent and gross profit by 19 percent over 2015, for Construction and Adhesives, for the same periods, revenues grew by 59 percent and gross profit by just 6 percent. Manufacturing sales fell by 16 percent with profits remaining unchanged, while Transport enjoyed a 16 percent growth in sales leading to a 61 percent rise in profit and Lubricants sales climbed 403 percent with profits jumping 127 percent. Graham indicated to IC Insider that the fall in manufacturing sales is due to a customer reorganising their business. The data suggests that the new lubricant plant is likely to be the area of growth for Paramount.
In 2015, Graham indicated that a rights issue was likely, asked about that source of funding for the expansion, Graham stated “I can’t talk about that now,” he however, stated that “some other revenue announcement should be made soon.”
Sagicor Group flat Q2 profit
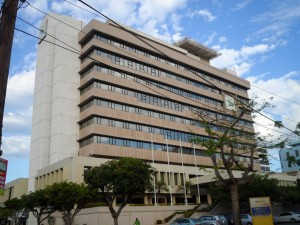
Sagicor Group HQ – the stock closed at $21.45 on Friday.
Total Comprehensive Income jumped sharply in the quarter to $5.7 billion from $1.9 billion at June 2015 and for the six months it stood at an impressive $8 billion versus $3 billion in 2015.
Expenses climbed 13 percent to $12.28 billion including administrative cost that rose 16.4 percent to $3.88 billion. Segment results show mixed fortunes, with Individual Lines slipping 9 percent to $800 million, down from $875 million, Employee Benefits jumped sharply by 49 percent to $1.87 billion, while Investment Banking grew by 6 percent, to $850 million. Commercial Banking fell 28 percent or $228 million to $585 million as write down of tax recoverable, took $250 million out of profits, in 2015 the group indicated that results for this segment was boosted by higher than expected recoveries on delinquent loans. Other segment jumped $220 million or 148 percent to $368 million while the company share of Sagicor Real Estate Fund contributed $153 million in the quarter and $329 million for the six months against no earnings in 2015.
Sagicor’s main focus is on the sale of personal insurance related products and banking, its success will be its ability to manage funds it receives and use in investment.
The group reported earnings of $2.51 for 2015 and with the performance this year to June, full year earnings should end up around $2.90, suggesting the stock should rise in the months ahead with the PE ratio at 7 times 2016 earnings versus an average of 9 for the main market. The stock last traded on Friday on the Jamaica Stock Exchange at $21.45.
At the end of June, equity attributable to stockholders climbed to $51.69 billion up from $46.57 billion, while total assets climbed 7.3 percent to $322.4 billion from $300.4 billion at the end of December 2015.
Outlook – “Our Group continued to produce good results in all areas. We are seeing the benefits of our business growth, digital and service-oriented strategies. We expect the second half year to be even better than the first,” Chairman, Danny Williams and CEO, Richard Byles, told shareholders, in the report of directors accompanying the financials.
Sagicor paid an interim dividend of $2.58 billion to stockholders or 66 cents per share, in April this year which is 69 percent higher than the $1.52 billion or 39 cents per share for the similar period in 2015. A second dividend is expected before the end of 2016. An interim dividend of 34 cents per share was paid to shareholders in November 2015.
Flat results, increased profit at tTech
tTech closed at $4.50 on Thursday.
Profit after tax, is up to $16 million from $12.4 million for the six months and $9.2 million versus $7.6 million in 2015, but for tax expense saved in 2016, profit for the year to date would be flat. Profit for 2015 was subject to $1.4 million in taxes and for the six months, $3 million. A sharp rise in operating expenses due to a 50 percent rise in staffing, pushed the spend by 54 percent to $50 million for the quarter and 36.4 percent to $91 million for the half year.
Earnings per share ended at 9 cents for the quarter and 15 cents for the half year and should end up around the 35 to 40 cents range for the full year based on the results to date. The strong revenue gain is a signal for growth going forward for the company.
Management stated that “the increase in revenue was due to growth in all areas of our services including the Consulting Division. Increase in expenses was driven primarily by increases in our workforce to increase capacity to meet the growth in demand. At June 30, 2016 the company had 31 full-time employees compared to 21 at the same date in 2015.”
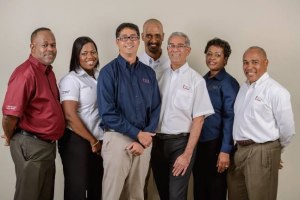
From Left: Mr. Hugh Allen, Resolution Manager and Executive Director; Mrs. Natalya Petrekin, Service Desk
opportunities for automation will be explored to facilitate increased efficiencies and improved service delivery.”
The company ended with cash and investments amounting to $115 million at June, up from $67 million at the end of December last year with net current assets ending at $130 million with payables at $34 million, while shareholders’ equity is at $146 million.
The stock traded as high as $5 on the JSE junior market today but fell back before the close to $4.50 for a PE of just over 11 times projected 2016 earnings. For investors will the strong growth continue and deliver increasing profit for them to buy and hold at these prices for long term gains.
Cargo Handlers’ share goodies
Cargo Handlers to split stock 10 for 1.
The shares now issued amounts to 37,465,830 units but the stock trades infrequently as very few are in the hands of the general public. The stock split is expected to enhance liquidity of the stock.
The stock last traded at $56 on the junior market of the Jamaica Stock Exchange having shot up from $46 after the announcement was made that the directors were meeting to recommend a split. There are currently ids to buy the stock between $60 and $64.01 for 10,877 units, the last offer was 919 units on at $66, at the close on Monday.
The directors declared an interim dividend of $1.35 per share to be paid on September 13, with the ex-dividend date set for August 17.
The company enjoyed a buoyant June quarter, with revenues rising 55 percent from $56 million to $87 million and for the nine months by 36 percent to $245 million from $182 million. Profit before tax rose to $53 million from $29 million in 2015 and after taxation, profit ended at $46 million from $29 million. For the nine months, profit rose from $108 million to $143 million before tax, with the 2016 results ending at $125 million after tax, there were no taxes in 2015.
Management attributes the strong growth in third quarter revenues and profit, to increased activity in the Montego Bay region and increased port activity, flowing from the conversion of the Jamaica Public Service power plant to LNG gas.
Earnings per share for the quarter ended at $1.23 and $3.32 for the nine months. Full year’s earnings should be just under $5 per share but scarcity of the stock is driving the valuation up.
Access post good Q1 results

Access Financial Services’ profit jumps 29% in Q1.
The company reported a moderate 10 percent growth in loan interest revenues to $301 million in the quarter over that of 2015. The loan portfolio for the June is 8.6 percent ahead of March, if the rate of growth continues, loans would end at $2.84 billion versus $2.1 billion as of March.
Total revenues moved by 10 percent from $315 million to $347 million for the June quarters while profit after tax for the quarter grew 29 percent to $146 million or 53 cents per share, compared to $112 million or 41 cents for the June 2015 quarter.
Cost was well contained at $184 million for the quarter, down from $186 million in 2015. Loan loss provisions fell from $54 million in 2015 quarter, to $43 million in 2016. IC Insider projects the provision to rise to $187 million for the full year, up from $184 million for the 12 months to March 2016, while earnings of $800 million or $2.90 per share are projected for the 12 months to March 2016, with growth to $4 per share or $1.1 billion in profits after tax, for 2017.
At the end of March, shareholders’ equity stood at $1.3 billion and borrowings at $1.1 billion with cash and equivalent at $299 million out of total assets of $2.7 billion.
The stock which remains BUY RATED last traded at $17.50 giving it a PE based on the above forecast at an attractive 6.