Simply Impressive

Honey Bun shot up by more than 500% in 2016 shortly after stock split.

Honey Bun shot up by more than 500% in 2016 shortly after stock split.

Junior market listed bakers, Honey Bun, is enjoying a glorious period of surging revenues and profit that fueled a huge jump in the stock price of 355 percent for 2016, after rising over 500 percent, earlier in the year.
In continuation of a successful year, revenues climbed 36 percent in the third quarter of financial year to June, spawning a 124 percent increase in profit before taxes to $38 million over the June 2015 quarter. Revenues climbed 35 percent to $903 million for the nine months to June, up from $672 million in 2015 while profit jumped 109 percent to $138 million before tax and $132 million after tax of $6 million.
Gross profit for the nine months climbed at a faster pace than revenues, at 40 percent while for the quarter, gross profit rose 34 percent, just below the growth in revenues for the quarter. Expenses excluding cost of sales, rose even slower than revenues, at 20 percent, with administrative expenses rising sharply by 33 percent to $147 million and selling and distribution costs increasing by 10 percent to $104 million, while depreciation rose by 4 percent to $28 million. For the June quarter administrative, selling and distribution expenses rose at a slower pace than for the nine months, at 12 percent.
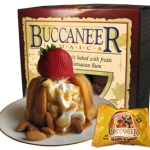
One Honey Bun's Products.

One Honey Bun’s Products.

The company generated gross cash flows of $171 million for the nine months, before expending $75 million on the acquisition of property, equipment and fleet. Honey Bun is in a healthy state with cash balance and investments at $104 million after the company repaid $38 million in long term loans, leaving loans at $16 million. Current assets stood at $212 million and current liabilities ta $71 million. Shareholders equity climbed to $491 million.
The Company that listed on the Jamaica Stock Exchange Junior Market in June 2011, is now subject to taxation on profit for the next 5 years at 50 percent of the normal corporate income tax rate of 25 percent.
Earnings per share for the quarter came in at 8 cents and 28 cents for the nine months. IC Insider projects 34 cents or $160 million for the full year to September, with $147 million or 52 cents per share projected for 2017. The stock traded at $5.60 on the Jamaica Stock Exchange junior market for a PE of 16.5 times 2016 earnings, making it one of the highest valued stock on the market.
The stock was accorded a BUY RATED ranking in November 2015 but has since been placed on a watch list when it shot to over $7 per share.
Loans to surge at Jamaica National

JNB HQJamaica National enjoyed a 10 percent increase in loans at the end of March this year over March 2015 to $66 billion inclusive mortgages that rose from $56 billion to $61 billion. Based on loans approved and not disbursed at the end of March, the loans portfolio seems set to climb at a much faster pace than for 2016 fiscal year.
According to the societies’ financials, loans approved but not yet disbursed jumped by a sharp 168 percent to $7.36 billion or 12 percent of outstanding loans, up from $2.75 billion or 4.9 percent of the loan portfolio at March 2015.
Jamaica National, Jamaica’s largest building society had a mix fortunes in fiscal year 2016 with assets climbing by 8.8 percent to $181 billion. Investment securities made up the bulk of the assets at $94 billion. Equity capital stood at $31.2 billion and savers deposits of $101.4 billion up from$90 billion in 2015.
The society suffered a sharp drop of 44 percent in profits to $1.42 billion from $2.53 billion in 2015. For the year to March 2014, profit jumped to $2.3 billion from only $908 million in the previous year.
Contributing to profit for the year was net interest income growing from $8.5 billion to $8.8 billion, other operating income that fell from $6.2 billion to $5.9 billion and operating expenses climbing from $11.8 billion to $13.3 billion.

Huge 25% jump in Q3 results for NCB

NCB posted a 16% jump in nine months' profits & declared a dividend of 50 cents.

NCB posted a 16% jump in nine months’ profits & declared a dividend of 50 cents.

Jamaica’s National Commercial Bank (NCB) posted a strong increase in profit after tax, for the June quarter with earnings jumping 25 percent or $789 million over the 2015 June quarter, to $3.9 billion. For the nine months to June, profit is up 16 percent to $9.9 billion compared to $8.6 billion in the 2015 period.
Earnings per share ended at $1.88 for the quarter, up from $1.29 in 2015 and for the period to June $4.31 versus $3.48, with full year earnings are set to exceed $6.
The gains were helped by an 11 percent climb in loans and advances to reach $180 billion and a reduction in a number of areas of cost, including a fall in loan loss provisioning to $157 million in the quarter from $472 million in 2015 and for the nine months from $1.4 billion to $904 million.
Customer deposits increased by 18 percent or $38.9 billion over June 2015 to $256 billion.
Total operating income net of interest cost and fee and commission expenses increased to $12.76 billion from $11.68 billion, for the quarter and to $38.4 billion compared to $35.3 billion for the period to June. Net interest income increasing by 8.8 percent, or $1.7 billion, due to growth in the net loans and investments and a reduction in interest expenses driven by a decline in funding costs.
NCB management stated that for the nine months, net fee and commission income increasing by 10.3 percent, or $743 million, mainly due to credit related fees from growth in the loan portfolio, higher volumes of point of sale transactions and unit trust commissions arising from growth in the portfolios. Premium income grew by $388 million, or 6.8 percent, due to higher levels of life insurance and annuity contracts. Gain on foreign currency and investment activities increasing by 10.8 percent, or $305 million to $3.1 billion.
Overall expenses grew slightly from $7.46 billion to $7.64 billion for the quarter and for the nine months by 3.8 percent from $24.1 billion to $26 billion well below the increase in revenues.
NCB declared an interim dividend of 50 cents per ordinary stock unit payable on August 29, to stockholders on record as at August 15. NCB remains an IC Insider Buy Rated stock. In Trading the stock closed at $42.50 today on the Jamaica Stock Exchange for a PE of 7 and on the Trinidad and Tobago Stock Exchange at TT$2.75 or the equivalent of J$52.

Carib Cement bad news say buy

CCC GteJamaica’s sole cement manufacturing company Caribbean Cement, reported a fall in profit from $621 million in the June quarter of 2015 down to only $221 million and for the six months to June $1.05 billion versus $869 million.
Investors seemed to have focused more on the fall in the quarter than on the details of the results and the clear message sent by them. As a result, the stock was sold down to $19.25 from $23 the prior day, with very few buyers at the close, but investors who sold were making a bad decision. This is a classic case of bad news is indeed good news. For one, revenues climbed 9.6 percent in the quarter and 10.3 percent for the half-year but local sales of cement are up a very strong 27 percent. “Despite a reduction in export cement and clinker volumes by 8 percent and 77 percent respectively, total revenue increased by $777 million. This was mainly due to an increase in domestic cement volumes by 27 percent arising from increased projects and strong retail demand. Improvements in operational efficiencies, effective control of fixed costs, lower financing costs and lower energy costs, contributed to the improvement in earnings before interest, tax, depreciation, amortisation, manpower restructuring costs,” the directors’ report to shareholders stated.
CCC fact - 14Importantly, the cement company took a charge for manpower restructuring, amounting to $421 million, a huge positive development and augurs well for improved profit margin and increased profits going forward. In addition there is a charge for excess inventory amounting to $400 million, this is one off and therefore unlikely to recur. Stripped of these costs, earnings would be up by 63 percent to $1.16 million before tax compared to $708 million in 2015 that includes one off income of $168 million for the quarter and pretax profit of $2.1 billion versus $996 million in 2015.
Not only will the cost for redundancy not recur for the current set of staff being severed, it should results in savings in a year, in the region of the sum expended.
During the twelve months to June, the company repaid Trinidad Cement, its parent, loans and other debt $1.6 billion leaving only $556 million more to be paid. Cash funds were left at $788 million after more than $600 million was added to fixed assets since June 2015. At the pace profits are coming in the accumulated deficit of $4.6 billion will be wiped out in 2017.
IC Insider’s forecast for full years earning form normal operations is $4.75 which excludes the one off cost leaving the stock strongly in the buy column. The stock is listed on the main market of the Jamaica Stock exchange and closed at $22 on Friday.

Profit jumps 81% for Kremi

Kremi GapntProfit jump 81 percent to $71 million for Caribbean Cream in its latest quarter to May this year, the company reported, from a rise of 9 percent in sales to $316 million resulting in earnings per share of 19 cents.
Gross profit climbed faster than revenues by 24 percent to $138 million as production cost dipped slightly to $177.5 million from $178.4 in 2015, as the company continues to benefit from lower prices of sugar and milk based major production ingredients and from energy savings.
Administration cost declined by $2 million to $54.3 million while selling and distribution cost came in at $10.8 million from $11 million in 2015 and finance costs fell to $3 million from $4.6 million as the amount of loan funding declined from $140 million to $120 million, Gross cash flow amounted to $85 million up from $53 million in 2015. Having funded loan repayment and acquisition of fixed assets, the cash inflows helped push cash at the end of 2016 quarter to $194 million, from $50.75 million at the end of May 2015. Shareholders’ equity climbed to $509 million at the end of the quarter.
The company has declared an interim dividend of 5 cents per share or $19 million payable in September. The stock traded at $5.50 but should head higher with earnings projected by IC Insider at $1 per share for the full year.

Profit drops 15% at Prestige

Prestige Holdings brand - TGIF

Prestige Holdings brand – TGIF

Profit after tax fell by a moderate 4 percent at the Trinidad based Prestige Holdings, for the first half 2016, to reach $23 million, from $23.9 million in the previous year. That disguises a much sharper fall in profits in the second quarter, with profit falling 14.5 percent from $12.25 million in 2015, to $10.7 million, from revenues that increased by a mere 1.6 percent to $240 million for the quarter to May 2016 while group revenue increased 2 percent to $478 million for the six months.
Gross profit hardly grew as is the case with sales, moving from $169 million in the 2015 six months period to $171 million in 2016 and in the May quarter, from $84.4 million to $84.7 million. Administrative expenses moved to $36.4 million from $32.2 million for the year to date and from $15.75 million in the May 2015 quarter, to $17.67 million, for 2016, but other operating restaurants expenses moved to $100 million from $99.9 million in 2015 six months period, while that for the May quarter, was up $1 million to $51.25 million.
Earnings per share ended at 37 cents, for the half-year and 17 cents for the latest quarter. Full year’s earnings should end at around 90 cents per share, the new restaurant being opened could change the end results.
“These results were generated from an average number of 113 restaurants. Performance in the 2nd Quarter was mixed with our KFC and Pizza Hut brands showing greater resilience to the economic headwinds, foreign exchange challenges and a persistently difficult labour environment; and our TGI Fridays and SUBWAY brands less so. Despite these macro-economic factors, we recognize that there are opportunities for improving the performance of these brands and we are focused on doing so,” Christian Mouttet, Chairman of the company reported to shareholders in the commentary accompanying the quarterly report.
The Six results came against the background of a sluggish Trinidad economy, but the future could be spiced with expansion plans.
“At the end of the quarter, we opened a new Pizza Hut restaurant at South Park in San Fernando, which has been well received. We expect to open our first Starbucks restaurant by the end of the 3rd Quarter and another two restaurants by the end of the financial year. Significant work is underway for the establishment of this brand in the Trinidad and Tobago market,” the report by the company to shareholder also stated.
The stock traded at $10.90 on the Trinidad & Tobago Stock Exchange on Friday at a PE of 12, based on this year’s projected earnings.

More 1834 Investments delays

Glnr 2Having not published the December 2015 quarterly report as required by the Jamaica Stock Exchange rules, 1834 Investments (formerly The Gleaner Company Limited) who previously advised of a delay in reporting the March 2016 before the end of June, now promises the release of the audited accounts of the company by July 31, 2016.
The companies release comes against the background of an IC Insider report on the further delay in a posting on Tuesday.
According to the release which was issued and posted July 5, 2016 at 3:57 pm, the company stated, “as previously advised, the restructuring activities of the company during 2015, coupled with the change in financial year-end, and close of the merger transaction with Radio Jamaica Limited in March 2016, have necessitated an extensive revision to how the company’s accounts are compiled, reviewed and presented in order to distinguish between the continuing operations of 1834 and the discontinued media operations.”
“1834 Board is aware that shareholders are anxious to see the company’s financial results; however, 1834 is taking time to ensure the total accuracy of the accounts.1834 also advises that the audit review exercise is substantially complete and every effort is being made to finalize the accounts for release in advance of July 31, 2016.”
Radio Jamaica last week also indicated that their 12 months results are further delayed resulting from the merger.
Whether, the companies make the revised deadlines, the Jamaica Stock Exchange is not looking pretty in the messy situation of the failure for the Gleaner to release the 2015 numbers. The question now to be asked, should these companies shares still be trading with an unclear financial picture, occasioned by the long delays and the uncertainty resulting therefrom.

Where are the 1834 Investments results?

Gleaner & RJR execs signing merger agreement earlier in 2015

Gleaner & RJR execs signing merger agreement earlier in 2015

The rules of the Jamaica Stock Exchange require, listed companies to submit quarterly interim financial report within 45 days of each quarter. In the case where a company opts to release an audited account within 60 days of the year-end, they can opt in lieu of a quarterly report within 45 days.
1834 Investments Limited (formerly The Gleaner Company Limited) did not release the usual December quarter report as such investors have been deprived of important information on the company. The stock exchange has fallen down badly on this one in not requesting it. No good reason has been given why it was not released.
Apparently the exchange regulatory arm expected that the 15 months report to March this would have been released to let the matter go away but it has not. First out of the block towards the end of May, 1834 Investments advised the Jamaica Stock Exchange that the Audited Annual Financial Accounts for March, 2016 will be late and unavailable for publication by May 30, 2016. 1834 anticipates that it should be available for publication on or before June 30, 2016. Bad news for investors and bad news for the capital market. The matter gets worse, the end of June has now gone and with July well advanced but there are no results released and no advisory on the JSE website or in the newspapers as to the new deadline. Nearly seven months have elapsed since the last report was released.
In the past several companies have changed their year end, as recently as late last year Desnoes & Geddes and Access changed their but provided investor with results for all relevant quarters, but the Gleaner Company who changed theirs to March from December did not do so.
It is well past the time for the Jamaica Stock Exchange act to protect the investing public.

Caribbean Producers profit gets hit

CPJ set to be hit by asset write down

CPJ set to be hit by asset write down

Caribbean Producers (CPJ) seems set get a big hit for the financial year ended June, this year. According to a release to the Jamaica Stock Exchange today the company release information on the impact of what they say are unregulated players in the market.
(CPJ) says it “has taken the decision to issue a preliminary disclosure of likely impairment to their net profit in the financial year ended June 30, 2016”
“CPJ advises that the presence of unregulated players in the market continue to create an unequitable environment for the company to compete against products of questionable origin and repute. This has resulted in a review of the implications for CPJ’s business model and hence the following prudent management decisions will be made: A write-down of inventory that has become aged or obsolete that cannot be competitive against unregulated players. An increase in tax provision in anticipation of realignment changes to CPJ’s business model.”
“CPJ views these issues as material primarily for the Fiscal year ended June 2016 and anticipates the authorities will aggressively target the unregulated players. CPJ states however, that the new fiscal year will concentrate on rationalizing non-core businesses and a realignment to address the year-on-year increase in costs associated with their rapid growth and new investments while focusing on protecting their profitable lines of businesses.”
CPJ reported lower profits in the March 2016 quarter of US$643,000 versus US$1.286 million in the similar period in 2015 with the nine months results being just ahead of that for 2015 at US$2.4 million.
While revenues were moderately up, by US$1.3 million in the quarter, to US$24.38 million and nearly US$5 million for the nine months to March,to US$69.8 million, selling and administrative expenses jumped by $1.3 million to US$5.47 million in the quarter and US$2 million for the nine months.
At the end of March, inventories totalled US$25.4 million, even a small write of say 5 percent, could do major damage to the 2016 profit.
The company’s shares that are listed on the junior market of the Jamaica Stock Exchange, traded a small volume today at $4.68.

CAC profit edges higher

CAC logo 12-15Revenues climbed just 5 percent to $252 million and after tax profit rose 16 percent to $21.8 million for junior market listed CAC 2000, but pretax profit was slightly lower than for 2015 with $23.6 million reported for 2016 April quarter versus $24.7 million for the similar period in 2015.
For the six months to April, revenues climbed 16 percent to $481 million and after tax profit rose 20 percent to $48.5 million from $40.6 million in 2015. Gross profit rose 19.7 percent to $182 million for the six months and 8.9 percent to $96 million for the second quarter.
Selling and distribution cost fell from $10 million in the 2015 second quarter to $6 million in 2016 and for the half year, from $20 million to $14 million. Administrative cost rose from $46 million for the second quarter to $63 million and for the six months from $83 million to $114 million. The increase is “due to our investment in additional resources to support the continued growth in business,” Steven Marston, the chairman of the company stated.
The increased cost, pushed profit before other revenues to $27 million for the 2016 quarter from $34 million in 2015 and for the year to date, from $50 million to $54 million.
Earnings per share ends at 40 cents for the half year and 18 cents for the quarter. The stock trades on the Jamaica Stock Exchange junior market at $6.70 at a PE around 8.7 times this year’s earnings, putting it at 21 out of the 29 junior market listings.
At the close of April, CAC had cash of $188 million, total current assets of $771 million and current liabilities of $382 million. Borrowed funds stood at $156 million with equity capital at $382 million.