New additions to ICTOP10 & TOP15

At the end of the week when the Junior Market index hit another record high in closing over 4,200 points for the first time, there was no exit from the ICTOP10 Junior Market listing but there is one change to that of the Main Market as Caribbean Producers returns to the TOP 10 while Transjamaican Highway slips out.
This is the last week of publication of ICTOP10 that is based on 2021/22 results. The next report will the TOP10, incorporating 2022-23 earnings, currently showing the average for the Junior Market at 12.6 and the Main Market at 13.1. These are well off the current PE for the Junior Market at 22.6 times 2021-22 earnings and the Main Market at 16.1.
For this week only, the current compilation of the TOP 15 stocks based earnings for 2022-23 for now till March 2023 based on the latest stock prices, are shown along with the TOP10 for 201/22. The current TOP 15 stocks show changes to the list published in January, as price changes and earnings computation for some stocks have changed, while five stocks dropped out of the original list for the Main Market stocks, with five new listings. Dropping out are Radio Jamaica, Scotia Group, Grace Kennedy and Jamaica Broilers while in the Junior Market, Spur Tree dropped with the price moving from $1 to $3.55, Lasco Manufacturing also dropped out and Dolphin Cove that moved from $15 to $27. Coming into the TOP 15 are, iCreate, Paramount Trading and tTech.
The Junior Market movement this past week pushed the gains for the year to date to 22.7 percent, still some distance from the 60 percent forecasted by this publication at the start of the year, but just around 25 percent of the year has elapsed so far.
In the ICTOP10 listing this week, the big move was a 23 percent rise in the price of Tropical Battery, followed by an 11 percent gain for Lasco Manufacturing to end at $5 and 6 percent increase by Iron Rock Insurance. AMG Packaging slipped 11 percent as talk in the marketplace is that they are facing challenges with some raw material supplies that will affect production. Lasco Distributors fell 5 percent followed by Access Financial and Caribbean Assurance Brokers down 4 percent each. In the Main Market, Jamaica Broilers rose 9 percent followed by JMMB Group up 5 percent.
This weeks’ Junior Market index close, is 154 points higher than the 4,052.19 points at the end of the previous week, helped by the strong gains in Caribbean Cream up 41 cents, Dolphin Cove, up by $2.70, Express Catering 75 cents, Fontana 26 cents, Future Energy Source 51 cents, Honey Bun 55 cents, Jamaican Teas 18 cents, MailPac 47 cents, Main Event 62 cents and Tropical Battery 46 cents. Meanwhile, the Main Market continues to consolidate around support of 440,000 points for the All Jamaica Composite Index, even as it closed the week just under, at 435,748.05.
Most of the Junior Market TOP 10 have full year’s results due in months and the lack of final results seem to be sapping buying interest at this time.

ICTOP15 main market stocks for 2022-23

Potential gains for the TOP 10 Junior Market stocks stand at 107 percent and the potential gains for Main Market stocks end at 134 percent.
The average PE for the JSE Main Market TOP 10 average PE is 8.8 well below the market average of 15.8, while the Junior Market PE for the Top 10 is at 9.8 versus the market at 22.6.
ICTOP10 focuses on likely yearly winners, accordingly, the list may or may not include the best companies in the market. ICInsider.com ranks stocks based on projected earnings to highlight winners from the rest, allowing investors to focus on potential winning stocks and helping to remove emotional attachments to stocks that often result in costly mistakes.

ICTOP15 Junior Market stocks for 2022-23

IC TOP10 stocks are likely to deliver the best returns up to the end of March 2022, ranked in order of potential gains, based on likely increases for companies taking into account, earnings and PE ratios for the current fiscal year. Expected values will change as stock prices fluctuate and result in weekly movements in and out of the lists. Revisions to earnings are ongoing, based on receipt of new information.

Persons who compiled this report may have an interest in securities commented on in this report.

10 Junior Market stocks for 10 years run

Most Junior Market listed companies don’t have the depth of management that most Main Market companies have. What most may lack in Management they make for by their agility and ability to grow faster than the more matured counterparts in the Main Market and this feature can deliver above average growth for stock prices. This factor alone can determine winners from losers in business.

Junior Market trades

Some elements are common to companies in both markets; as such, the investors who don’t have the time and inclination to monitor their investments regularly may want to invest for the long haul with the expectation that their investment will grow appreciably over time. There are some factors to consider in investing long term, these include continued growth of companies, inflation, possible shifts in government policies as well as social and economic policy changes that can affect investment returns in the short and long term.

Over the next ten years, many of the companies in the Junior Market could see changes in the leadership of many of the Junior Market companies and change in ownership as some of the majority owners retire. The ownership shift may be negative or positive, but it is a major factor. Continuity of ownership is a major factor to consider and this is more critical for Junior Market companies, with the largest shareholders being the lead executive management.

Access Financial Services is the first company to list on the Jamaica Stock Exchange Junior Market and enjoyed years of growing revenues and profit, but the stock price declined sharply in 2020 and 2021 as profits fell in the fiscal year 2020 and 2021 due to heightened provision for doubtful loans and slowdown in lending. Corrective measures were put in place and loans and profits are growing again, with improvement in the economy and a reduction in unemployment. The company stands a great chance of continuing to grow to provide the unbanked with alternative financing. The potential for tapping into this underserved area would position AFS as an interesting company to follow over the next ten years.

Elite Diagnostic – Health care services are a never ending need and demand will continue to grow as the local population ages and individual wealth improves. The company recently expanded from one location to three. They encountered major operating problems with machinery that increased cost and negatively affected revenues but now seems over that, with revenues growing again. They have plans for another branch to be established, which is delayed for the time being, but they added to machinery at the Hope Road branch to meet increasing demand. This company should be able to innovate and stay relevant for years to come. The company has the potential to expand into other areas of the country, bringing services closer to the consumers and generating higher income and profit.

Express Catering provides services directly to the tourism industry, with its restaurant operations housed within the Sangster International Airport. The future is tied into the growth in that industry, seemingly poised for more growth with the continued expansion of hotel rooms on the country’s north coast. The airport in Montego Bay is expanding and will provide opportunities for greater expansion for the company. Now focused solely on Montego Bay but could well move into Kingston, bringing additional growth possibilities.

Fontana stock is richly priced currently, as such, the time may not be right to buy into it as it could well fall back in price. It stood the test of time and seemed set for the next level of expansion and performance. It possesses good management has room for expansion by adding new products or acquiring others pharmacies as current owners of other existing pharmacies retire. A new branch is planned for the Portmore to come on stream in late 2022. The area with a growing population in Jamaica and therefore company’s expansion should attract good and profitable business. Spanish Town, another area, earmarked, with Montego Bay, could follow. The company is well positioned to acquire the many family owned pharmacies when the owners decide to retire.

General Accident has an excellent track record of growing the business and has adequate liquid funds to fund expansion and meet its operating commitments. The Jamaican operation is very profitable. Recently they expanded into Trinidad and Barbados, which could add to profits in 2022 but will be highly beneficial to the growth in revenues and profits in the years to come. This expansion will result in reduced reinsurance costs as the company spreads the risk over a wider geographical area. Further regional expansion is expected and will improve revenue and profit growth and swell cash funds for continued attractive dividend payments leaving sufficient amounts for investments and helping in reducing reinsurance costs. Guyana is growing strongly from oil production and will be enticing for the company to expand into that market, either directly or through one of the entities in the eastern Caribbean.

Fosrich has diversified into manufacturing pipes and has also gone into refurbishing electrical transformers, two new areas that it has a competitive advantage and is generating profits from. These ventures resulted in diversification away from being solely a retailer in the construction and energy sectors. With a growing Jamaican economy, that company will find room to increase revenues and profits as the years roll on and sales within the region.

The Beechwood Av. gas station

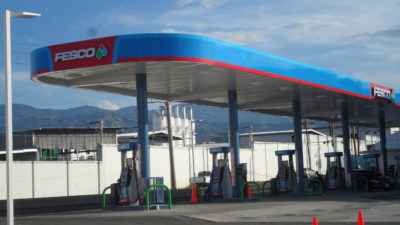
Future Energy is relatively a small player in the sector and has much room for growth, with only 16 service stations under its brand. The company is branching out into LNG and LPG gas sales to expand revenues in the future. The company plan to grow the number of service station under its name to 22, within three years, including one more to be owned and operated by the company. The great scope for expansion across the country makes FESCO one to watch over the next ten years as it could expand service stations in many more areas within the country. The stock is currently highly overvalued, and any investment should await a big pullback in price.

Honey Bun has made great strides since it was listed on the Junior Market in 2011. In 2009 sales were $404 million and has climbed to $1.67 billion in 2020 and rose climbed 28 percent to $2.145 billion for the 2021 fiscal year, with profit before tax moving from $191 million to $290 million. The impressive growth continued for the first quarter to December last year, with a net profit of $45.5 million that rose 31 percent above the prior year from sales that grew 44 percent to $665 million over the prior year. The company enjoys good Management that is expected to continue guiding the operations successfully, resulting in increased revenues and profit at attractive rates.

Jamaican Teas.

Jamaican Teas is a diversified group and continues to add new products. Exporting has been a strong growth area, with North America and the Eastern Caribbean being big markets for them, with sales exceeding those on the Jamaican market. The group spun off its investment arm into a separately listed company, allowing for greater focus on an area that has been very profitable for them. The manufacturing arm is to be spun off into a separate company that will allow for greater focus on that operation and provide greater exposure for the Caribbean Dreams brand. The group is unique amongst the Junior Market companies due to its diverse business. The strong and continued growth in exports is a great asset that is expected to provide a good basis for continued growth. The group is cash flow positive and possesses the ability to expand from mergers and acquisitions. The investment arm offers good prospects to add to profit going forward.

SOS anticipates maximising profits from every business line in 2022

Lasco Manufacturing is a low cost manufacturer with room for expansion either by producing its own brands or products under license from others. The business is cash flow positive and is building up cash at a healthy pace, with loans taken on to expand the factory almost fully paid off. They are in a good position to acquire brands or other entities and do production for third parties. It could be the subject of an acquisition by others, considering the main owner cannot be very far from retirement.

Stationery and Office Supplies is more than the name implies. While stationery and office equipment are the main lines, it also has a book manufacturing business that manufactures exercise books for children’s note pads. It also operates a paper shredding business with banks being clients of theirs and other entities, which is a high profit margin part of the business. They have stood the test of time and seem set for the next level. They possess good management that will deliver strong gains in the years ahead. The company posted its best fourth quarter results in the past year and that performance is said to have carried over into 2022, with revenues for the first two months running ahead of 2021. Looking forward, expect to see expansion by acquisitions and adding new products.

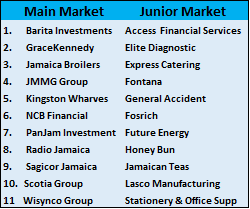
10 JSE Main Market stocks + 1 for 10 years

Some investors have time and inclination to monitor their investments regularly, but the vast majority do not. In the latter case, investors want to invest for the long haul, expecting that their investment will grow appreciably over time.
There are many factors to consider; these include continued growth of companies, inflation, possible shifts in government policies, and social and economic policy changes that can affect investment returns in the short and long term.
Junior Market stocks have some features that investors should pay observe. Most Main Market stocks have controlling interest that is likely to ensure continuity of ownership for years to come. The same is not so for Junior Market companies where there are few companies where controlling ownership is assured long-term.

Barita public stock offer pulled money away from other JSE stocks.

Barita Investments – Bankers are not supposed to be bright; they must be careful; this is an adage within the financial community worldwide. Tell that to the new management at Barita. Maybe if they were told, they might have avoided the negative comments they had to face in 2021. The directors can take comfort that JMMB Group suffered years of rumours about imminent failure, but they persevered and have prospered regardless and are now highly regarded. Barita stands an excellent chance of doing just that.
The recent focus on Barita is partially due to the current management taking a sleepy company and aggressively expanding into new and profitable areas and seems to be disrupting the status quo. They are aggressive and disruptive and are willing to go into areas with good growth potential when others take a more conservative posture. This approach is not risk free, to date, they seem to have prospered and their shareholders love it, having a rich stock price and healthy dividend payments. Additionally, Jamaica’s financial landscape is changing and providing increasing opportunities for growth of newer financial products. Barita has grown based on an increased capital base that stands them in good stead to prosper if management handles the resources at its disposal well. The company could be a significant player in financial services in the next ten years. They have taken a posture of paying out most profits and then going back to the market for added capital. That formula has worked well so far and has rewarded shareholders positively.

GraceKennedy has diversity in products, services, and geographic locations, making them one for the future, with a relatively significant presence in the USA and UK markets. They can enjoy good annual growth for years to come. The diversified product line put them in good stead to benefit from what seems set to be a reasonable period of economic growth for Jamaica. The Group has been acquiring new entities to expand the operations and geometric growth; this will give them increased bargaining power that can lower costs and drive revenues. Investors should not ignore the value of the Grace Brand will continue to be more valuable as the Group continues to make inroads into the international market. Currently, the stock is undervalued. Investors who can wait for the payoff could benefit from unlocking value down the road.

Jamaica Broilers’ product demand and global diversity will see them making money and providing good investment returns. Expected growth in the local tourism sector and the company’s efforts to expand its reach in the US market should augur well for investors from a company that is well managed and produces products that are in high demand in the local market. The negative is the politically sensitive nature of the main product. Management has been able to navigate such challenges and prospered over the years and should be able to do that in the future with their strong links to the farming community.

JMMG Group stock is severely undervalued currently. In addition, regional diversification, the variety of products and services it offers the public, and technology will drive revenues for the next ten years. The company has operations in the Dominican Republic, which is an excellent base for them to continue strong growth in that market with a population of 11 million, nearly four times the size of Jamaica. There is room for remarkable growth in that market that is not a financially developed market like Jamaica. Their banking arm in Jamaica and Trinidad is relatively small and they could enjoy above average growth that would be good for increased profit in the future.

Kingston Wharves has been around for decades and is highly profitable. It controls a significant portion of the logistics and distribution chain for imports and transhipment business, making them one to watch with growth expected in the Jamaican economy and growth in the transhipment. They should grow even faster as they cater to the local market and the expanding transhipment of goods within the region.

NCB Group stumbled in 2020, with the advent of the COVID 19 pandemic that saw major dislocations in businesses in Jamaica and worldwide, including the closure of the tourism industry. The Group suffered from a high degree of nonperforming loans, which is provided against and losses in the investment portfolio. The fourth quarter results for the just concluded year to September show that the worse is behind them and they should see growth in earnings for 2022. The Group is spread throughout the Caribbean and is involved in commercial and investment banking and insurance. Strong growth going forward will be dependent on a buoyant Jamaican economy and, to a lesser degree, that of Trinidad, where Guardian Holding is headquartered. Along the way, investors can expect a good level of dividends as compensation for waiting. The stock is currently in demand, but now could be the best time to start accumulating it.

Stephen Facey Chairman & Paul Hanworth Chief Operating Officer

PanJam Investment spans an array of activities from property development and ownership, many of them in prime areas in Jamaica, Investments, a significant owner in Sagicor Group and hotels. They are currently pushing into property investments in downtown Kingston and Montego Bay, the latter to be a hotel in the Montego Freeport area geared to business visitors. Buying into PanJam gives investors a strong involvement in Sagior Group, with the company owning around 30 percent of the shares. The Group has a long history of good performance and the suite of assets and quality management place them in an excellent position to grow at an attractive pace over the next ten years. While at it, don’t forget the heightened level of inflation that is currently afoot worldwide. PanJam, with its real estate and stock market portfolio, is well positioned to generate positive returns form as a result and protect investors against losing value in their investment in the company.

Radio Jamaica has lots of scope to grow revenues that will increase as the economy grows and swell profits as most of the revenues will fall to the bottom-line as operating costs are partly fixed. Most investors continue to focus on the old RJR but fail to recognize the Group’s invaluable assets, including the highly watched and profitable television station. The digital footprint is not to be ignored, with the Gleaner’s website being a big winner in the future, with the RJR site following. There are many developments taking place within the Group that will add to revenues and profit in the future. The digitization of television will create more flexibility in targeting markets with the signals and allow for expansion and increased income from the offerings it currently owns. Investors can look forward to reasonable dividend payments as profits grow in the future.

Sagicor Group & PanJam hit new closing highs.

Sagicor Jamaica is historically a strong performer that will benefit from continued growth in the Jamaican economy and buoyancy in the financial products that provide high returns. Apart from life insurance, they are involved in Health insurance and general insurance, investments, investment brokerage and banking. They control a sizeable portion of the local market and have a presence outside of Jamaica.

Scotia Group has had a long history of growing profits and dividends, with the stock price delivering attractive gains to investors over the years. In more recent years, things have not all gone well for the Group, with significant shifts in the financial market as new players and products came into the market and increased aggressiveness from the market leader NCB. The Group is now focusing on restructuring its branch network that will lead to lower costs while loans will be growing and driving interest income to help add to profits. The recent increase in interest rates will be highly beneficial to the Group. They will be generating more revenue from the government bonds as interest rates get some elevation from the Bank of Jamaica’s recent moves.

Wisynco Group is one of Jamaica’s larger manufacturing and distribution companies. The company has accumulated a wad of cash and will continue to do so with a very profitable operation that generates positive free cash flows. The growing buildup of cash places them in a healthy position to expand the group. The Group is involved in the manufacturing and distribution of products mainly for the local consumer market. It is a significant supplier to the tourism industry, with around 15 percent of the company’s goods. The sector continues to see growth with new hotel rooms being built and plans for more to come on stream in the future. It does not hurt with the company having a good management team, one of the most important elements in ensuring continued success in the business into the future.

10 stocks for 10 years

In the world of investing, it would be nice to find big winners at all times and invest in them just before their prices explode; that is not how stock markets work. Most investors need to buy and wait, to be rewarded with much higher prices later on. History is replete with many examples that show patience paying off handsomely.
In more recent times, some investors are demonstrating levels of exuberance in buying some stocks at excessive values that will take a long time to generate a reasonable return on investment.
In Jamaica, over the past few years, there are several stocks that recorded huge gains, allowing persons who hold them for years to make a bungle. One of the most celebrated is Lascelles DeMercado is no longer listed on the Jamaica Stock Exchange having been acquired by Angostura in late 2007 for the equivalent of $643 or US$10.65 per share valuing the company at $61.7 billion. The stock traded at $4.25 (the equivalent of 10.5 cents) in 1983, with 2.4 million shares issued, valuing the group then at just $10 million and it gained 6,000 percent between 1983 and 2007. In other words, a $10,000 investment in 1983 would be worth over $6 million in 2007. How many persons saw that coming? Not many but some seasoned investors did. But Lascelles is not the only stock on the local market to provide rich rewards for Investors.
What the information above shows is that long term investment can be very rewarding. This is especially so for persons with limited time to spend monitoring their investment on an ongoing basis.
In 2017, this publication recited portions of an article captioned “Teachings from silly Unilever Investors.”  “In 2013 ICInsider.com posted a report on the Unilever Caribbean, a company based in Trinidad and traded on the country’s stock exchange. “
”Since the report, the company stock has been on a downward slope after rising to a new record in 2013. On November 8, 2017, Jamaica Stock Exchange Junior Market listed Knutsford Express, after a long period of overvaluation relative to the market, dropped $2.75 as demand for the stock evaporated. Similarly, Cargo Handlers was pushed unrealistically to $30, only for it to currently be trading at $10, which is still above normal valuation. This latter stock came as a big buy recommendation on the way up by a brokerage house at the time.
“Unilever’s profit peaked in the period to September 2014 and started a downhill ride since, but investors kept on pushing the price higher until it peaked at an unrealistically high of TT$68.30 in December 2015.”
The IC Insider.com recommendation at the time was as follows: When stock prices rise much faster than the growth in profits, time out is needed to discover what is happening. That recommendation is as true then as it is now.

Knutsford Express

Notably, after several years, all three of the above stocks are currently trading well below their peak while many other stocks in the markets have gone on to record high prices. At the last trade Unilever is trading at TT$15.20, Cargo Handlers for a long time around $7, but recently hit $12 and Knutsford that traded at a high of $17, with a PE of 31 now trades at $8, with a PE closer to 40.
Investing in undervalued stocks that have products to support growth, as was the case in Lascelles shares, can pay rich dividends over time.
Investors should be mindful of chasing after the popular stocks that are fully valued or overpriced as was the case in the above three stocks that failed to perform in more than four years while others have delivered outstanding gains. That is why ICInsider.com has come up with a list of 10 stocks in both the Main and Junior Markets that, in our estimation, are good candidates for long-term investment for the next ten years. The numbers climbed to 11 each as we could not separate the 11th ones from the lists. The listings are a compilation based on inputs from some knowledgeable investors as well as ICInsider.com’s own assessment. The selections are based on an evaluation of the quality of management, products and services each company offers to their customers, and prospects for growth by these companies and the economies they service.
Most importantly, the analysis considers that management has the quality or will get the talent to steer the companies successfully over a ten year period.
Note is taken of the local economy, the commitment to fiscal surplus or modest deficit financing if at all for a number of years. This will lead to low interest rates and stimulate long term economic growth, subject to world conditions. In such an environment investors can look to invest for the long term rather than a few months or years.
Caribbean Producers almost made the cut with expected strong growth in the tourism sector in which it is a major player, but the historical performance since it was listed on the Junior Market in 2012, leaves doubt if management can in fact deliver predictable good returns for investors over the next ten years.
ICInsider.com was assisted with the selection by Karl Wynter and an individual investor, with years of managerial experience working for some leading groups in the Caribbean. Karl Wright former head of VM Group and individual investor, Ryan Strachan of GK Capital and Nigel Coke former investment advisor and trader at one of the leading Jamaican stockbrokers and an individual investor.

Coming in two separate articles are commentaries on the rationale for each selection. 

More changes to ICTOP10

The only major move in the Junior Market ICTOP10 listing, this week was a fall of 8 percent for Tropical Battery, while in the Main Market, Carreras rose 6 percent followed by Caribbean Producers with 5 percent, both dropped out of the TOP10, while Guardian Holdings and 138 Student Living both lost 5 percent for the week. The week’s movements resulted in no change to the ICTOP10 Junior Market stocks but Transjamaican Highway and Jamaica Broilers return to the list.

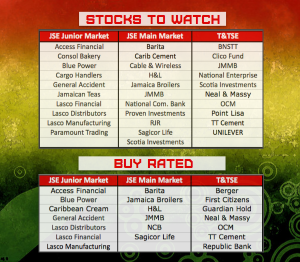
BuyRated stocks from the long-ago past

The Junior Market index closed up to 4,052.19 points, ahead of the 4,031 close of the previous week, helped by the strong gains in the two newly listed companies; JFP limited and EducFocal that jumped sharply during the week, with the former topping out at $2 to close the week up by 36 percent at $1.36, with a PE of 19 times projected 2022 earnings, while the latter jumped to $3.07 for an incredible gain of 207 percent with a PE of 38 based on projected earnings of 8 cents for 2022.  Meanwhile, the Main Market continues to consolidate at a support level of around 440,000 points using the All Jamaica Composite Index, but the market drifted down below that level in the latter part of the week as NCB Financial dropped to a multi-year low of $91.01 on Wednesday, with little demand for the stock currently, but it may find support around the $105 level.
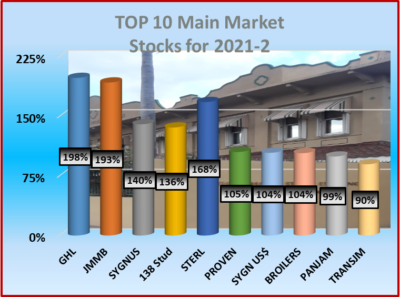
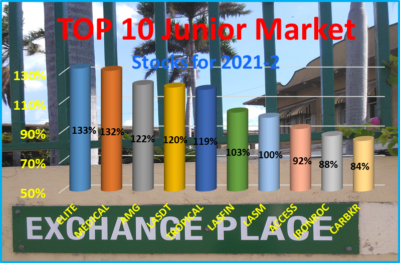
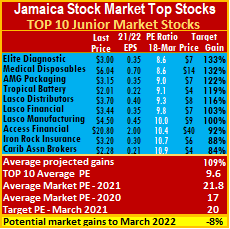
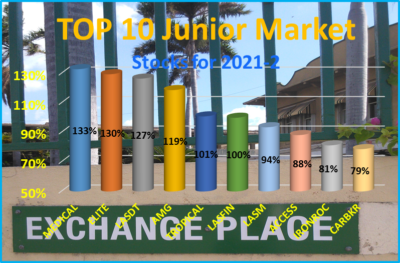
The Junior Market potential gains for the TOP 10 Junior Market stocks stand at 109 percent, much lower than the Main Market at 137 percent, an indication that Main Market is greatly undervalued. The top three stocks in the Junior Market are Elite Diagnostic, Medical Disposables followed by AMG Packaging, to gain between 122 and 133 percent.
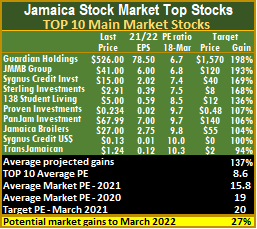
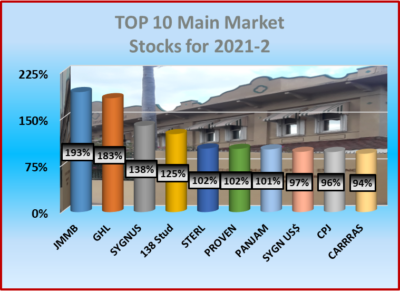
The potential gains for Main Market stocks moved from 127 percent last week to this weeks’ 137 percent, with the top three being Guardian Holdings, JMMB Group followed by Sygnus Credit Investments all projected to gain between 169 and 198 percent versus 168 to 193 percent last week.
The average PE for Junior Market is well ahead of the average of 17 times 2020 earnings achieved at the end of March last year in moving to 21.8 based on ICInsider.com’s 2021-22 earnings, pushed up mainly by five stocks, with EduFocal and Main Event over 100 times 2021 earnings. Excluding the 5 highest PE ratios over 40, the average would be around 18. The JSE Main and USD Markets at 15.8 is well off from 19 in 2021. The TOP 10 stocks trade at a PE of a mere 8.6, with a 45 percent discount to that market’s average.
The average PE for the JSE Main Market is 20 percent less than the PE of 19 at the end of March and 24 percent below the target of 20 to the end of March this year. The Main Market TOP 10 average PE is 8.6 representing a 45 percent discount to the market, well below the potential of 20. The depressed PE of the main market is an indication that bigger investors are reluctant to be aggressive in buying into the market currently, with inflation, rising interest rates and war populating the headlines.
ICTOP10 focuses on likely yearly winners, accordingly, the list may or may not include the best companies in the market. ICInsider.com ranks stocks based on projected earnings to highlight winners from the rest, allowing investors to focus on potential winning stocks and helping to remove emotional attachments to stocks that often result in costly mistakes.
IC TOP10 stocks are likely to deliver the best returns up to March 2022 and ranked in order of potential gains, based on the possible increase for each company, considering the earnings and PE ratios for the current fiscal year. Expected values will change as stock prices fluctuate and result in weekly movements in and out of the lists. Revisions to earnings per share are ongoing, based on receipt of new information.
Persons who compiled this report may have an interest in securities commented on in this report.
Cargo Handlers exits ICTOP10 with 33% gain

Cargo Handlers returned to ICTOP10 listing last week and was another winner with gains of 33 percent, sufficient to move it out of the top flight Junior Market stocks. The stock joins a long list of high performance ICTOP10 stocks, including the 32 percent gain in Tropical Battery stock in the previous week.
Caribbean Assurance Brokers come back in the Junior Market list, while Sterling Investments makes it back to the Main Market listing at the expense of TransJamacian Highway after just one week, but investors should keep an eye for this one.
In a week when the Junior Market dropped 297 points in three days that pushed the index down to 3,871 points, it bounced on the last two days to close over 4,031, still 137 points from the record of 4,168.16, at the end of the previous week. Meanwhile, the Main Market continues to consolidate around support at 440,000 points measured by the All Jamaica Composite Index.
Recent IPOs JFP limited and EducFocal are set to list on Monday and Tuesday coming following the oversubscribed initial public offers.
During the past week, the Junior Market TOP10 listed Access Financial, Lasco Financial and Iron Rock Insurance gained 6 percent each while Medical Disposables fell 9 percent and Tropical Battery slipped 5 percent. In the Main Market, the primary movers are Guardian Holdings with a 4 percent gain, while JMMB Group fell 7 percent and Proven Investments declined by 5 percent.
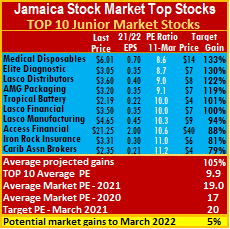
The potential gains for the TOP 10 Junior Market stocks remained for a second week at 105 percent, much lower than the Main Market at 127 percent, an indication that the Main Market is undervalued. The top three stocks in the Junior Market are Medical Disposables followed by Elite Diagnostic and Lasco Distributors to gain between 122 and 133 percent, compared to 121 and 126 percent, previously.
The potential gains for Main Market stocks moved from 124 percent last week to this weeks’ 127 percent, with the top three being JMMB Group followed by Guardian Holdings and Sygnus Credit Investments all projected to gain between 168 and 193 percent versus 161 and 193 percent last week.
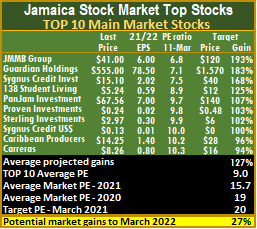
The average PE for Junior Market has surpassed the average of 17 times 2020 earnings achieved at the end of March last year in moving to 19 based on ICInsider.com’s 2021-22 earnings and is ahead of the JSE Main and USD Markets at 15.7 well off from 19 in 2021. The TOP 10 stocks trade at a PE of a mere 9, with a 48 percent discount to that market’s average.
All the stocks in the Junior Market can gain just 5 percent to the end of March this year, based on an average PE of 20. About a third of Junior Market stocks with positive earnings are trading at or above this level, averaging around 23.
The average PE for the JSE Main Market is 21 percent less than the PE of 19 at the end of March and 24 percent below the target of 20 to the end of March this year. The Main Market TOP 10 average PE is 9 representing a 43 percent discount to the market, well below the potential of 20. Around 15 stocks or a thirty percent of the market trade at or above a PE of 19, with most over 20, for an average roundabout 25, suggesting that the accepted multiple is between 20 and 25 times current year’s earnings. The depressed PE of the main market may be indicating that bigger investors are reluctant to be aggressive in buying into the market currently with inflation, rising interest rates and war populating the headlines.
ICTOP10 focuses on likely yearly winners, accordingly, the list may or may not include the best companies in the market. ICInsider.com ranks stocks based on projected earnings to highlight winners from the rest, allowing investors to focus on potential winning stocks and helping to remove emotional attachments to stocks that often result in costly mistakes.
IC TOP10 stocks are likely to deliver the best returns up to March 2022 and ranked in order of potential gains, based on the possible increase for each company, considering the earnings and PE ratios for the current fiscal year. Expected values will change as stock prices fluctuate and result in weekly movements in and out of the lists. Revisions to earnings per share are ongoing, based on receipt of new information.
Persons who compiled this report may have an interest in securities commented on in this report.
SOS driving sales and profit into 2022

“The fourth quarter of 2021 also provided a substantial increase year-over-year as Stationery and Office Supplies was able to post a $13.3 million profit compared to a loss in the previous year 4th Quarter of $8.2 million from sales of $103 million up 45 percent from $71 million in 2020, to record the best December quarter in SOS’ history” the director advised shareholders in their commentary on the full year results.
The company “had a very strong year in 2021 as revenues and gross profit grew by double digits, gross profit percentage increased to 51.2 percentage while expenses were held to a modest 3 percent increase. SOS was, therefore, able to record its second highest pre-tax profit figure in its history of $105M.”
“For the fourth quarter, we put an emphasis on Christmas sales which is normally our slowest time of the year so that greatly helped” Allan McDaniel, the company’s recently appointed CEO, informed ICInsider.com. Revenues for the company’s 2022 first quarter are said to be the company’s best first quarter ever up to early March, with expansion in the BPO sector seeming to be playing a major role.
The company seems set to deliver its best full year results in 2022 barring any major negative developments. If revenues excluding book production grow by 18 percent profit should reach $210 million for EPS of 85 cents versus 43 cents for 2021, but ICInsider.com projects sales revenue growth of 28 percent and profit to reach $275 million and EPS of $1.10.
Segment results from the audited financial statements paint an interesting picture with Furniture revenues dropping 37 percent to $462 million from $734 million in 2020 but Stationery and Others surged 207 percent to $614 million. The small books segment saw revenues climbing 26 percent to $48 million. ICInsider.com consulted with the company about the substantial changes in the revenues for the two large segments and was informed that there are to be adjusted and will likely show that that the Furniture segment remained flat while Office supplies grew by 45 percent over 2020. With the expansion in the BPO industry, there are good prospects that the furniture segment could see a major move in sales in 2022.
Cost of sales climbed 9 percent to $574 million from $527 million in 2020, but gross profit surged 24 percent to $551 million from $445 million in 2020.
Administrative and general expenses rose 9 percent to $320 million from $287 million, while selling and promotional expenses rose 7 percent to $80 million from $75 million in 2020,

Stationery & Office Supplies hit new high after posting good Q2 results.

Depreciation and amortization cost slipped from $28 million to $26 million and Finance expenses fell from $15 million to $11 million.
The performance generated gross cash inflows of $142 million, but increased inventories, and receivables consumed $124 million, with the company ending up with negative funds flow after paying $40 in dividends and loan repayment of $42 million that resulted in cash of $34.5 million down from $97 million at the end of 2020.
Notwithstanding, the dislocations caused by the Coronavirus, the company’s financial position continues to improve, with shareholders’ equity climbing to $677 million from $610 million in 2020, borrowed funds amount to $137 million, down from $172 million at the end of 2020. Current assets rose to $524 million from $460 million with Inventories climbing to $296 million from $233 million and trade and other receivables moving from $99 million to $124 million. Current liabilities fell by $40 million to $105 million.
The company has an excellent management team, with the stock being ICInsider.com BUY RATED, with a price of $7.20 and a PE of 6.6 times 2022 earnings and 16.7 times last year’s earnings.

Tropical drops ICTOP10 with 32% rise

Last week Tropical Battery surged right to the top of the ICTOP10 Junior Market listing with the company seems poised to earn $280 million for the current year, with earnings per share of 22 cents. Investors who pounced on the stock immediately after the release of the first quarter results before the price pulled, drive the price up in the holiday shortened week to close with a 32 percent gain at $2.30.
In a week when the Junior Market came back to life to close at a new record high on Friday, following a new record on Thursday, the market index closed on Friday over the 4,100 mark for the first time and ended at 4,168.16, with a 21.6 percent gain for the year to date. At the same time, the Main Market continues to consolidate around the 440,000 points level, on the All Jamaica Composite Index.
The EduFocal initial public offer to raise $130 million at $1 per share, opened and closed on Thursday morning, ICInsider.com was informed that preliminary data suggests that the offer attracted around twice the amount on offer, resulting in the early closure. Elsewhere, the Jamaica Stock Exchange is enjoying robust business in 2022 over 2021, which should deliver a big bump in revenues and profit for 2022 should the trend holds, accordingly, ICInsider.com now puts 2022 earnings for the first quarter above the 2021 full year’s earnings of 71 cents, with a possible $3 per share for the full year. Watch this one.
In TOP10 developments this week, returning to the Junior Market are Cargo Handlers with the price holding at $8.99 and Medical Disposables after the price slipped from $7.27 to $6.60 this week. Dropping out of the TOP10 this week are Caribbean Assurance Brokers with the price falling 23 percent to $2.50 as investors dumped the shares after the company reported a 47 percent increase in profit to 21 cents per share, but vastly down on the 33 cents per share reported in the nine months to September. The Main Market had three changes, with Caribbean Producers and Carreras returning to the Top10 to be joined for the first time by Transjamaican Highway and out goes Berger Paints, Jamaica Broilers and Sagicor Group.
During the week, the Junior Market TOP10 listed AMG Packaging fell 8 percent to $3.14 and in the Main Market, Proven Investments rose 9 percent followed by Berger Paints 6 percent and a 4 percent fall for Jamaica Broilers, but Guardian Holdings and Sagicor Group fell 5 percent
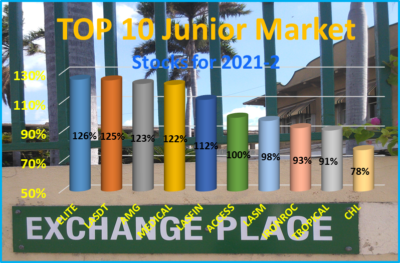
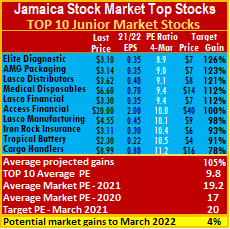
The Junior Market potential gains for the TOP 10 Junior Market stocks moved from 113 percent to 105 percent much lower than the Main Market at 124 percent. The top three stocks in the Junior Market are Elite Diagnostic followed by AMG Packaging and Lasco Distributors to gain between 121 and 126 percent, compared to 120 and 153 percent, previously.
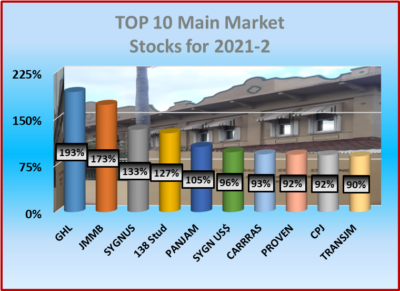
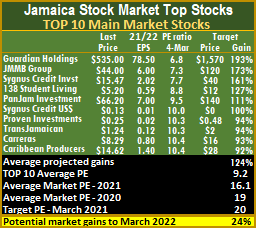
The potential gains for Main Market stocks moved from 125 percent last week to this weeks’ 124 percent, with the top three being Guardian Holdings followed by JMMB Group and Sygnus Credit Investments all projected to gain between 161 and 193 percent versus 161 and 180 percent last week.
The average PE for Junior Market has surpassed the average of 17 times 2020 earnings achieved at the end of March last year in moving to 19.2 based on ICInsider.com’s 2021-22 earnings and is ahead of the JSE Main Market at 16.1. The TOP 10 stocks trade at a PE of a mere 9.8, with a 49 percent discount to that market’s average.
All the stocks in the Junior Market can gain just 4 percent to the end of March this year, based on an average PE of 20. About a third of Junior Market stocks with positive earnings are trading at or above this level, averaging around 23.
The average PE for the JSE Main Market is 16.1 just 18 percent less than the PE of 19 at the end of March and 24 percent below the target of 20 to the end of March this year. The Main Market TOP 10 average PE is 9.2 representing a 43 percent discount to the market, well below the potential of 20. Around 15 stocks or a thirty percent of the market trade at or above a PE of 19, with most over 20, for an average roundabout 25, suggesting that the accepted multiple is between 20 and 25 times the current year’s earnings. The depressed PE of the main market may be indicating that bigger investors are reluctant to be aggressive in buying into the market currently with inflation, rising interest rates and war populating the headlines.
ICTOP10 focuses on likely yearly winners, accordingly, the list may or may not include the best companies in the market. ICInsider.com ranks stocks based on projected earnings to highlight winners from the rest, allowing investors to focus on potential winning stocks and helping to remove emotional attachments to stocks that often result in costly mistakes.
IC TOP10 stocks are likely to deliver the best returns up to March 2022 and ranked in order of potential gains, based on the possible increase for each company, considering the earnings and PE ratios for the current fiscal year. Expected values will change as stock prices fluctuate and result in weekly movements in and out of the lists. Revisions to earnings per share are ongoing, based on receipt of new information.
Persons who compiled this report may have an interest in securities commented on in this report.
Huge jump in trading at Jamaica Stock Exchange

Trading on the Jamaica Stock Exchange climbed sharply for the first two months and three days of 2022, well above the similar period last year with both the Main and Junior markets showing strong increases in volumes and value of trading.
In 2021, the Junior Market traded 422 million shares in the first two months valued at just over $1 billion that climbed to 137 percent to 577 million shares valued 212 percent higher at $2.17 billion but trading for the first three days of March is up a strong 543 percent over the similar period in 2021.
Main Market trading climbed 111 percent in volume and 184 percent in value to 712.7 million units at $6.35 billion up from 641.8 million units valued at $3.46 billion.  For the first three days of March, the value of stocks traded on the Main Market is $1.765 billion and is up a stunning 674 percent for the same period in 2021. March dollar value trading is 48 percent of this year’s February and the value of Junior Market trading for the first three days of March amounts to $426 million or 36 percent of the value of stocks traded for February this year.
Not only are the numbers for March so far are now at 65 percent of the entire value traded in March 2021 in the Main Market, with the Junior Market at 36 percent of the $1 billion traded for March 2021.
The trend if continued is positive for the two main stock exchange markets and suggest a big rise in stock price and a big jump in revenues and profits at Jamaica Stock Exchange that generated income of 1.93 billion last year up just 12.6 percent from $1.71 earned in 2020 and profit of $497 million up 22 percent over the $407 million earned in 2020 after tax as the company held cost to $1.24 billion up 8.7 percent above $1.14 billion in 2020. Taxation ate into the profits, taking $244 million compared to $212 million in 2020. The company reported 71 cents per share for 2021 but this seems set to explode sharply higher in 2022 if the above trading trends continue.
The company remains in a very healthy financial position with current assets ending the year at $881 million and current liabilities of $235 million and generating cash inflows of $777 million for the year. The JSE ended with shareholders’ equity of $1.9 billion in 2021 up from $1.5 billion in 2020.
The JSE is not only benefitting from increased trading for 2022 but will be seeing new listings during the year that will provide added income and profits for them.
The stock traded at $16.95 on Friday at a PE ratio of 24 but the PE seems poised to fall sharply for 2022 with the strong growth in revenues from existing business as well as a result of new listings, accordingly, ICInsider.com places an ICBUY RATED approval on the stock.

Tropical Battery profit explodes in Q1

Tropical Battery reported stunning first quarter results to December, with profits surging 198 percent from just $19 million in 2020 to $56.7 million as revenues jumped 46.8 percent to $662 million and encouraging investors to react positively to the surprising numbers right out of the block by driving the price up 18 percent for the day of the release and 37 percent for the year to date.
Earnings per share climbed from 1.5 cents to 4.4 cents for the quarter.ICInsider.com forecast is for profit of $280 million, with earnings per share of 22 cents, for the year to September, more than five times 2021 full year earnings, with potential for the price to deliver gains of 153 percent.
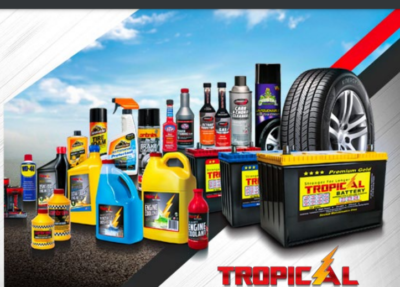
Battery Sales jumped 52 percent from $389 million in the 2020 December quarter to $591 million while Tyre Sales rose from $6.5 million to $8 million and Accessories contributed $67 million compared to $60 million in 2020, just 11 percent more.
The big push in sales was facilitated by a recovery in the local economy but importantly, increased inventory levels that doubled from $434 million at the end of December 2021 to $873 million which is up from $609 million at the end of September last year, would have played a big role in increasing revenues. The increase in sales “was achieved through an increase in balanced inventory arrivals and a tremendous effort on the part of our sales team to surpass targets by bringing in new customers,” the company managing director and deputy managing director advised in their interim report to shareholders.
Other Income slipped 14 percent to $2.6 million and interest Income dropped 39 percent to $3.6 million.
Improvement in profit margin remained at 30 percent for both quarters and resulted in gross profit rising 44 percent to $196 million from $136 million in 2020 as cost of sales rose just ahead of the increase in revenues.
Administrative expenses rose 10 percent to $114 million in the quarter from $104 million in 2020. Depreciation charges jumped 79 percent to $16 million. Finance costs rose 13 percent, to $15 million from $13.5 million in 2020.

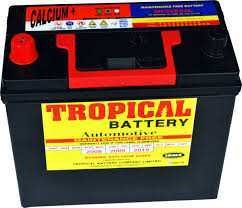
Tropical Battery line of products

The operation generated gross cash flow of $73 million but ended up with negative inflows of $30 million after increase in working capital and addition to fixed assets and ended with cash funds of $144 million. At the end of the quarter, current assets rose to $1.6 billion from $1.09 billion in 2020 while current liabilities moved from $343 million at the end of December 2020 to $679 million, leaving net current assets at $933 million. Payables rose to $564 million from $223 million at the end of 2020, at the same time shareholders’ equity stands at $883 billion with borrowings at $568 million.
“With our more-than-adequate levels of inventory, we see a bright year ahead. We are also currently expanding our top-selling retail store, located on Grove Road, just off Half Way Tree Road in Kingston, which will allow us to increase sales at this location even further, and achieve higher profitability, given that retail margins are better than our wholesale margins while offering greater comfort and convenience for our team members and customers with a substantial increase in square footage. We plan to increase our retail presence island-wide in the coming quarters. The company rolled out new products in the quarter and plan to launch more in the March quarter”, the company stated in a report to shareholders, jointly signed by Alexander Melville, Managing Director and Daniel Melville Deputy Managing Director.
The stock traded at $1.74 on the Junior Market of the Jamaica Stock Exchange with a PE ratio of just 8 times 2022 earnings compared to an average of over 19 for the market and sits at the top of ICTOP10 Junior Market listing.