Profit at the Jamaica Stock Exchange jumped a sharp 155.5 percent in the March 2025 first quarter, to $236 million after corporate Tax, up from just $93 million in 2024.
 Expenses increased 12.4 percent over 2024, to $554 from $493 million in 2024, the increase was much less than the 36 percent growth in revenues of $861 million, up from $634 million in 2024, growth was driven by improved market conditions and heightened market activity, leading to a substantial 245.7 percent rise in income form Cess of $256 million over, just $74 million in 2024.
Earnings per share amount to 34 cents, up from 13 cents last year and compare well with full year earnings last year of 71 cents. Based on these results, the company is on target for earnings in the $1.60 region, with a PE of 8 based on the last traded price of $12.75 and placing it on the ICInsider.com coveted Buy Rated accolade.
Equity capital stands at $3 billion and cash and investments amount to more than $1 billion.
With interest rates much lower this year than last year, more funds should flow into stocks and boost the existing income levels of the exchange. In addition, more companies are expected to be listed in 2025 and future years and existing companies are raising more equity capital, all of which should boost revenues for the exchange in the years ahead. The future looks very promising for investors in this stock in the years ahead.
 The group declared a dividend payable in January of 40 cents for a second consecutive quarter putting it at $1.60 annualised, for a 4.6 percent yield based on the current price. Traditionally the group was committed to paying 40 to 50 percent of profits, this seems to have temporarily changed with the fallout from the Covid-19 pandemic but could return in the near future.
 Highlights of the good performance came from interest income, with the quarter jumping 22 percent to $11.6 billion from $9.5 billion in 2022 and by 31 percent for the full year to $40.8 billion with loans disbursed growing a robust 15 percent to $269 billion from $234.7 billion in 2022, after loan loss provisions. Non-accrual loans stood at $4.5 billion compared to $4 billion at the end of October 2022 and represent 1.6 percent of gross loans compared to October 2022 at 1.7 percent.
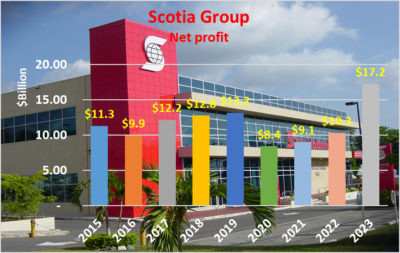 lower fair value losses on the investment portfolio, recognition of the insurance finance reserve on the adoption of IFRS 17 and profit generated for the year, partially offset by dividends paid. Total assets grew by $70 billion to $665 billion at October 2023.
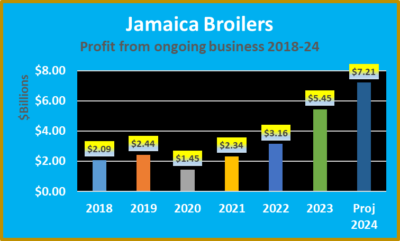 Administrative costs declined marginally from $2.98 billion to $2.92 billion in the current period, distribution costs rose four percent from $690 million to $720 million, finance costs almost doubled, moving from $320 million to $633 million, taxation moved up from $332 million to $393 million during the 2023 quarter.
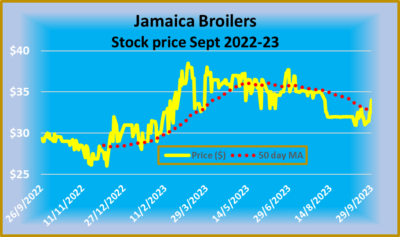 Cash inflows before working capital requirements for $3.4 billion and is up from $2.6 billion in the previous year after working capital funding rose, the group ended up with a negative cash flow of $2 billion that is up from $1 billion in the previous year.
 Trades by directors and connected parties in listed companies may speak volumes about what is currently occurring in their operations and can be a short term signal to follow. Not all trades have immediate significance, as they may be for reasons unrelated to the company’s performance, like the need for cash or reallocation of investments; regardless, investors would be well advised to take a keen interest in such actions.
 Earnings per share amounted to $2.67 for the September quarter and $4.55 for the nine months to September, that should end the year around $7 per share, with a PE of 3.5 times current year’s earnings and a stock price at J$530.
 We projected revenues of $1.465 billion and they delivered $1.449 billion in the quarter. Our forecast for TV revenues was $626.344 million, they reported $639.377. Radio revenues came in at $199.605, somewhat higher than ICInsider.com’s projection of $184.05 and the print division delivered $610,217 million versus ICI’s forecast of $635,697. Other income amounts to $29 million versus IC forecast of $19 million.
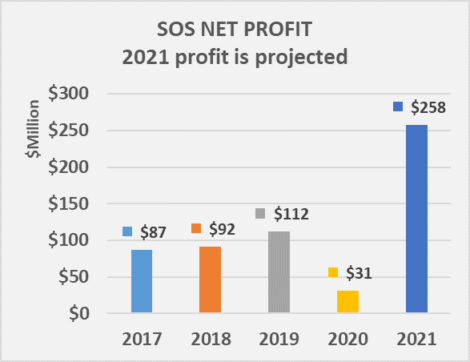 The company enjoys a ten-year tax profit break and will be subject to zero taxation until mid-2022 and 50 percent thereafter for five years.
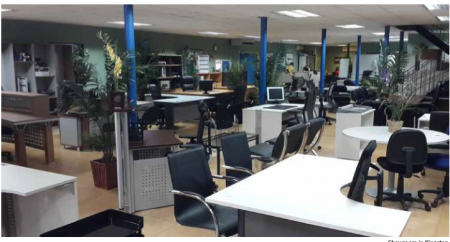 Cash funds and investments amount to $121 million after the company generated cash funds of $69 million before working capital and capital financing needs. ICInsider.com projects earnings of $1 for the financial year to December 2021 and $1.60 for 2022.
 For the year, profit after tax surged 70 percent to $3.2 billion after tax provision of $1.2 billion. The tax charge includes deferred tax amounting to $414 million, down from $664 million in 2019. The results would have been far better but for a billion loss in foreign exchange movement, but interest cost fell from $939 million to $812 million, partially cushioning some exchange losses. Interest cost will fall further in 2021 as the debt load recedes with the strong cash flows allowing for the rapid repayment of the $4.4 billion of long term loans.
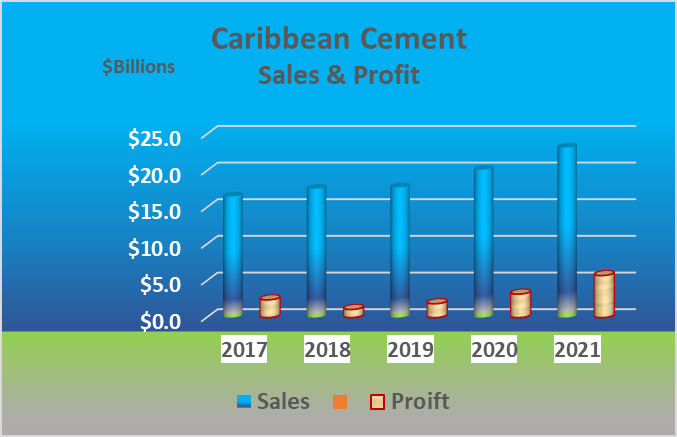 At the end of the year, shareholders’ equity moved to $11.5 billion from $8.3 billion at the end of 2019. The stock is one of the original