Rate hike pushes earnings higher at Scotia

If there was much competition in the banking sector in Jamaica, Scotia Group would be on its way out of business, unless they mended the poor service there are currently dishing out to customers.
Scotia Group stock could deliver handsomely in 2022.

The banking arm is delivering some atrocious customer service of late such as bouncing cheques for no funds when such accounts were adequately funded. Customers can’t get the use of the transfer of funds feature, for the credit cards are expired but no one within the bank advises of the expiration and the availability of the new card. Even when communication is made, with the bank, months pass without action. What about tokens that don’t work, leading to a nightmare trying to get the problem resolved. The service has rotted recently and they need to do something about it fast.
Though the service has gotten lousy of late and some may say it never was good, investors may find positives that they can profit from, at least that is what the group’s first quarter results to January this year show, thanks partly to the action by the country’s central bank. Most investors would not come to that conclusion from the net profit for the quarter compared to that in 2021, for while the 2021 quarterly profit came in at $1.75 billion, the latest results were only up marginally by $34 million to $1.784 billion. On the surface, there is nothing to get excited about, but closer examination tells a different story.
The results were vastly better than the $1.12 billion reported for the October quarter which suffered from a big drop in revenues. Loans fell in the quarter from $208 billion at the end of October to $201 billion at the end of January while investable funds grew to $339 billion from $321 billion at the end of October but net interest income climbed to $6.16 billion from $5.7 billion in the October quarter coming from a rise in gross interest income of $454 million quarter over quarter. Interest cost was static at $452 million. There was a strong improvement in net fee and commission income that rose from $1.1 billion in the October quarter to $1.5 billion but was a bit lower than the $1.67 billion in the January 2021 period, other revenues dropped from $973 million to $295 million in the latest quarter compared to January 2021.
Net interest income increase “was primarily attributable to an increase in interest earned on the investment portfolio and improved retail loan performance,” Scotia Group reported in their release of the quarterly results.
Audrey Tugwell Henry Scotia group’s CEO

Since the end of January, the Bank of Jamaica hiked the overnight rate to 4.50 percent from 2.5 percent, this move will drive an increase in net interest income for the group as the cost of funds will remain fairly flat while investments income balloons.
Expected credit losses on loans rose from $430 million in 2021 to $569 million in the January quarter this year but show an improvement over the $819 million in the October quarter. Net interest income after credit losses rose to $5.6 billion from $5.4 billion in 2021. Net fees and other income fell from $5.44 billion in the January 2021 quarter to $4.78 billion in 2022, resulting in a total net income of $10.37 billion, down from $10.8 billion in 2021.
Lower costs helped with the 2022 results, with expenses falling to $6 billion from $6.5 billion, net of asset tax of $1.36 billion in 2022 versus $1.26 billion in 2021, Other operating costs fell by $500 million from January 2021 to $2.8 billion in 2022.
Other comprehensive income shows an unrealized loss of $1 billion on investments compared to just $123 million in the 2021 first quarter.
Segment results provide another view of developments within the group that could point to the way forward. The Treasury segment delivered 22.4 percent more revenues from third parties to hit $763 million with a profit before tax of $138 million up from $120 in 2021. The retail division suffered a decline of 15 percent, with revenues from third parties hitting $4.57 billion from $5.38 billion in 2021 resulting in profit before tax of $103 million, down sharply from $492 million in 2021. Corporate and Commercial Banking pulled in net income of $2.7 billion, down from $2.8 billion, with profit surging to $1.44 billion versus $967 million in 2021. Investment Management pulled in $822 million in revenues with a profit of $404 million, from revenues of $878 million in 2021 with a profit of $718 million.  The insurance division raked in $1.33 billion in revenues up from $984 million, with profit jumping to $857 million from $567 million. The segment classified as Other, generated revenues of $217 million and a profit of $175 million and delivered revenues of just $83 million and a profit of $30 million in 2022.
The Group’s assets grew by $38 billion or 6.9 percent to $591 billion at January 2022. This was predominantly, a result of the growth in cash resources of $42 billion or 32.4 percent due to increased deposits and places the group in a good position to expand the loan portfolio when demands pick up, with the resurgence now taking place in the wider economy.
A dividend of 35 cents per stock unit in respect of the first quarter, was approved for payment on April 20 to stockholders on record as of March 29.
Gooden buys 10% of Elite Diagnostic

Reports reaching ICInsider.com is the chairman of Elite Diagnostic acquired more than 35 million shares on Friday, with the majority coming from Excel Investments, that owned the largest block of 130 million or 36.9 percent of issued shares.
The trade means that Gooden, who previously owned a mere 242,230 or a fraction of one percent, will now own around 10 percent of the company, the third largest shareholder behind Excel with 85,231,108 units and NCB Capital Market with 66 million shares or 18 percent.
Gooden, a very knowledgeable person in the investment field, also heads NCB Capital Market and controls the largest block of shares in the company of 28 percent, compared to Excel with 27 percent.
The Elite Diagnostic trade was the largest block of shares trading on Friday, accounting for 76.5 percent of all Junior Market trades on that day, but trading ended with 85.2 million units on the offer to sell at $2.57 and 30 million on the bid to buy at $2.50. ICInsider.com gathers that the amount on offer is not up for sale and should have been cancelled before the market closed.
The purchase is a strong endorsement for the stock and the company’s future that ended as the number one choice in this weeks’ ICTOP10 Junior Market listing.
The results for the second quarter to December stated, “continued spread of the Coronavirus disease (COVID-19) continued to negatively impact the operations of the company. Revenue continues to be impacted as social distancing protocols reduce the number of patients booked per day.”

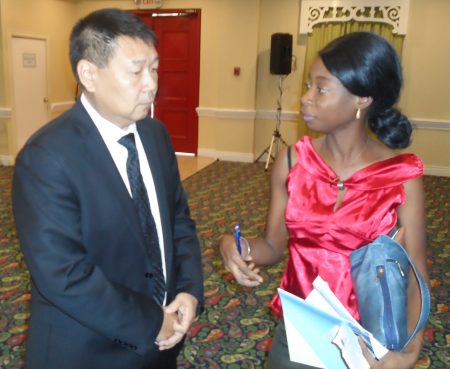
Elite CEO Warren Chung & shareholder in Excel Investments chatting with a shareholder at Elite’s 2018 AGM.

ICInsider.com understands that the restriction placed for curfews restricted business as the offices could not be opened late, thus affecting business.
Gooden most likely would have seen the prolonged trend of year over year and quarter over quarter growth in revenues and the strong positive cash flow the company continues to generate and prospects for more expansion of the business as solid credentials for future earnings and profit.
For the six months to December last year, the company generated a profit of $7 million but had positive cash inflows of $83 million, with revenues rising 22 percent from $236 million to $288 million with eth December quarter rising 16.6 percent from $128 million to $148 million. Profit in the second quarter increased from $3 million in 2020 to $7.3 million. Importantly gross profit margin is an astounding and attractive 66 percent.


JFP lists on Monday

Trading of shares that were recently offered to the public in JFP Limited, will commence on Monday on the Junior Market of the Jamaica Stock Exchange and bring the total listings on the market to 44 and will move to 45 on Tuesday after the listing of Edufocal.
A total of 280 million ordinary shares were offered to the public with the issuing opening on February 21 and closed the offer being oversubscribed.

JFP production

Employee Reserve Pool applicants received 100 percent of their application with the balance not applied for was made available for Key Partner Reserve Pool who received all they applied for. GK Investments Reserve Pool applicants got all shares applied for, applicants from the General Public got 12,500 shares plus approximately 22.8 percent of the excess shares applied for above the Base Allotment. The oversubscription should provide a bounce for the stock when it opens.

Edufocal lists on Tuesday

Trading of shares in EduFocal that offered 129,689,219 ordinary shares to the public on March 3, will commence on Tuesday as the company shares will be listed on the Jamaica Stock Exchange Junior Market on that day and will bring the total listings on the market to 45.
The offer was oversubscribed, with Key Strategic Partners in this reserved pool will receive all their predetermined amount.
Applicants who applied for more than their predetermined amount will receive a pro-rata allocation of approximately 59.67 percent of the excess shares for which they applied, with any excess transferred to the General Public Pool.
All applicants from the General Public received 10,000 shares and approximately 16.57 percent of the excess shares.
Although the offer was handily oversubscribed, ICInsider.com gathers there were applications that came in after the close just after the issue opened and closed minutes after opening so there is added demand that should provide a bounce for the stock.

Fesco raised $1 billion for expansion

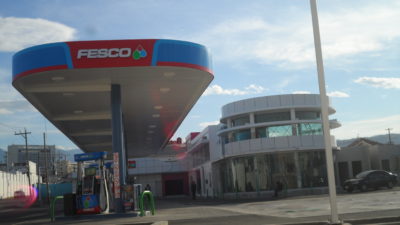
Future Energy Source Company (FESCO), secured debt financing for One Billion Dollars, the company informed the Jamaica Stock Exchange to be used for general corporate purposes that support FESCO’s growth objectives.
The facility is a five years corporate bond to be listed on the Private Market of the Jamaica Stock Exchange, with NCB Capital Markets acting as Arranger. The proceeds will be utilized including working capital, operating expenses and capital expenditure related to the expansion of its dealership network and service station footprint and funding the entry into the consumer cooking gas and LPG market.
Fesco recently traded at an all-time high of $8.49 but closed on Wednesday at $5.28 after listing in April 2021 at just 80 cents per share. The company reported revenues of $8 billion for the nine months to December last year, almost doubling the $4.45 billion in the corresponding 2020 period and generating a profit of $171 million versus $92 million before tax.
Included in the expansion plans is the equipping large industrial corporate customers with digitally equipped tanks that will dispense fuel based on individual cards for each driver that will easily track usage for each vehicle as well as the acquisition of cooking gas cylinders in preparation for starting delivery of that service. According to CEO Jeremy Barnes, the plan is to have 22 branded stations within three years.
The company currently has 16 Fesco branded service stations in operation, with the newest one on Beechwood Avenue in Kingston the only one owned and operated by them.

SOS driving sales and profit into 2022

“The fourth quarter of 2021 also provided a substantial increase year-over-year as Stationery and Office Supplies was able to post a $13.3 million profit compared to a loss in the previous year 4th Quarter of $8.2 million from sales of $103 million up 45 percent from $71 million in 2020, to record the best December quarter in SOS’ history” the director advised shareholders in their commentary on the full year results.
The company “had a very strong year in 2021 as revenues and gross profit grew by double digits, gross profit percentage increased to 51.2 percentage while expenses were held to a modest 3 percent increase. SOS was, therefore, able to record its second highest pre-tax profit figure in its history of $105M.”
“For the fourth quarter, we put an emphasis on Christmas sales which is normally our slowest time of the year so that greatly helped” Allan McDaniel, the company’s recently appointed CEO, informed ICInsider.com. Revenues for the company’s 2022 first quarter are said to be the company’s best first quarter ever up to early March, with expansion in the BPO sector seeming to be playing a major role.
The company seems set to deliver its best full year results in 2022 barring any major negative developments. If revenues excluding book production grow by 18 percent profit should reach $210 million for EPS of 85 cents versus 43 cents for 2021, but ICInsider.com projects sales revenue growth of 28 percent and profit to reach $275 million and EPS of $1.10.
Segment results from the audited financial statements paint an interesting picture with Furniture revenues dropping 37 percent to $462 million from $734 million in 2020 but Stationery and Others surged 207 percent to $614 million. The small books segment saw revenues climbing 26 percent to $48 million. ICInsider.com consulted with the company about the substantial changes in the revenues for the two large segments and was informed that there are to be adjusted and will likely show that that the Furniture segment remained flat while Office supplies grew by 45 percent over 2020. With the expansion in the BPO industry, there are good prospects that the furniture segment could see a major move in sales in 2022.
Cost of sales climbed 9 percent to $574 million from $527 million in 2020, but gross profit surged 24 percent to $551 million from $445 million in 2020.
Administrative and general expenses rose 9 percent to $320 million from $287 million, while selling and promotional expenses rose 7 percent to $80 million from $75 million in 2020,

Stationery & Office Supplies hit new high after posting good Q2 results.

Depreciation and amortization cost slipped from $28 million to $26 million and Finance expenses fell from $15 million to $11 million.
The performance generated gross cash inflows of $142 million, but increased inventories, and receivables consumed $124 million, with the company ending up with negative funds flow after paying $40 in dividends and loan repayment of $42 million that resulted in cash of $34.5 million down from $97 million at the end of 2020.
Notwithstanding, the dislocations caused by the Coronavirus, the company’s financial position continues to improve, with shareholders’ equity climbing to $677 million from $610 million in 2020, borrowed funds amount to $137 million, down from $172 million at the end of 2020. Current assets rose to $524 million from $460 million with Inventories climbing to $296 million from $233 million and trade and other receivables moving from $99 million to $124 million. Current liabilities fell by $40 million to $105 million.
The company has an excellent management team, with the stock being ICInsider.com BUY RATED, with a price of $7.20 and a PE of 6.6 times 2022 earnings and 16.7 times last year’s earnings.

Huge jump in trading at Jamaica Stock Exchange

Trading on the Jamaica Stock Exchange climbed sharply for the first two months and three days of 2022, well above the similar period last year with both the Main and Junior markets showing strong increases in volumes and value of trading.
In 2021, the Junior Market traded 422 million shares in the first two months valued at just over $1 billion that climbed to 137 percent to 577 million shares valued 212 percent higher at $2.17 billion but trading for the first three days of March is up a strong 543 percent over the similar period in 2021.
Main Market trading climbed 111 percent in volume and 184 percent in value to 712.7 million units at $6.35 billion up from 641.8 million units valued at $3.46 billion.  For the first three days of March, the value of stocks traded on the Main Market is $1.765 billion and is up a stunning 674 percent for the same period in 2021. March dollar value trading is 48 percent of this year’s February and the value of Junior Market trading for the first three days of March amounts to $426 million or 36 percent of the value of stocks traded for February this year.
Not only are the numbers for March so far are now at 65 percent of the entire value traded in March 2021 in the Main Market, with the Junior Market at 36 percent of the $1 billion traded for March 2021.
The trend if continued is positive for the two main stock exchange markets and suggest a big rise in stock price and a big jump in revenues and profits at Jamaica Stock Exchange that generated income of 1.93 billion last year up just 12.6 percent from $1.71 earned in 2020 and profit of $497 million up 22 percent over the $407 million earned in 2020 after tax as the company held cost to $1.24 billion up 8.7 percent above $1.14 billion in 2020. Taxation ate into the profits, taking $244 million compared to $212 million in 2020. The company reported 71 cents per share for 2021 but this seems set to explode sharply higher in 2022 if the above trading trends continue.
The company remains in a very healthy financial position with current assets ending the year at $881 million and current liabilities of $235 million and generating cash inflows of $777 million for the year. The JSE ended with shareholders’ equity of $1.9 billion in 2021 up from $1.5 billion in 2020.
The JSE is not only benefitting from increased trading for 2022 but will be seeing new listings during the year that will provide added income and profits for them.
The stock traded at $16.95 on Friday at a PE ratio of 24 but the PE seems poised to fall sharply for 2022 with the strong growth in revenues from existing business as well as a result of new listings, accordingly, ICInsider.com places an ICBUY RATED approval on the stock.

Tropical Battery profit explodes in Q1

Tropical Battery reported stunning first quarter results to December, with profits surging 198 percent from just $19 million in 2020 to $56.7 million as revenues jumped 46.8 percent to $662 million and encouraging investors to react positively to the surprising numbers right out of the block by driving the price up 18 percent for the day of the release and 37 percent for the year to date.
Earnings per share climbed from 1.5 cents to 4.4 cents for the quarter.ICInsider.com forecast is for profit of $280 million, with earnings per share of 22 cents, for the year to September, more than five times 2021 full year earnings, with potential for the price to deliver gains of 153 percent.
Battery Sales jumped 52 percent from $389 million in the 2020 December quarter to $591 million while Tyre Sales rose from $6.5 million to $8 million and Accessories contributed $67 million compared to $60 million in 2020, just 11 percent more.
The big push in sales was facilitated by a recovery in the local economy but importantly, increased inventory levels that doubled from $434 million at the end of December 2021 to $873 million which is up from $609 million at the end of September last year, would have played a big role in increasing revenues. The increase in sales “was achieved through an increase in balanced inventory arrivals and a tremendous effort on the part of our sales team to surpass targets by bringing in new customers,” the company managing director and deputy managing director advised in their interim report to shareholders.
Other Income slipped 14 percent to $2.6 million and interest Income dropped 39 percent to $3.6 million.
Improvement in profit margin remained at 30 percent for both quarters and resulted in gross profit rising 44 percent to $196 million from $136 million in 2020 as cost of sales rose just ahead of the increase in revenues.
Administrative expenses rose 10 percent to $114 million in the quarter from $104 million in 2020. Depreciation charges jumped 79 percent to $16 million. Finance costs rose 13 percent, to $15 million from $13.5 million in 2020.

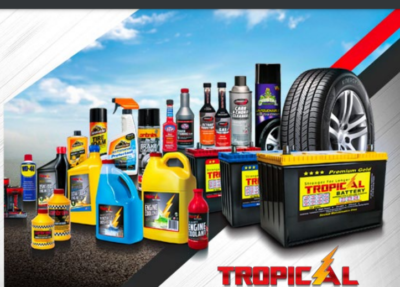
Tropical Battery line of products

The operation generated gross cash flow of $73 million but ended up with negative inflows of $30 million after increase in working capital and addition to fixed assets and ended with cash funds of $144 million. At the end of the quarter, current assets rose to $1.6 billion from $1.09 billion in 2020 while current liabilities moved from $343 million at the end of December 2020 to $679 million, leaving net current assets at $933 million. Payables rose to $564 million from $223 million at the end of 2020, at the same time shareholders’ equity stands at $883 billion with borrowings at $568 million.
“With our more-than-adequate levels of inventory, we see a bright year ahead. We are also currently expanding our top-selling retail store, located on Grove Road, just off Half Way Tree Road in Kingston, which will allow us to increase sales at this location even further, and achieve higher profitability, given that retail margins are better than our wholesale margins while offering greater comfort and convenience for our team members and customers with a substantial increase in square footage. We plan to increase our retail presence island-wide in the coming quarters. The company rolled out new products in the quarter and plan to launch more in the March quarter”, the company stated in a report to shareholders, jointly signed by Alexander Melville, Managing Director and Daniel Melville Deputy Managing Director.
The stock traded at $1.74 on the Junior Market of the Jamaica Stock Exchange with a PE ratio of just 8 times 2022 earnings compared to an average of over 19 for the market and sits at the top of ICTOP10 Junior Market listing.

Dividend payment lifts QWI stock 25% in days

QWI Investments‘ shares gained 14 percent in 2021, with the price closing at 88 cents, a level it remained at until the company announced on February 8, the holding of a board meeting to consider a dividend on Valentine day, February 14, investors have since pushed the price over $1 for a rise of 25 percent at the high of $1.06 it traded at on Wednesday.
At the close of trading on February 7 the price close at 85 cents and ended at 90 cents the next day and closed at $1.01 on the 9th.
At the board meeting, the company approved a dividend of 3.5 cents per share amounting to $47.78 million that will not be subject to taxation, payable on April 7. The board also approved and announced a dividend policy of paying out 20-25 percent of profits annually as dividends in two separate payments. The dividend to be paid is equivalent to just over 4 percent on the pre-announcement stock price and translates to an annual return of nearly 25 percent.
The stock has since climbed to $1.06 in trading on Wednesday morning the first day of trading after the information was disclosed to the Jamaica Stock Exchange, but closed at $1.04 after trading 3.26 million shares.
The gains in the stock since the initial announcement is 24.7 percent as a result investors in the stock before February 8, will enjoy a near 50 percent return if the price remains at these levels after the stock goes ex-dividend in mid-March.
The company continues to record gains in net asset value, with a record $1.56 on February 11, up 11.4 from $1.40 at the end of December and 16.4 from $1.34 at the end of September last year. That translates to a profit of $300 million after provision for taxation from September up to the end of last week and if is sustained would result in an additional payout. The announced dividend policy could be a major game-changer for the stock that has languished below $1 since eh decline in the market in 2020 as the dividend yield could make it an attractive income producer for investors.
The Chairman of QWI Investments is the principal of ICInsider.com.

Impressive profits for listed companies

Freshly released quarterly results reveal positive gains for companies reporting 2021 final quarter numbers recently with most showing improvement over 2020 results, with some being impressive.

Caribbean Producers traded 52 weeks’ high during the week following a near US$2 quarterly profit.

Leading the group was Caribbean Producers with revenues more than doubling to US$33 million up from US$15 in the December 2020 quarter and revenues moving from US$24.4 million to $58 million. Profit jumped to $3.6 million from a loss of $837,492 million in 2020 and rose to $5.2 million for the six months from a loss of $2.7 million in 2020. Earnings per share ended for the quarter at 0.33 US cents and 0.48 US cents for the six months.
Future Energy Source delivered a 250.9 percent surge in profit to $73.6 million from $21 million with the nine delivering an increase of 140.8 percent to $171 million from $71 million in 2020 as revenues rose 139 percent in the December quart to $3.675 billion from $1.535 billion and 84 percent to $8 billion from $4.347 billion in 2020. Revenues were fueled by an increase in the number of service stations from 14 to 16 and a sharp increase in the price of petroleum.
Lasco Distributors revenues grew 12 percent from $5.17 billion to $5.79 billion in the December quarter and 14 percent from $15 billion to $17.4 billion for the nine months percent in 2020.
Profit after tax rose 6 percent, to $775 million from $731 million for the nine months to December, for the quarter to December profit after tax rose 18 percent in the quarter to $286 million from $243 million in 2020.
Earnings per share ended for the quarter at 8 cents and 22 cents for the nine months.

Lasco Financial profit dropped 39% in 2018 Q2.

Revenues at Lasco Financial got a big 30 percent bounce from $532 million to $693 million in the December quarter and 9 percent from $1.69 billion in 2020 to $1.84 billion for the nine months to December 2021.
Profit after tax rose just 6 percent to $130 million from $124 million for the December quarter, but pretax profit rose a strong 35 percent in the quarter to $203 million from $150 million in 2020 and jumped a sharp 60 percent for the nine months to December, to $398 million from $249 million, while profit after tax surged 71 percent to $264 million for the nine months from $154 million in 2020.
Earnings per share ended for the quarter at 10 cents and 21 cents for the nine months.
Revenue for the year ending October 2021 jumped 34.7 percent at Limners and Bards to $1.2 billion, up from $912 million for the prior year. The increase was mainly in media placement up 35 percent to $173 million, production up 63 percent to $148 million.
Profit after rose 22 percent, to $156 million from $127 in 2020 but fell from $19 million in the 2020 final quarter to $13 million in 2021. Earnings per share climbed to 16 cents from 13 cents in 2020.
For MailPac revenues for the quarter were just 2 percent lower than in 2020 as the company generated $502 million, in 2021 from $512 million the same quarter in 2020. Gross profit for the quarter was $255 million, a 9.8 percent increase over 2020. For the year to December last year, revenues increased by 5.4 percent to $1.8 billion and gross profit came in at $893 million, 9 percent more than 2020.

Mailpac CEO Khary Robinson.

Net profit for the fourth quarter in 2021 ended at $115 million, 10 percent more than the $104 million generated for the same quarter of 2020. Full year profit came in at $400, down 9.7 percent from$443 million earned in 2020. The results delivered 5 cents per share for the December quarter and 16 cents for the full year.
Seprod Group achieved revenues of $11.76 billion, in the December quarter up 30 percent or $2.68 billion above $9 billion earned in 2020. Net profit was $455 million, 17 percent more than $389 million for the final quarter of 2020, excluding losses for discontinued operations but was up 18 percent to $373 million from $319 million in 2020 before accounting for discontinued business.
For the year to December 2021 revenues climbed 14 percent to $42.9 billion from $37.7 billion in 2020. Net profit fell to $2.16 billion from $2.87 billion in 2020. The fall resulted from a one time gain of $762 million from the sale of a property in 2020.