 Sterling Investments, the latest listing on the Jamaica Stock Exchange started trading on Monday with 56 trades ranging from 100 shares to 1,000 shares for a total of 10,075 shares. All the lots sold were executed by Proven Wealth Management, and only 3 lots purchased were done by other brokers.
at the close of trading, there were no stocks being offered for sale and no bids to buy. Sterling, a St Lucia registered company, was listed by introduction, as such there were no shares issued to the general public as an initial public offering. The total number of stock listed is 4,014,547 units which is up on the amount of 3.6 million reported in the 2013 audited accounts. The stock traded just below its net asset value of $138 per share at the end of June, but at a PE ratio of around 10.
Sterling Investment reported income of $70 million and comprehensive profit of $56.7 million, including $11 million from unrealized gain on investments, for the 2013 financial year. For the six months to June this year, income amounted to $25.7 million plus gain on sale of investments of $2.8 million and $25 million in Forex gains resulting in profit of $34 million for the half year. SIL generates interest income from the securities and capital gains realized from increases in the price of the securities.
Sterling Investments trades at $134
Producers’ improving performance
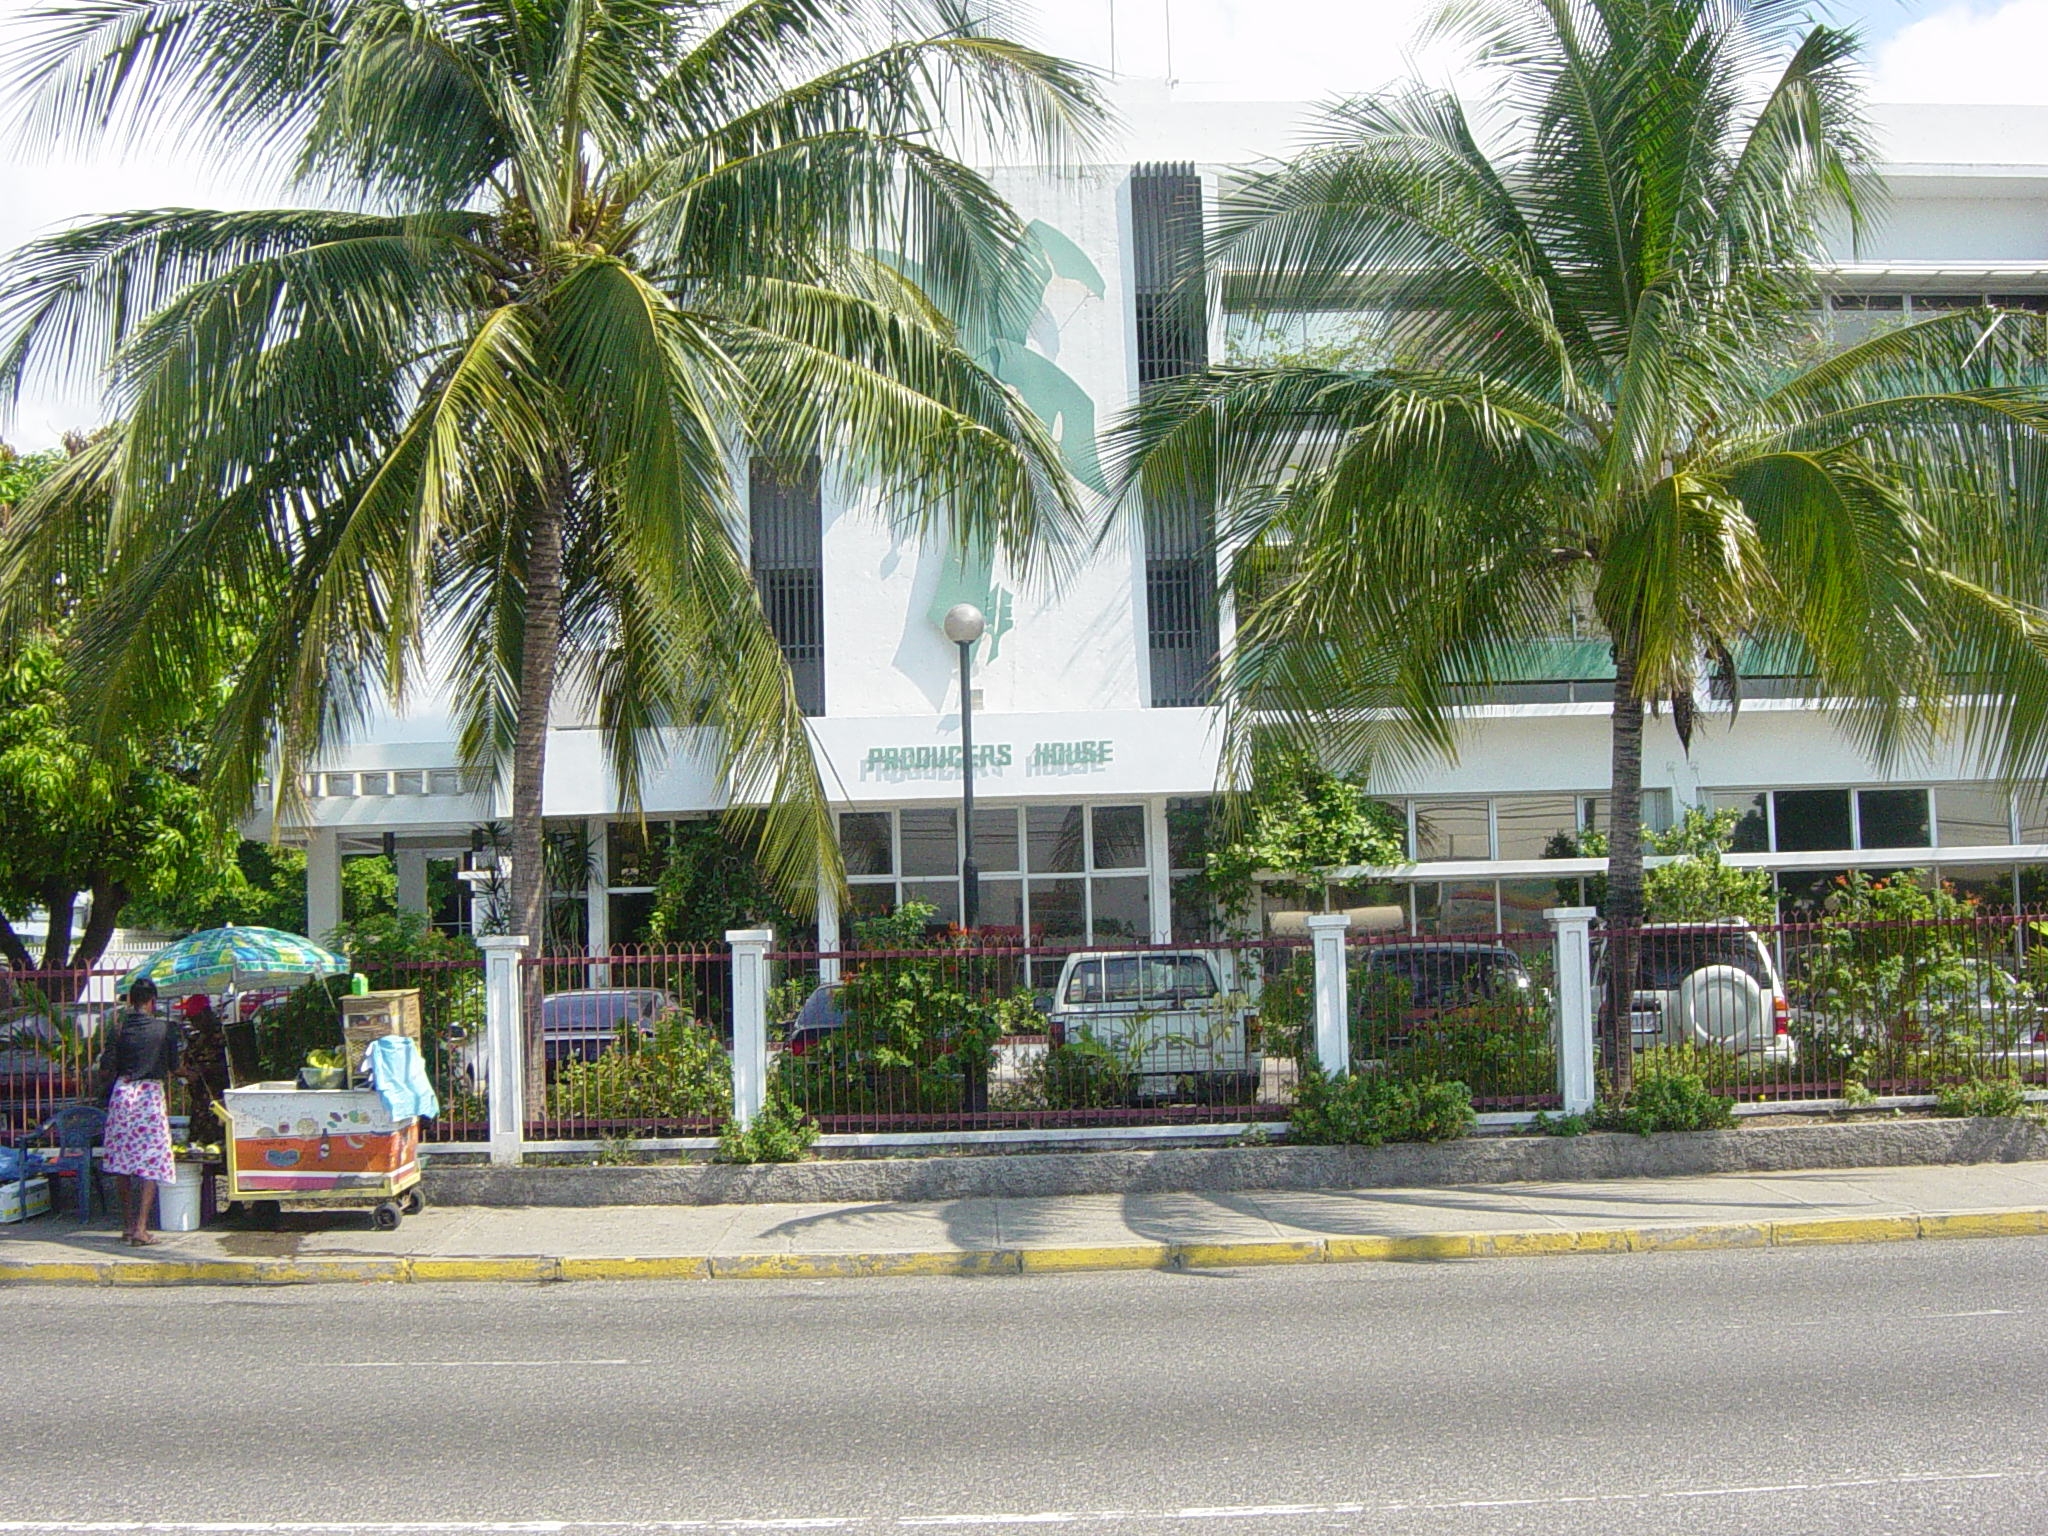
Jamaica Producers HQ in Kingston Jamaica
For the half year to June, net profit attributable to shareholders was $138 million, a 13 percent decline, compared with the similar period in 2013. This year’s performance only had $17 million of gain on sales of fixed assets and investments compared with $105 million in 2013. The 2013 result was negatively affected by $36 million in restructuring cost, there was no such charge this year, resulting in the quality of earnings from ongoing operations being better than in 2013.
Europe| In the 2014 second quarter, the Europe division earned revenues of $1.78 billion and pre-tax profits of $167 million, a 33 percent increase in revenues and 196 percent increase in pre-tax profits relative to the 2013 second quarter. Europe is still facing tough economic conditions, resulting in further monetary easing recently, leading to the Euro slipping sharply in value. This development could negatively affect Producers profit for the rest of the year. The results for 2015 could benefit from the monetary easing as the economy could benefit from the stimuli. The local currency could stay stable for some time thus robbing it of the gains make due to currency slippage in the first half of the year.
JP Tropical Division includes businesses located in the Caribbean that faced particularly challenging production and trading environment that adversely affected margins. The division experienced a loss during the 2014 second quarter of $43 million compared to a profit of $27 million for the same period in the prior year, although revenue grew 25 percent. The loss to JP shareholders is $20 million.
 JP Tropical Foods experienced growth in its snack foods product lines, particularly in the USA and UK markets. During the quarter, we launched a new tropical snack brand of plantain and cassava chips for the Dominican Republic market.
Gross profit climbed slower than operating revenues at 24.7 percent in the June quarter to $549 billion but was in line with revenues in the year to date period with gross profit rising 17.8 percent to $977 million.
Subsequent to the quarter the group acquired 11.59 percent more Kingston Wharves shares raising its stake to approximately 42 percent to become an even more dominant shareholder of the company. The rate of return on this latest investment is likely to be around 8 percent, or just slightly better than government of Jamaica current Treasury bill rate. But Producers’ focus would be on the longer term growth prospects that will accrue from the expansion of the port, and the increased business that they expect, especially with the opening of an expanded Panama Canal.
The main activities of the group are juice and food manufacturing, the cultivation, marketing and distribution of fresh produce locally, logistics, land management and the holding of investments.
Finances|At the end of June, the group had debt close to $1.2 billion, that should rise with the acquisition of the Kingston Wharves share purchase, as it was partially funded by borrowed money. Equity stood at $5.9 billion and they had cash funds and investments of $987 million. Current assets to current liability was below norm, at $2 billion to $1.5 billion.
Encouraging results| The results for 2014 so far is encouraging, importantly, Jamaica Producers is adding new products to the existing lines, both in the Caribbean and Europe, this is one of the surest ways of improving profitability as it is less costly to add new lines as much of the overheads cost are already built into the system. This is clearly a stock to be watched.
Pan Jam profit up 29% for Q2
 Pan-Jamaican Investment Trust enjoyed a strong 29 percent growth in profit, attributable to owners of the group, for the quarter ended June this year to $627 million. Profit of $486 million was realised in the 2013 second quarter. For the six months to June, net profit hits $1.07 billion, compared to $710 million for 2013, an increase of 50 percent.
Earnings per share amounted to $5.09 for the six months and $2.99 for the latest quarter, earnings for all of 2014 should end up around $12 per share. With the stock selling at $49, there is much room for the stock price to double, that is why it is one of IC Insider BUY RATED stock.
Total revenue was higher for the quarter compared to last year, by $125 million, or 30 percent, due to the improved investment and property income, and ahead of last year for the 6 months by $185 million, or 21 percent as the group generated income of $544 million in the latest quarter versus $419 million in 2013 and $1.08 billion for the six months, compared to $895 in 2013.
The share of results of associated and joint venture companies for the quarter is $537 million and is flat compared to last year, while the six month period share increased by 16 percent to $893 million. Last year’s results were significantly affected by the first quarter NDX impact on Sagicor.Investment income of $123 million, in the second quarter of 2014 was nearly three times higher than the $44 million in the similar quarter last year, principally as a result of better foreign exchange gains of $42 million, versus $23 million last year, and trading gains of $37 million, versus a loss of $21 million in 2013. Year to date investment income of $259 million is 79 percent ahead of 2013, due principally to trading gains of $89 million versus a loss of $29 million in the prior year. Property income grew $54 million, or 16 percent, compared to last year for the quarter and $83 million, or 12 percent, year to date.
Group operating profit for the second quarter increased by $115 million, or 73 percent, compared to last year’s second quarter. For the year to date, group operating profit of $544 million is $157 million, or 40 percent, more than last year’s level.
Operating expenses were contained to $273 million for the June 2104 quarter versus $263 million in 2013 and $536 million for the year to June from $508 million in 2013.
Total assets at June 2014 amounted to $25.1 billion, compared to $23.3 billion at December 2013. Bank and other loans stand at $4.48 billion and stockholders’ equity stood at $19.4 billion from $17.8 billion at December last year, equating to a book value per stock unit of $92.34.
Pan Jamaican is involved primarily in commercial property ownership and rental and owns just over 31 percent of Sagicor Group a life assurance and banking operations.
C2W Music shifts to new business model
 C2W Music announced today, that it will shift its business model, from music publishing to artiste management under the 360 model. The change is aimed at increasing revenue streams, at the cash strapped company, said CEO Ivan Berry, Saturday at the annual general meeting, held at the Knutsford Court Hotel, in Kingston.
“The 360 model is an all rights model. We are not in the music publishing business, we are now in the all rights business,” Berry told roughly 20 shareholders at the early morning meeting. “We are going to sign fantastic songwriters and create copyright, we are going to sign fantastic artistes and help them get global recognition and going to sign producers and make earnings from producer fees.”
C2W made a net loss of US$620,000 for 2013 which mirrored a US$602,700 loss, a year earlier and virtually wiped out the capital it raised in early 2012, leaving only US$42,000 at the end of 2013.
C2W will follow the model of global company BMG which sold its record label to Sony then immediately set-up BMG Rights Management. “It is tough operating without revenue and it will continue to be tough. As CEO we value the trust that shareholders have put in us and we will continue to grow this company,” stated Berry. “Where we need to go is to be a fluid flexible operation that can move in on the drop of a dime.”
Berry lamented that under the music publishing model the publisher is the first to spend cash and last to get paid.“As we give these artistes songs. The artiste immediately goes on tour and [earns] from our songs but we have to wait another 14 months for our royalties to be collected globally…we are the last to be paid,” explained Berry in his trademark muscle shirt and chain.
The shift actually reflects the more ‘Jamaicanised’ directorship which includes local music experts Sly Dunbar and Clyde McKenzie.
“So we are fast going into the 360 model…so that we get a piece of live shows, we get a piece of the endorsement deals, sponsorship deals and all that comes along with an artiste,” he concluded.
General Accident flat 2014 profit
 General Accident Insurance marginally improved profit for the first half of 2014, with net profit rising to just $187 million, from $178 million in 2013. Earnings per share for the six months rose to 18 cents. This year’s performance is not, however, as strong as last year’s 57 percent increase for the same period. For the June quarter, profit came out at $88 million up from $80 million in 2013. Investment income for the first half of 2014 was $125 million, well below the $145 million earned, in the first half of 2013.
For the year to June, gross premiums income grew to $3.44 billion, from $3.24 billion for the first half of last year. Net earned premiums grew to $485 million, from $443 million for the six months in 2013. Premium income fell to $1.9 billion from $2.09 billion and commission income ended at $90 million from $84 million, for the June quarter. For the six months, commission income amounted to $175 million, from $117 million for 2013. The company said, the performance was “as a result of improvement in our core business of underwriting commercial property and motor insurance.”
Claim expenses rose from $310 million for the year to June last year, to $316 million in 2014 and for the June quarters from $157 million to $169 million. Management expenses rose from $165 million for the year to June 2013 by to $2055 million in 2014, and in the latest quarter, from $88 million to $110 million
Assets down| Total assets totalling $7 billion at the end of June last year has seen a major fall to June this year to $4.3 billion mainly as result of amounts due from reinsurers and co-insurers and from policy holders declined back to normal levels. Equity stood at $1.55 billion and cash and short term investments stood at $2 billion.
If the company can maintain the current profit levels then earnings per share should reach 35 cents for the year which makes the stock now priced at $1.62 cents cheap, at a PE of only 4.6.
Purity’s 2014 profit & stock price falls
 Periods of major economic adjustment negatively affecting consumers, can be tough for bakeries, as demand pressures tend to squeeze margins. That is exactly what happened to Consolidated Bakeries, better known as Purity, for the first six months of 2014.
For although sales’ revenues for the period to June 2014, grew 17.9 percent over the six months to June 2013, profit fell 19 percent to $14.7 million from $24.4 million in 2013. Profit, in the June quarter fell 28 percent to $7.3 million while sales’ revenues for the quarter rose 22 percent. During the six-months, Consolidated said, exports grew 25 percent in US dollars, over the same period last year.
According to management in their report to shareholders for the June results “revenue growth over the six month period in 2013, represent growth in all product categories. This growth is a result of our strategy to grow distribution and volume. During this period, price increases were low due to market competition and in a response to difficulties shoppers face.”
Gross profit| Gross profit margin that ended last fiscal year at 54 percent, fell to 44 percent in the March quarter, 47 percent for the June quarter and for the six months 46 percent. The decline was a major factor dragging profit down for 2014. For 2011, gross profit ended at 62 percent, leaving much room for improvement for management going forward.
Operating cost| comprising administrative, selling and distribution cost, rose sharply by 21 percent for the June quarter to $57 million and 15 percent for the six months, hitting $113 million, faster than the increase in gross profit.
The company has lots of work to do, to improve gross profit margin as well as the paltry return on equity of 6 percent for 2014.
Borrowed funds amount to $57 million at the end of June at a very comfortable level with equity at $518 million. Cash funds available amount to $111 million.
Property plant and equipment was increased by $17 million up to June 2014, additional machinery was ordered to build capacity.
Watch this one| The company has room to grow faster than the economy for a while, this can make it a good growth prospects for investors looking long term. IC Insider’s forecast for earnings per share is around 15 cents for 2014. It may not be until 2015 that the earnings could show improvement to help push the stock price upwards in a major way.
Trading volume & main indices up
strong> Thursday’s activity on the Jamaica Stock Exchange, resulted in the prices of 4 stocks rising and 7 declining as 21 securities changed hands, cumulating in 8,271,202 units trading, valued at $38,526,528, In all market segments.
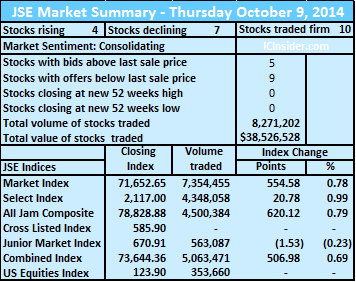 Main Market| The JSE Market Index gained 554.58 points to 71,652.65 and the JSE All Jamaican Composite index rose 620.12 points to close at 78,828.88.
IC bid-offer Indicator| At the end of trading, in the main and junior markets, the Investor’s Choice bid-offer indicator showed 5 stocks with bids higher than their last selling prices and 10 stocks with offers that were lower, with the junior market having 6 of the lower offers.
Gains| Stocks gaining with last traded prices, at the end of trading in the main market are, Grace Kennedy with 118,600 shares trading, gaining $2.45 to $59, Jamaica Broilers 17,931 shares traded with a gain of 34 cents to $3.85, Kingston Wharves with 88,794 shares changing hands, gained 50 cents to $5.50 and Scotia Group closed with 31,749 units with a gain of 48 cents at $19.50.
Firm| The stocks in the main market to close without a change in the last traded prices are, Ciboney with only 200 units at 7 cents, Desnoes & Geddes with 2,286,959 shares at $4.70, Radio Jamaica with 3,900 share trading closed at $1.04, Sagicor Real Estate Fund had 33,100 units changing hands to close at $6.60 and Supreme Ventures with 1,044,250 shares trading to close at $1.80.
Declines| The last traded prices of stocks with losses at the end of trading in the main market are, with shares, lost cents to end at , traded just units at loss and with only.
Cable & Wireless with 839,349 shares, closed with a cent loss at 29 cents, Carreras with 9,220 shares lost 15 cents to end at $34.50, Pan Jamaican Investment 15,300 units trading lost a cent to end at $49,
Proven Investments with 353,660 shares lost I cent to end at 17 US cents, Sagicor Group closed with 9,260 shares trading as the price ended down 1 cent at $9.50 and Scotia Investments 1,772 shares trading dropped 4 cents to end at $21.71.
Preference| Jamaica Money Market Brokers 8.75% preference share traded 2,852,171 units at $3.02 and Proven Investments 8% preference share traded 1,900 units at $5.
Seprod & Lasco Distributors hike dividend
 Seprod will pay a dividend of 35 cents per share on November 14, to shareholders on record as at October 31. The stock will trade ex-dividend as of October 29.
Seprod paid a dividend of 55 cents per share on July 4, this year. Last year a dividend of 30 cents per share was paid on November 15 and 53 cents per share on July 8 Lasco Distributors declared an interim dividend of 3 cents per share payable on December 9, 2014 to shareholders on record as at November 25, 2014. The stock will trade ex-dividend on November 21, 2014. An interim dividend of 2.3 cents per share was paid on December 10, 2013.
Medical Disposables & Supplies declared an interim dividend of 4 cents per share payable on November 19, to shareholders on record as at November 14. The stock will trade ex-dividend on November 12, 2014. This is the first dividend the company is paying since listing in December last year.
Knutsford Express profit grows
 A strong 88 percent jump in Knutsford Express’ fourth quarter revenues to May this year, slowed to 44 percent in the August quarter, to reach $103.4 million, up from $71.9 million in the 2013 quarter, producing only a 20 percent rise in net profit of $17 million.
The growth from continuing operations is greater than the figures on the surface suggest as 2013 figures include $4.7 million in one off income, excluding this, profit before tax would have climbed an impressive 44 percent, in line with the growth in revenues. Earnings per share ended at 17 cents for the August 2014 quarter, with signs of continued growth in revenues, earnings for the 2015 fiscal year should end up around 80 cents to $1 per shares
With such earnings, the stock at a $5 price has an interesting valuation, with some growth potential, that could put in the stock price somewhere in the $8-10 range over the next nine months or so. The company’s finances continue to be healthy, with little debt, equity of $177 million and cash of $67 million. For the 12 months to May, this year, pretax profit climbed marginally to $56 and the May 2015 profits seems set to far surpass this amount.
The company provides a passenger coach service from Kingston to Negril via the north and south coast of Jamaica, several times per day.
Lasco shares sell & buy FX or hold
Our response back then, thanks for your enquiry. As you will see our BUY RATED list contains these three stocks. Here are our views. First off the local stock market tends to go down around May until last June or July. This is not cast in stone, just a tendency. One reason for it is that investors get the full information as to what companies did last fiscal year and a glimpse for the new-year. In the case of the three Lasco companies they have just reported their full year results. The distributorship earning is the most encouraging of the three and looks like it will probably do better than the other three in the short to medium term. It will also benefit from the Salada Foods distribution which started this year, as well as from increased production to come from the expanded Lasco Manufacturing Company’s operation. The information suggest that the next set of results should possibly show growth over that of 2013.
Lasco Financial seems poised for good things but big marketing spend last fiscal year kept profits down as they went for more market share. It does look as if they will be spending on the world cup promotions which could build business, but may also keep profits pressured somewhat for a while.
Lasco Manufacturing seems cheap at $1 bearing in mind the impact that the factory expansion is likely to have on both sales and profits ultimately. Short term they will have to pick up interest cost and depreciation on the completed factory but will enjoy cost savings and ultimately increased profits.
It is my view that the market overall, is undervalued but investors will need to be patient and the payoff is likely to huge for those who wait, the gains to be reaped elsewhere is not likely to be all that great, to cause one to jump and possibly miss the gains in the local market that is ahead.