Flat sales higher cost hit Lasco Manufacturing
Earnings per share fell to 3 cents for the quarter and 7 cents for the six months. Year to date revenue was $2.08 billion compared to $1.88 billion for the same period last year, an increase of 11 percent. “This growth was driven mainly by increased volume in our export markets. Our International Division reported a growth of 40 percent during the quarter” management stated in their release with the financials.
Gross profit for the six months rose 14 percent to $602 million from $526 million and in the September quarter it grew to $287 million from $276, bettering gross profit margin moderately. Net profit for the six months declined 15 percent to $268 million against the comparative period last year. “The net profit performance was in line with the expectations of management and the board, this was due to temporary increase in manufacturing cost resulting from the effect of changes in staff complement, overhead costs associated with the new manufacturing plant, and increased finance cost,” the company’s management stated.
Operating expenses climbed 54 percent to $151 million in the latest quarter, and 41 percent, for the six months period. While there is no breakdown for the operating cost, other than the increased staff cost mentioned above, increased depreciation charge on the liquid factory would also be one of the factors pushing cost. With the other factory to be opened after the quarter’s end, the depreciation charge will rise again. Finance cost jumped to $25 million in the quarter from just $2 million in the 2013 quarter and for the half year to $57 million from $2.3 million. Prior to the completion of the factory, the finance cost associated with building and equipping the factories was capitalised as part of the factory cost. With the completion of the facilities, the cost will be a direct charge against income.
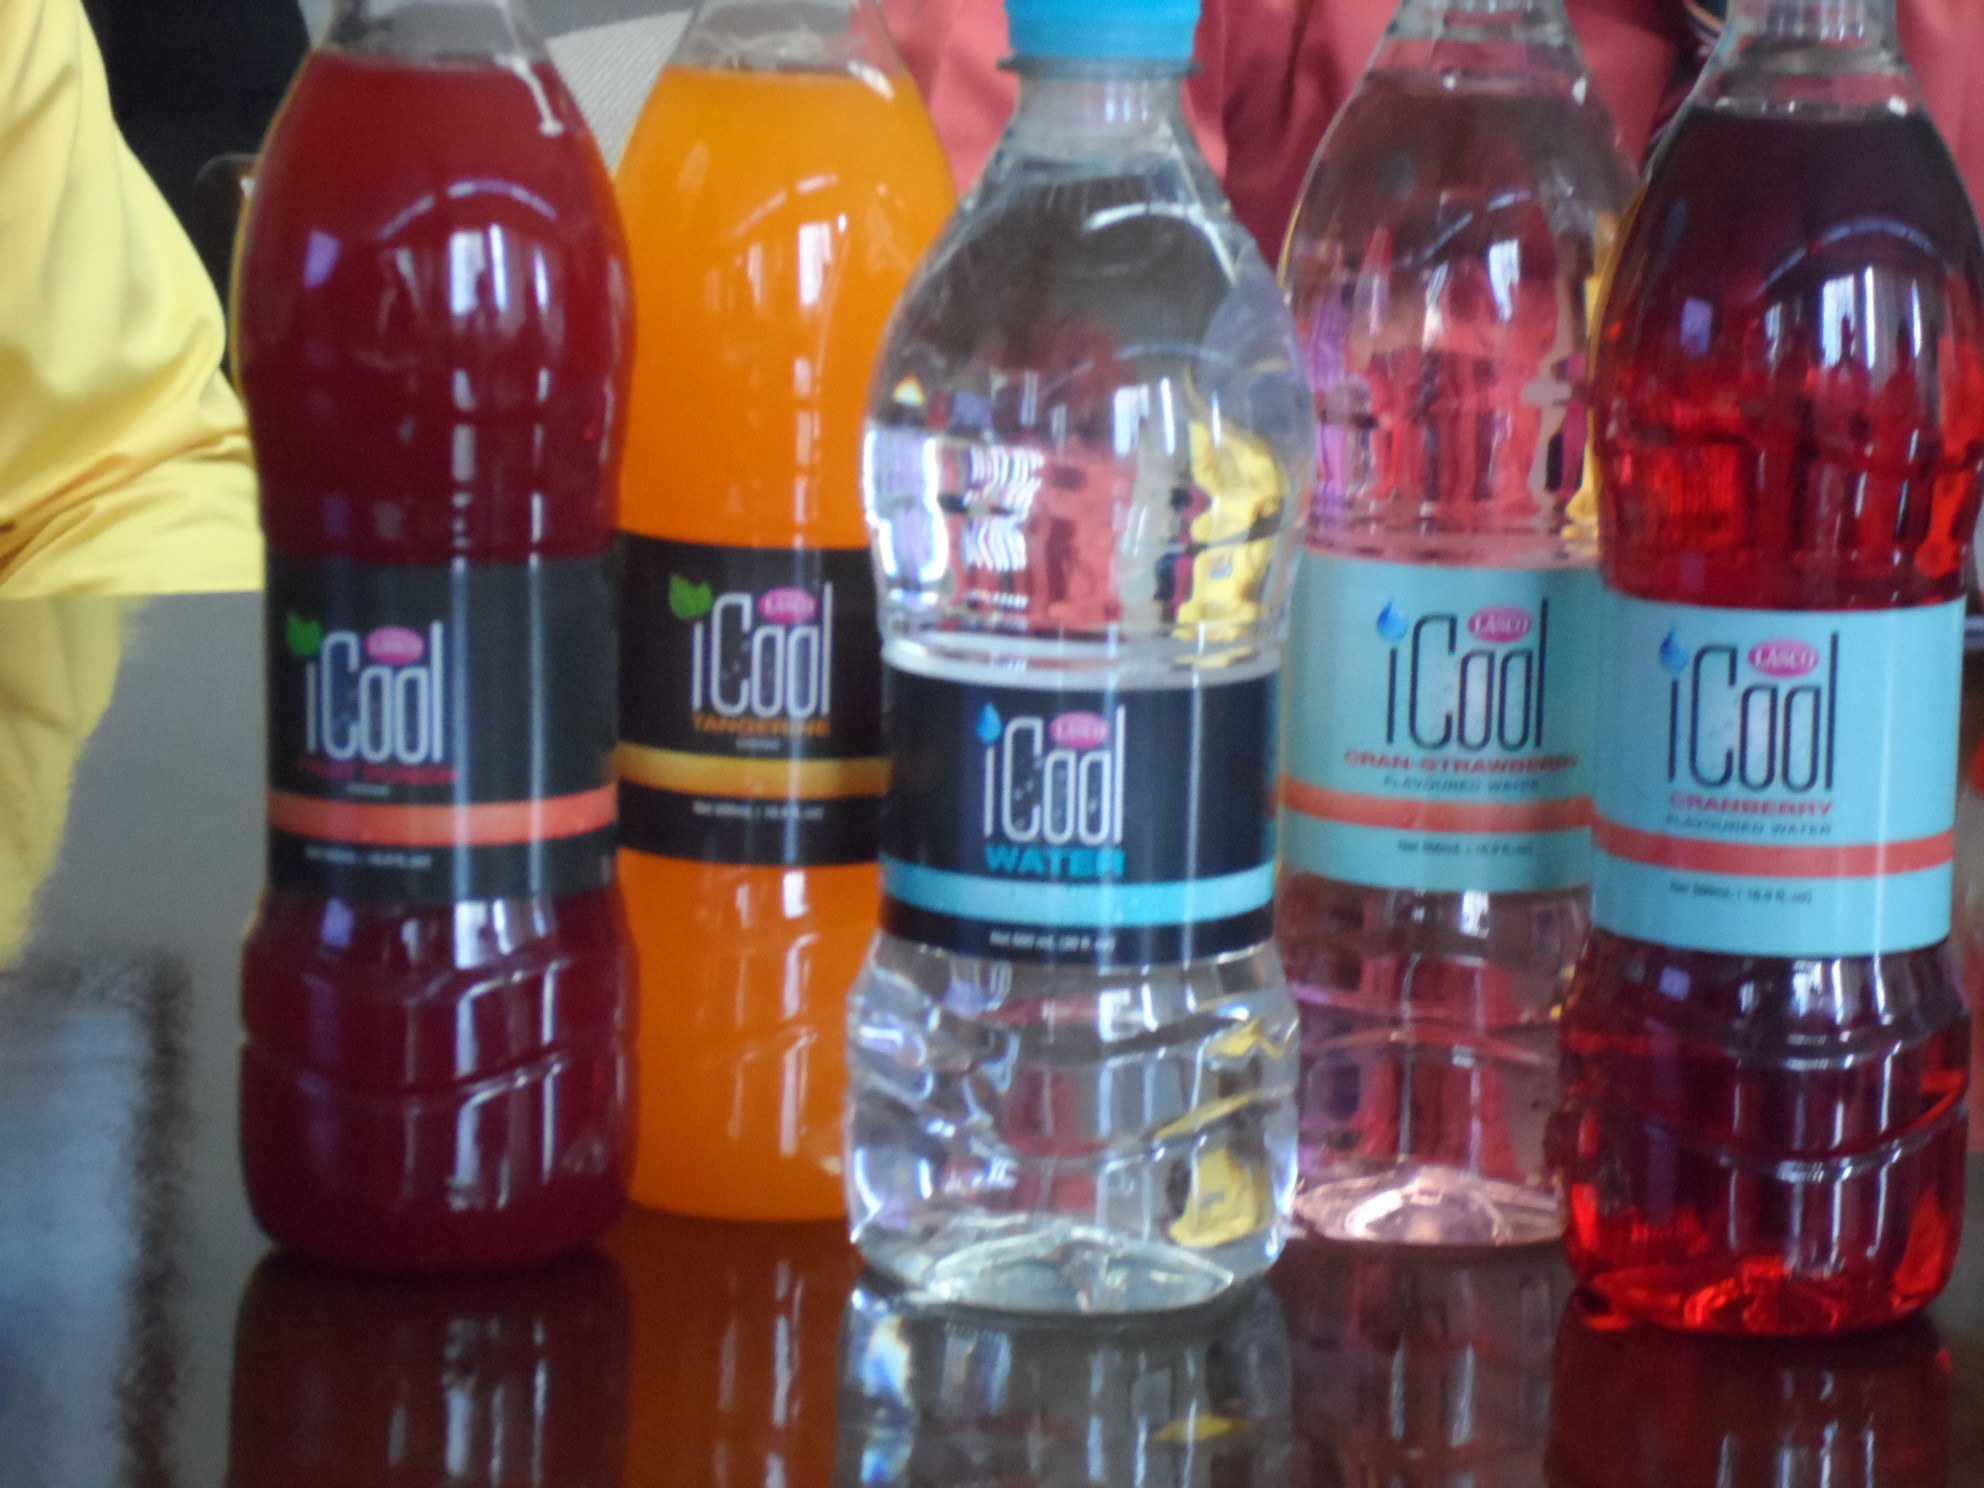
During the quarter, the company introduced LASCO iCool water, iCool flavor water and iCool juice drinks to the market. The company made significant investments in marketing as well as promotional activities in collaboration with affiliated company LASCO Distributors.
“The company is on target with its long-term plan to invest in innovation across all facets of the business – from new product development to powering a pipeline of new products, drive financial performance and fuel continued consumer passion for the LASCO brand,” management stated.
Finances| At the end September, borrowed funds was at $1.49 billion with $187 million to be paid within the next twelve months, while cash funds were at $153 million. $2.1 billion is in work in progress to be transferred to fixed assets and will push total fixed assets to $3 billion when effected. The company is also in the process of constructing a new warehouse of 30,000 square foot. Up to the end of the September the company was operating from two factories one at the White Mall facilities as well as at Red Hills Road, thus resulting in duplicated cost. The liquid plant is to be up graded further by $3 million to reduce raw material cost and expanded for other products, including production for some foreign partner.
Lasco Financial rolls out profit gains
For the six months to September, profit is up by 25 percent to $112 million or 9 cents per share and revenue climbed 14 percent to $366 million from $303 million in 2013. All things being equal, the full year earnings to March next year should exceed 20 cents per share.
Cost rose 19 percent in the six months as increased marketing cost helped push cost up, but the increase for the September quarter was only 14 percent. The company is embarking on some new initiatives to expand the business. One will be the utilization of 14 locations island-wide for the provision of loans. They indicated earlier this month that they have already signed an agreement to facilitate this. New software that that has been installed will allow for Money Grams’ data to reside locally and thus speed up the processing in the money transfer transactions, thus creating a better experience for their customers. The focus in this area, is a partial recognition that that the traditional business of cambio and to a lesser degree remittance services are fairly matured and growth has to be explored elsewhere.
Lasco Financial should generate in excess of 40 percent return on equity for the current fiscal year. As of September, equity stood at $726 million, loans and other receivables on the books is at $325 and cash funds $448 million.
A look at Access with return on equity of more than 50 percent, contrast with Lasco Financial more than 40 percent. For one, it indicates that high risk lending is very profitable area if done right as well as the benefit that leveraging can deliver, with Access borrowing funds to relend versus Lasco using its own capital alone.
NCB to face $500m wages hit in 2014
National Commercial Bank (NCBJ) advised that the Industrial Disputes Tribunal made an award in respect of salaries and benefits for most of the clerical employees of NCBJ and its subsidiaries (NCB Group).
The award included an increase in salaries of 8 percent per annum for each of the financial years ending September 2013 and 2014. The increases for those years will now have to be paid retroactively. NCB Group said they make provision for salaries to be increased once the award was received, but the increases awarded exceed the amounts provided. The extent to which the retroactive payments for those two financial years exceed the provisions that had been made will be taken into account in the income statement for the financial year ended September 30, 2014. Union leaders for the staff association claimed that the bank offered five percent for 2013 and four percent for the current year. Such an offer would mean that the group would need to book an additional 7 percent to the wage bill. The groups wage bill was approximately $11 billion for the 2013 fiscal year to September and would place the additional charge, somewhere in the $800 million region. The net effect would be closer to $500 million or around 20 cents per share after tax. The bank’s wage bill for the 2013 financial year was $9.5 billion.
IC Insider originally projected earnings of $4.80 per share for the 2014 fiscal year. The adjustment to be reflected in the 2014 accounts will most likely results in a lower out turn.
Revenues up strongly at Access
Access Financial Services’ profit increased 13 percent in the June quarter and is up by 17 percent in the September quarter, to reach $93.57 million that is still down from the robust 30 percent increased profit, in the March quarter.
The third quarter profit grew much more slowly than revenues that grew 31 percent to $272 million and slightly more than in the second quarter’s $267 million and $254 million in the March 2014 quarter.
For the nine months to September, profit is up by 20 percent to $239 million or 87 cents per share. The company becomes taxable in the December quarter, but earnings should surpass $1.20 per share for the full year. In the nine months to September, revenues climbed 37 percent to $793 million from $579 million in 2013, continuing its strong growth trajectory since the shares were listed. The December quarter is traditionally the biggest quarter in income and profit generation. All things being equal, the earnings of 34 cents in the September quarter, should be well surpassed and putting full year earnings around $1.40 per share.
Increase in the provision for bad loans climbed much faster than revenues in 2014 so far, with $54.6 million provided in the latest quarter, bringing the nine months to $169 million compared with $52 million in 2013. The nine months provision amounts to 23.4 percent of the loan income, this is a major increase from 12.6 percent for full twelve months of last year.
Access should generate in excess of 50 percent return on equity for the current year. As of September, equity stood at $744 million, loans on the books is at $1.1 billion, a 26 percent jump from $889 million at September last year. Total borrowed funds used in the financing of the business, amount to $582 million compared to $422 million in September last year, cash funds stand at $146 million.
The company paid a dividend of 36.5 cents per share payable to shareholders on September 1st this year.
Dividend likely for Eppley
The Board of Eppley Limited will meet on Thursday, November 13, to consider the payment of an interim dividend.
For the current year, Eppley paid an ordinary dividend of $9 per share on September 2. An ordinary interim dividend of $9 per share was paid on May 29 and $9 per share was also paid on February 28, this year.
Profit before tax, was up 67 percent for the six months to June this year, but only 21.5 percent in the June quarter, and after tax it was up 112 percent for the quarter, and 119 percent year to date, for a net profit of $29.6 million. There is no tax payable of the profit for the current year, as the company enjoys tax free status for 5 years, under the junior market listing incentive.
Proven to consider a dividend
The Board of Directors of Proven Investments will to consider dividend payments to both its ordinary and preference shareholders at a meeting on November 4.
A dividend of US$0.0022 per ordinary share was paid on December 3, last year. For 2014, the investment company, paid dividends of US$0.0020 per share to ordinary shareholders on June 24 and US$0.0015 per ordinary share, on March 13, this year.
The net profit for the quarter to June 2014, excluding a loss on extra ordinary activities and gain on purchase of subsidiary amounted to US$1.18 million, an increase of 14.3 percent, compared to the same period last year.
JMMB to consider a dividend
The Board of Directors of Jamaica Money Market Brokers will meet on November 7, to consider an interim dividend payment on the company`s ordinary shares.
The company paid a dividend of 17 cents per ordinary share on June 26, this year. A payment of 16 cents per share was made on December 18, last year.
JMMB Group posted net profit of $558 million and earnings per share of 34 cents for the quarter to June this year, 26 percent lower than the $754 million earned in 2013. The decline in the June quarter, contrast with a 5 percent increase in profit for the March 2014 quarter over the 2013 period.
D&G to up December’s dividend?
The payment of a dividend based on the financial year ended June, 2014, will be considered by Desnoes and Geddes at a meeting scheduled for Wednesday, October 29.
The company paid an interim dividend of 20 cents per share and a special dividend of 5 cents per share on December 20, last year.
They also paid interim dividend of 10 cents per share and a special dividend of 15 cents per share on May 16, this year. Profit after tax, for the 2014 fiscal year was $3.15 billion, but excluding the gain from the shares the company had in two breweries in the eastern Caribbean, it would have been $2.2 billion or an increase of 80 percent, instead of the 160 percent increase the net result shows. This means that shareholders can look forward to a healthy increase in the dividend to be declared.
Profit climbs 21% at Margaritaville
Revenue jumps 30.7 percent to US$1.7 million, in the first quarter, ending August and pushed up gross profit by 33.24 percent to hit US$1.267 million, as margin improved over the similar quarter in 2013, at Margaritaville Turks Ltd. It was not all good sailing for the second US dollar listed stock on the Jamaica Stock Exchange, as administrative cost climbed faster that revenues at 37.76 percent, and kept growth in profit to US$245,000, for a 21.18 percent increase.
Full year profit| For the current year, based on the growth in revenues so far, profits should climb to US$1.6 million, up from US$732,000 in twelve months to May this year and result in earnings per share of 2.4 US cents and put the PE of the stock at 4.6 making it an attractive buy currently. The standalone business depending on ships docking is not without added risk, a factor that investors should be cognizant of. The shares are not in great supply but there are offers ranging from 11 US cents to 18 cents but there has been no buying interest for weeks.
Construction of a new restaurant, is to commence in the second quarter of the financial year and end in the third quarter, to expand their offerings to customers.
Concerns| The company has little debt, but has a big jump in the amounts owing to creditors, growing from $716,000 to $973,000 while amounts owing by related companies to it, jumped sharply, from $424,000 to $987,000. This is not a good sign and there is not even an ounce of comment by management about this unusual buildup of these amounts. While all of this is happening, cash is down to only $4,000 from $58,000 a year ago.
Margaritaville is new to listing on the stock exchange, but they need to get a few things right. The prospectus stated that the shares would be listed on the stock exchange main market, the audited statement for 2014 says the same, and the current report repeats it as well. These are all incorrect as the shares are listed on the US dollar denominated market, which differs from the main market. The actual financial statement does not provide readers with the number of shares issued, this should be a part of the financial statement. The listing of the number of shares issued in the top 10 shareholders is not a part of the financials and investors should not have to look there for it.
Price increase to push Witco 2015 profit
Trinidad’s West Indian Tobacco (Witco) raised prices on cigarettes approximately 15 percent, effective October. The increase should push revenues to over $1.3 billion dollars in 2015, from TT$1.185 billion in 2013.
An increase of that level on top of one in 2013 will most likely reduce the volume of sales on the Trinidad market, where the increase was effected. The price adjustment should help boost next year’s profit and by our calculation that should hit $700 million after tax or around $6.80 per share. That would put the PE ratio of the stocks at just over 17 times next year’s earnings and should help move the stock back into the $20 region which should be helped with an expected increase in dividends in the region of the EPS.
Witco’s profit jumped 23.5 percent in the June quarter, this year to hit $127 million as revenues climbed by a smaller 15 percent, to $324 million. For the six months to June, profit is up to $224 million from $188 million, a 19 percent spurt, from revenues of $590 million versus $556 million in 2013. Earnings per share came in at $1.50 for the quarter and $2.65 for the half year. Earnings for the full year to December should reach $5.70 per share.