Stationery & Office Supplies drops in 2025


A six percent rise in revenues in the first nine months of 2025 melted down to a modest 1.3 percent for Stationery & Office Supplies (SOS) for the year, to $1,866 million, over $1.843 billion recorded in 2024, following the negative impact on sales caused by the impact of Hurricane Melissa in the last quarter.

While the top line held up well, supported by a 50 percent surge in export sales across the Caribbean region and strong growth from the EVOLVE furniture line, the bottom line came under considerable pressure, partially affected by the impact from the hurricane and lower margins from exports.
Stationery & Office Supplies hit a record high on Friday.

Stationary & Office Supplies – Montego Bay office.

Gross profit for the year came in at $953 million, down 5.5 percent from $1.01 billion in the prior year. The gross profit margin narrowed from 54.7 percent to 51.1 percent, reflecting higher shipping and input costs that the company chose to absorb, as well as the lower-margin profile of the growing export business. Cost of sales rose to $913 million from $835 million, a 9.4 percent increase that meaningfully outpaced revenue growth.
Administrative and general expenses climbed 7.2 percent to $612 million, driven largely by a 9.5 percent increase in staff costs as the workforce expanded from 162 to 170 employees and management remuneration that rose to $142 million. Selling and promotional expenses were essentially flat at $154 million, while depreciation and amortisation held steady at $45 million. Total expenses for the year reached $828 million compared to $785 million in 2024, a 5.5 percent increase.
Operating profit fell sharply to $137 million from $228 million in 2024, a decline of approximately 40 percent. Net finance income of $11 million and foreign exchange gains of $10 million, resulted in pre-tax profit for the year of $160 million, down 35 percent from $247 million in the prior year. The effective tax rate was approximately 17.4 percent, after accounting for a 50 percent tax remission as a Junior Market listed company. Net profit after tax amounts to $133 million, well below $223 million in 2024, a fall of 40 percent.

Earnings per share for the full year was 6 cents, down from 10 cents in 2024. The company paid dividends of $45 million during the year, representing 2 cents per share, the first dividend distribution since 2023.

Fourth Quarter 2025
The fourth quarter was severely disrupted by Hurricane Melissa, with Revenues declining by 14 percent to $377 million, from $437 million in the same period of 2024. Gross profit collapsed by around 50 percent to roughly $105 million as storm-related inventory losses at the Montego Bay warehouse and reduced trading activity weighed heavily on results. Expenses for the quarter declined 11 percent to approximately $183 million as the company curtailed discretionary spending. The net result was a pre-tax loss of approximately $6 million for the quarter, compared to a pre-tax profit of $15 million in Q4 2024, a swing of $21 million. The quarterly EPS was aa loss of 0.2 cents.

Segment Performance
The Furniture segment remained the powerhouse of the business, generating revenues of $1.35 billion in 2025, up 9.6 percent from $1.23 billion in 2024, with a gross profit of $760 million and a segment gross margin of 56.4 percent. The Book segment, representing the SEEK brand, saw revenues decline sharply to $76 million from $106 million, with gross profit falling to just $6 million from $27 million, reflecting both hurricane disruption and the pre-commissioning stage of the new factory. Stationery and other supplies posted revenues of $441 million, down 13 percent from $506 million, generating a gross profit of $187 million at a margin of 42.4 percent.
The company had an official opening for the Seek factory a week ago, with reports that it elicited some fresh orders and increased interest in the products that are manufactured. As the leading player in the office and stationery business smaller players who may want to exit the business will most likely look to them to be acquired. This is an ever present possibility, so investors should not be surprised if there are such developments in the future that could push revenues and profit.

Balance Sheet
urrent assets at year end stood at $1.06 billion, with current liabilities of only $358 million, with a net current asset of $701 million, a modest improvement from $687 million in 2024. Cash and equivalents rose 15 percent to $382 million from $332 million. Inventories grew 4.5 percent to $416 million. Shareholders‘ equity increased to $1.64 billion from $1.55 billion, with a net asset value per share of 73 cents. Long-term borrowings, totalled $17 million, down from $27 million.
The company generated gross operating cash of $201 million, after favourable working capital movements and tax and interest payments, net operating cash flow was $215 million, ahead of the $187 million generated in 2024. Capital expenditure consumed $114 million, primarily on the SEEK factory build-out, motor vehicles and computer equipment. Financing outflows of $69 million included the dividend payment, lease repayments and loan servicing. The net increase in cash for the year was $50 million.
ICInsider.com projects earnings per share for 2026 at 15 cents at a PE ratio of 12.3 times earnings at $1.85 the stock last traded at on Thursday. This compares to the Junior Market average of 15.6 currently. At the close of trading on Thursday supply of the stock for sale has dried up with only 7 offers of 149,000 share for sale. Watch this stock that could deliver a 50 percent gain or more for the year.
Transjamaican stock doubles in 2023

Transjamaican Highway stock closed trading on Wednesday with a gain of 105 percent at a record close of $2.87 on Wednesday and traded at a record $2.95, up 111 percent on Thursday morning, to be one of only two stocks on the Main Market of the Jamaica Stock Exchange to gain more than 100 percent for the year to date, the other being Ciboney up 139 percent.

New record high for the JSE Junior Market.

Investors in Transjamaican, the operators of Highway 2000 have much more to cheer about as the company raised the dividend to be paid in October by 118 percent to 18.66 cents up from 8.55 cents last year. The dividend adds another 13 percent to their return for 2023 based on the opening price for the year of $1.40. While the 2023 performance is a big reward for investors in the stock, it has been a long wait for early investors who bought in the IPO at $1.41 in February 2020, valued then at a PE ratio of 25 times, when the market was averaging 16 times. Critics of the value at the time indicated the serious overvaluation but supporters hailed it as reasonably priced. Now the stock is trading at less than 10 times 2023 earnings of 30 cents per share and buyers have been less than ecstatic about it, by slowly driving the share price to current levels over several months.

Transjamaican Highway

The stock’s performance is supported by an outstanding jump in profits for the six months to June over the similar period last year, with earnings of 14 cents per share versus just 3 cents for the same period last year, with the profit ballooning 338 percent for the June quarter to US$6 million and 442 percent to US$11 million for the half year. Revenues and profit rose as a result of the acquisition of its new subsidiary, Jamaican Infrastructure Operators which reduced cost considerably as well and the group benefitted from increased revenues from operating the toll road. The stock’s performance was also helped by the declaration of the substantial increase in dividend.

Transjamaican breakout

Transjamaican Highway (TJH) reported record revenues of $65 million for 2022, up 12.3 percent from $52.76 million generated in 2021, resulting in profit of $9.3 million before the one off cost, up a solid 74 percent above the $5.34 million generated in 2021.

The company reported a loss of US$7 million for 2022 after tax and after factoring in a onetime loss of US$13.7 million resulting from the acquisition of the major share of Jamaica Infrastructure Operators, the loss compares with a profit of $4 million in the previous year.
The above acquisition “will result in future cost savings, expected to significantly reduce Operating Expenses by more than 50 percent or US$12 million per annum and increase our profitability,” the directors informed shareholders in their commentary on the results. ICInsider.com projects earnings  of 0.016 US cents per share or J$0.24, giving it a PE of 7 and a target price of J$4.50.

In addition, it is worth noting that the vast majority of costs are more or less fixed, with Amortization of intangible assets amounting to $13.7 million, up from $12.3 in 2021, finance cost slipped slowly to $14.7 million in 2022 from $15.3 million in 2021. Operators fixed fees amounted to $17.7 million, up from $16.4 million but will drop in 2022, now that TJH owns the operating company. The company has been selected as the operator for the May Pen to Mandeville leg of Highway 2000, which will add to future revenues and profits.
In their commentary of the full year results, the company directors stated that “traffic since the advent of Covid19 has fully recovered and was approximately 7 percent above our 2019 pre-covid levels and 13 percent above the 2021 traffic”.
Gross cash flow brought in $10 million but with growth in receivables, inventories, addition to fixed assets offset by loan payment of $6.6 million, increased payables and paying $7 million dividends, the company ended with a net outflow of $1.3 million and closed with $5.4 million in cash funds.
At the end of December, shareholders’ equity stood at $40 billion or $3.20 per share—long term borrowings at $224 million and short term at $10 million. Current assets ended the period at $6.3 million, which comprises mostly the above cash and bank balance. Current liabilities ended the period at $16.5 million. Net current assets ended with a negative amount of $10 million.
All amounts are in US dollars unless otherwise stated.  

31% Express Catering rebounding profit

Tourist arrivals passing through Montego Bay rebounded strongly in the August quarter just a fraction less than the previous high mark in 2019 pushing revenues at Express Catering up 35 percent for the first quarter of the 2023 fiscal year to August to US$4.9 million as profit surged 31 percent to US$652,841, even as the 2021 period benefited from a rental concession of US$351,544, with none in the latest quarter.

Ian Dear, Managing Director of Express Catering

The company also released full year results showing continued recovery from last fiscal year’s fallout, with a profit of US$1.1 million, up from a loss of USUS$1.73 million in 2021. In contrast, in the nine months to February, profit was just US$364,607, with only US$120,248 of it generated in the February quarter.
Sales jumped 223 percent for the year to US$14.24 million from just US$4.4 million in 2021. For the fourth quarter, revenues rose to US$4.6 million, just 7 percent behind the August 2022 quarter and well ahead of the US$933,000 generated in 2021.
According to directors Ian Dear and John Byles, “total passengers accessing the departure lounge at the Sangster International Airport during the quarter were just below 623,000 or 37.44 percent higher than the similar period last year.” The directors also stated that they expect the trend to continue for the rest of the fiscal year.
Gross profit margin remained stable at around 65 percent for all periods from 2021, but input rose a tad faster than sales, with that for the latest quarter rising 40 percent and 228 percent for the fiscal year. The effect, gross profit rose just 32 percent in the August quarter to US$3.17 million from US$2.4 million in 2021 and increased 220 percent for the 2022 fiscal year, to US$9.3 million from US$2.9 million in 2021.
Administrative expenses rose 24 percent to US$1.23 million in the August 2022 quarter and increased 100 percent in the year to May, to US$5 million. Depreciation charge moved from US$2.4 million to US$2.78 million for the fiscal year and was stable at US$678,000 in the latest quarter. Finance costs rose in the quarter, to US$522,000 from US$515,000 in 2021 and from US$1.9 million to US$2.1 million for the year to May.
Gross cash flow brought in US$1.35 million, with US$1 million advanced to a related company, in addition to fixed assets consuming $298,324 and lease payment absorbed US$475,222.
At the end of August, shareholders’ equity stood at US$3.9 million with borrowings at US$33 million. Current assets ended the period at US$12.6 million, with US$11 million due from related company, without a date for repayment and on which no interest is charged even as the company is due to pay interest at around 12 percent per annum on funds it owes. Current liabilities amount to $6.47 million and Net current assets ended the period at US$6.1 million.
Earnings per share came in at 0.04 US cents for the quarter and 0.067 US cents for the fiscal year, If the company passed on the interest cost to the related party, profit for the quarter would be higher by around U$350,000 for the quarter, assuming no amount changed back for the prior years and more than US$1 3 million for the year.
ICInsider.com forecasts 40 Jamaican cents per share earnings for 2023 fiscal, assuming no interest is charged on the intercompany debt. The rebound in tourist arrivals only came back to 2019 levels in June, this year. Providing there are no reversals, the company that is highly dependent on the sector will enjoy a big bounce for the next nine months compared to the lower business generated from last year to May this year.
The PE is 13 times earnings based on the latest stock price of $5.25 on the Junior Market of the Jamaica Stock Exchange.
The company is increasing its coverage in the airport, according to the Directors, construction work on the revamped post security food and beverage lounge is ongoing. “There was a soft transitioning into the new food court with some concepts opening March 2022” stated the report accompanying the quarterly. Work on the second phase is slated for completion by the end of December, the directors indicated, “with the full rollout of the rest of Concepts – Bob Marley One Love, Freshens and Bento Sushi.”

NCB the stock to watch

NCB tis the stock to watch with big jump in profit from continuingh operations.

Investors in aggressive buying of NCB Financial shares in late 2018, pushed the group’s shares up to a record high of $161 on last day of November last, following full year’s results that were released earlier in the month.
If investors reacted so strongly to results that were telegraphed previously by the nine months results, it will be interesting to see how they react to the 29 percent hike in dividend and a 40 percent rise in profit before one-time income and taxation.
With profits from ongoing operations seeming set to rise to the $14 region this year, NCB Financial is clearly the stock to watch today.
The results could spark the start of the 2019 rally in the main market and push the price well beyond resistance around the $160 market and unto the next resistance around $200.
In pre market activity, the indication is that the stock will move higher than the $145 it last traded at on Thursday. With just over ten minutes to the start of trading, there are 20,300 units on the bid at $147 and ten at $145 to $145.01.

Producers’ improving performance

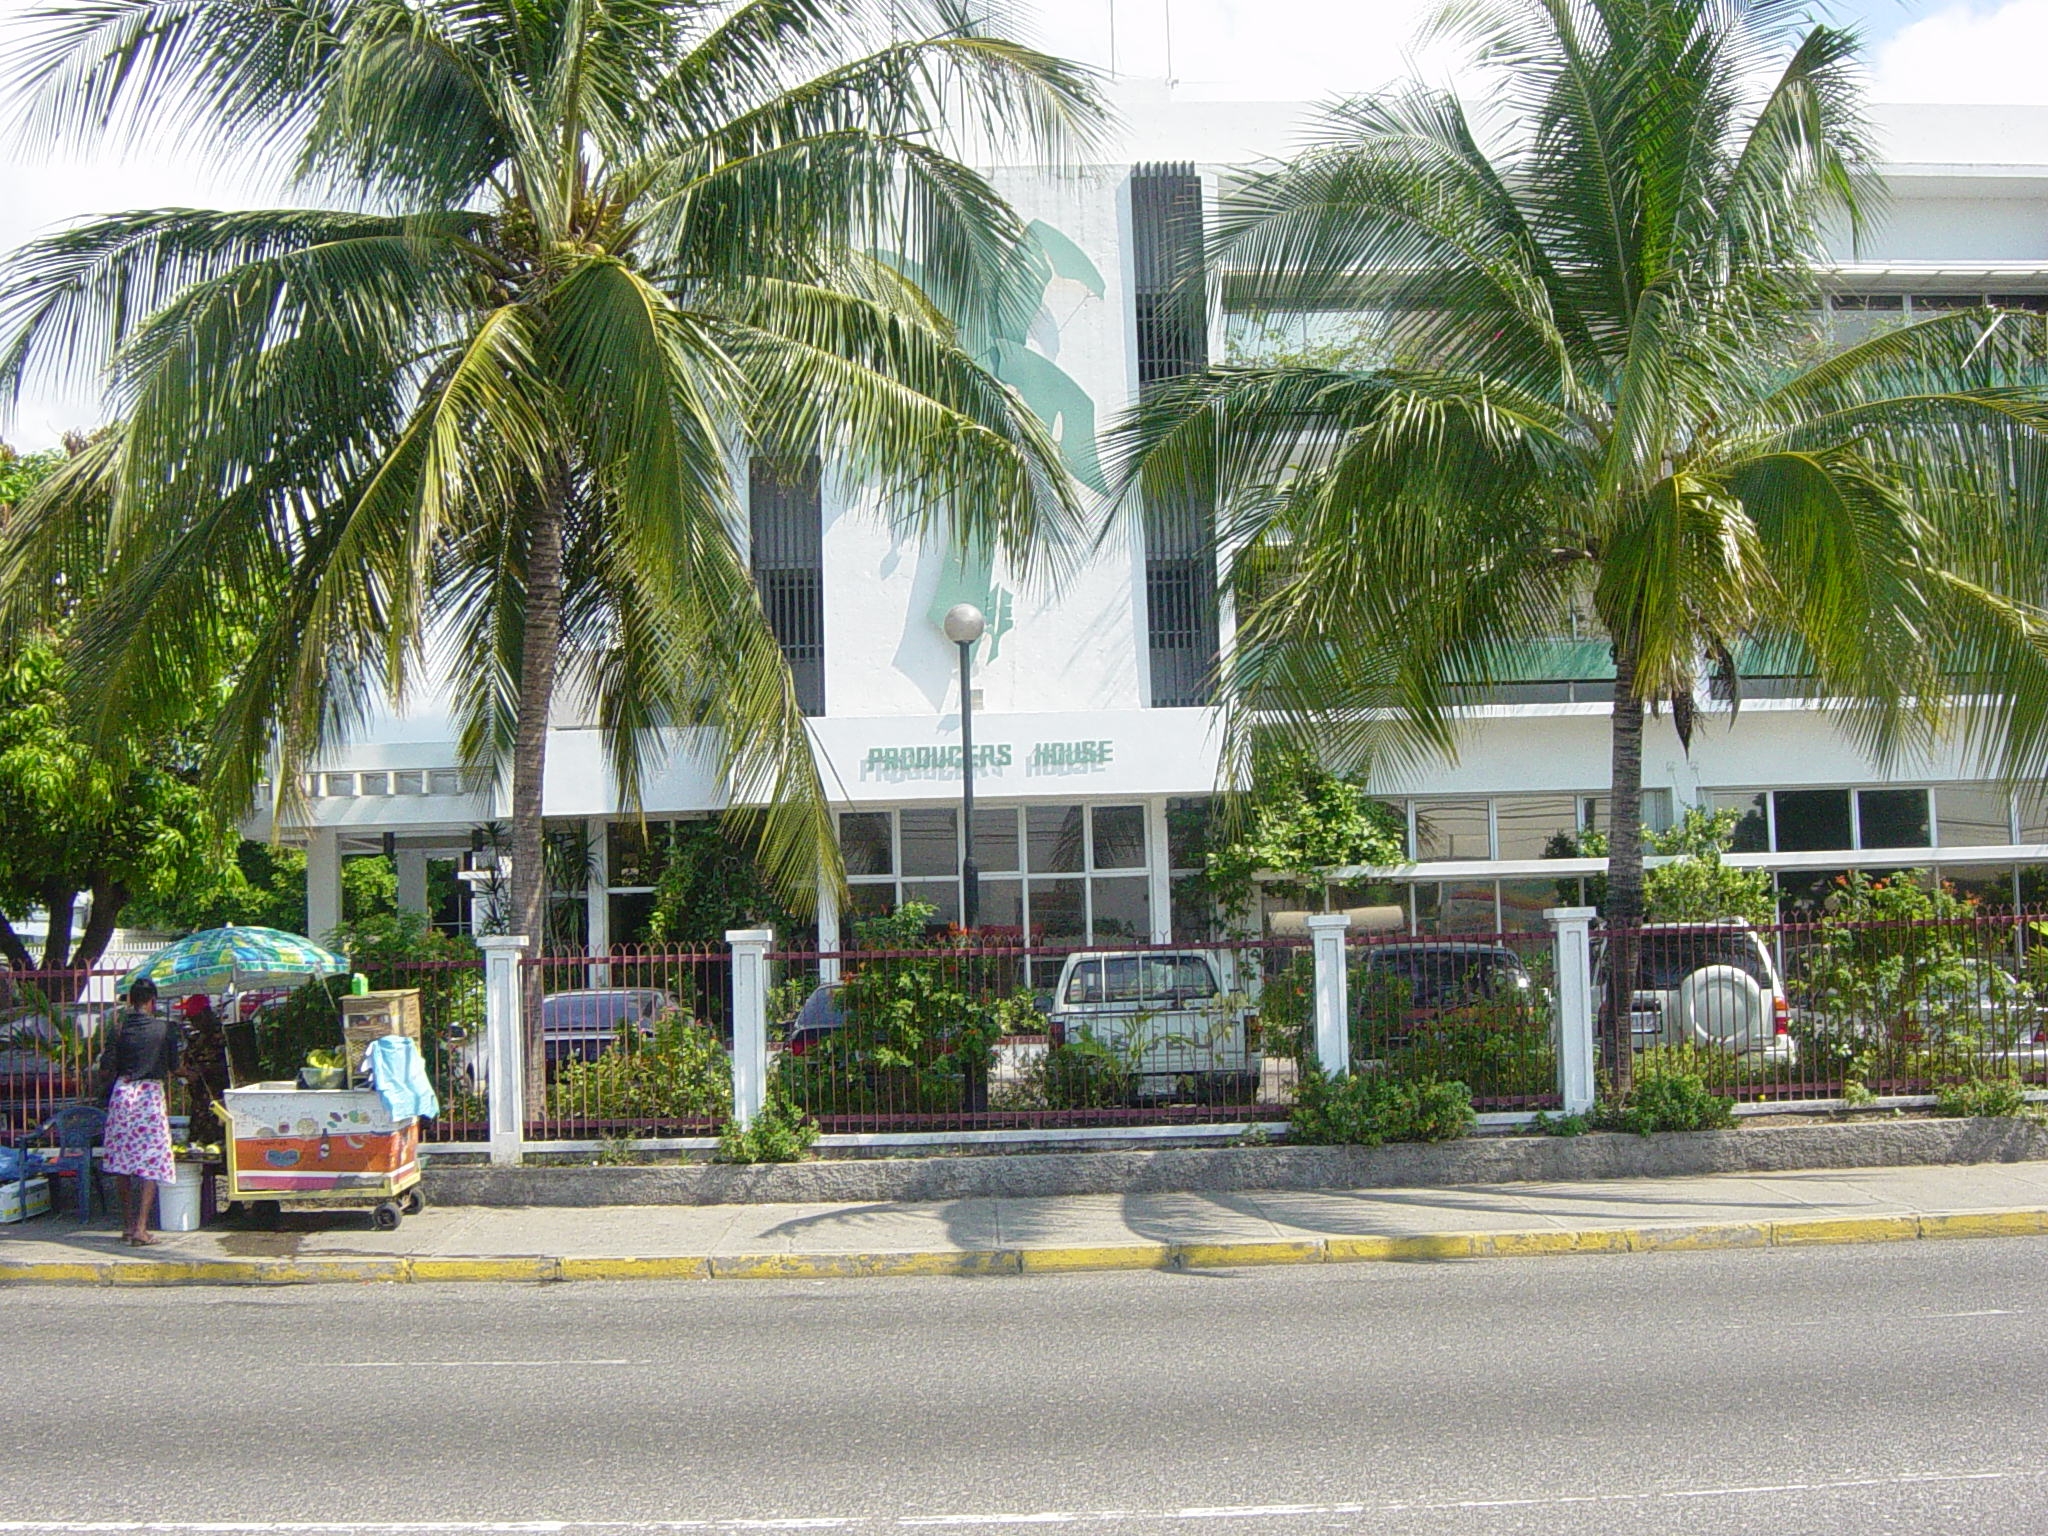
Jamaica Producers HQ in Kingston Jamaica

Jamaica Producers HQ in Kingston Jamaica

Revenues climbed an impressive 30 percent, for Jamaica Producers Group for the June quarter this year over 2013, to $2.39 billion. Net profit attributable to shareholders was $104 million, a 42 percent increase relative to the same period last year.
For the half year to June, net profit attributable to shareholders was $138 million, a 13 percent decline, compared with the similar period in 2013. This year’s performance only had $17 million of gain on sales of fixed assets and investments compared with $105 million in 2013. The 2013 result was negatively affected by $36 million in restructuring cost, there was no such charge this year, resulting in the quality of earnings from ongoing operations being better than in 2013.
Europe| In the 2014 second quarter, the Europe division earned revenues of $1.78 billion and pre-tax profits of $167 million, a 33 percent increase in revenues and 196 percent increase in pre-tax profits relative to the 2013 second quarter. Europe is still facing tough economic conditions, resulting in further monetary easing recently, leading to the Euro slipping sharply in value. This development could negatively affect Producers profit for the rest of the year. The results for 2015 could benefit from the monetary easing as the economy could benefit from the stimuli. The local currency could stay stable for some time thus robbing it of the gains make due to currency slippage in the first half of the year.
JP Tropical Division includes businesses located in the Caribbean that faced particularly challenging production and trading environment that adversely affected margins. The division experienced a loss during the 2014 second quarter of $43 million compared to a profit of $27 million for the same period in the prior year, although revenue grew 25 percent. The loss to JP shareholders is $20 million.
jamaica_producers+Tropicallogo150x150JP Tropical Foods experienced growth in its snack foods product lines, particularly in the USA and UK markets. During the quarter, we launched a new tropical snack brand of plantain and cassava chips for the Dominican Republic market.
Gross profit climbed slower than operating revenues at 24.7 percent in the June quarter to $549 billion but was in line with revenues in the year to date period with gross profit rising 17.8 percent to $977 million.
Subsequent to the quarter the group acquired 11.59 percent more Kingston Wharves shares raising its stake to approximately 42 percent to become an even more dominant shareholder of the company. The rate of return on this latest investment is likely to be around 8 percent, or just slightly better than government of Jamaica current Treasury bill rate. But Producers’ focus would be on the longer term growth prospects that will accrue from the expansion of the port, and the increased business that they expect, especially with the opening of an expanded Panama Canal.
The main activities of the group are juice and food manufacturing, the cultivation, marketing and distribution of fresh produce locally, logistics, land management and the holding of investments.
Finances|At the end of June, the group had debt close to $1.2 billion, that should rise with the acquisition of the Kingston Wharves share purchase, as it was partially funded by borrowed money. Equity stood at $5.9 billion and they had cash funds and investments of $987 million. Current assets to current liability was below norm, at $2 billion to $1.5 billion.
Encouraging results| The results for 2014 so far is encouraging, importantly, Jamaica Producers is adding new products to the existing lines, both in the Caribbean and Europe, this is one of the surest ways of improving profitability as it is less costly to add new lines as much of the overheads cost are already built into the system. This is clearly a stock to be watched.