Profit after tax for the first quarter ending September this year jumped 20 percent at Wisynco Group to $1.55 billion in the current year from $1.3 billion in 2022. Profit before tax also grew by 20 percent from $1.73 billion in 2022 to $2.1 billion, but profit is projected to jump 39 percent for the current year to $6.8 billion, ICInsider.com projections show.
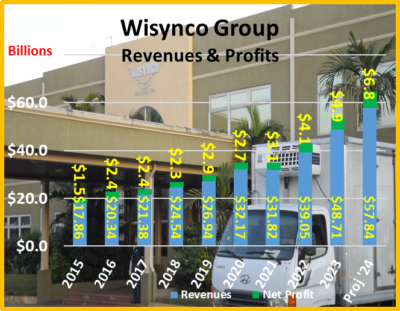 The profit performance resulted from a 15 percent rise in revenues from $11.95 billion in 2022 to $13.73 billion in the current year. Although revenues climbed 15 percent, gross profit increased by just 11 percent, from $4.3 billion in 2022 to $4.8 billion in the current year, as input cost climbed 17 percent to $8.93 billion from $7.6 billion in 2022.
Selling and distribution expenses rose 14.3 percent from $2.12 billion to $2.43 billion and administrative expenses popped nearly 13 percent from $455 million to $513 million. Finance income brought in $168 million versus $85 million in the previous year, but finance cost fell from $150 million to just $11 million, despite borrowings standing at $8.9 billion at the end of the period.
Earnings per share for the quarter rose to 41 cents from 35 cents last year and is projected to reach $1.84 for the full year and $2.40 in 2025. The stock, up 15 percent for the year to date, trades at a PE of 11.3 at the last traded price of $20.70 on the Main Market at the Jamaica Stock Exchange. The PE is slightly below the market average of 12.2.
A dividend of 23 cents per share, totalling $863 million, was paid in July, up from 22 cents per share, totalling $751 million in July 2022. In addition to the above dividends, 22 cents per share was paid in March 2023 and 20 cents in March 2022. The stock trades at 3.4 times a net book value of $6.05 at the end of September.
Cash flow generated for the 2023 quarter amounted to $2.2 billion and $1.9 billion in 2022. After working capital movements, operations delivered net flows of $2.4 billion, up from just $800 million in 2022
Wata is one of Wisynco’s known brands.
Shareholders’ Equity climbed to $22.7 billion at the end of September, up from $19 billion in September last year. Long term borrowings jumped to $2.8 billion from $790 million at the end of September last year and short term loans ended at $1.3 billion and $920 million in 2022. Some of the amounts borrowed are used explicitly to fund a significant expansion of its facilities currently on the way, so far consuming $1.8 billion in the quarter.
Net Current Assets closed the period at $13.5 billion, up from $11 billion at the end of September 2022 and emanate from Current Assets of $12 billion and $8.9 billion at the end of September last year and includes cash and investments of $10.2 billion and $7.7 billion in 2022. These amounts do not take into consideration $2.2 billion in longer term securities at the end of the quarter.
Current Liabilities ended at $7.4 billion at the end of September this year compared to $6.1 billion last year.
The group acquired the distribution rights for the Jamaican Teas products for sale locally. It will add around 2-3 percent to revenues in an entire year in addition to the expansion of the factory and warehousing currently underway and expected to come on stream by March 2024. The expansion will allow for increased production to meet demand they are unable to fill currently and provide capacity to expand exports.
 Price movements in the market resulted in one new TOP10 listing for the Junior Market and one for the Main Market. Everything Fresh rose 9 percent to $1.75, followed by Caribbean Assurance Brokers, gaining 7 percent to end at $3.10, while the losers include Elite Diagnostic and One on One, down 5 percent to $1.79 and $1.01 respectively, followed by a 4 percent decline in Dolphin Cove to $15.50.
 Returning to the Main Market TOP 10 is Caribbean Cement replacing Guardian Holdings, with the nine months’ results indicating lower earnings this year based on the new accounting policy.
 ICTOP10 focuses on likely yearly winners, accordingly, the list includes some of the best companies in the market, but this is not always so. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
 Earnings per share for the quarter was $2.28, up from $1.42 in 2022 and $5.15 versus $5 for the year to September.
 In relation to the cash flows, “Net cash provided by operating activities” was $5.7 billion for the nine months and $2.46 billion for the quarter. The cash flow generation during the quarter and the available cash at the beginning of the period have allowed the Group to invest $4 billion during the nine months of the year and $2 billion during the second quarter, leaving the company with $639 million in cash and bank balance at the end of the period.
 The above set the stage for ICTOP10 Junior Market stocks to post five rising stocks to two that declined, while the ICTOP10 Main Market recorded five modest gains and four losses.
 CInsider.com upgraded earnings to $0.40 per share for the current year and that pushed the stock to 5th place on the TOP 10 list. Paramount Trading returns with a depressed price and gains by the two stocks dropping out of the listing.
 The PE of the Junior Market TOP10 sits at 5.9, just over half of the market, with an average of 10.8. There are 11 stocks, or 23 percent of the market, with PEs from 15 to 25, averaging 18.6, well above the market’s average. The top half of the market has an average PE of 15, possibly the lowest fair value for Junior Market stocks currently, with the market projected to rise by 244 percent by May 2024.
 The company did not benefit as much from interest income as would be expected and had adequate funds on hand to expand the loan portfolio, development management indicated they would be pursuing for the rest of the year. Significant expansion of loans could radically transform both revenues and profit for the year. The extent of this improvement is unclear currently, however, the potential suggests that this is a stock to watch going forward as it could surprise to the upside. Lasco Manufacturing is, without question, a stock that is seriously undervalued, but investors pushed the price down during the week. This is clearly one for the future and one that investors should see continuous improvement in stock price over the next 12 months as the company rolls out improved profits in the quarters to come.
 The expectation is for profitability to improve during the current fiscal year ending in June 2024. The stock is clearly undervalued and has much room for growth over the next 12 months and beyond.
 The divergence between the average PE of the Main and Junior Markets and the overall market valuation are important indicators of the level of likely gains for ICTOP10 stocks.
 The average PE for the JSE Main Market TOP 10 stands at 5.1, well below the market average of 12.2. The Main Market TOP10 is projected to gain an average of 328 percent, by May 2024, based on 2023 forecasted earnings.
 ICTOP10 focuses on likely yearly winners, accordingly, the list includes some of the best companies in the market but not always. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
 At the end of the week, the average PE for the JSE Main Market TOP 10 stands at 4.9, well below the market average of 12.2. The Main Market TOP10 is projected to gain an average of 344 percent, by May 2024, based on 2023 forecasted earnings.
 ICTOP10 focuses on likely yearly winners. The lists include some of the best companies in the market but not always. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
 At the end of the week, the average PE for the JSE Main Market TOP 10 is 4.9, well below the market average of 12.4. The Main Market TOP10 is projected to gain an average of 330 percent, by May 2024, based on 2023 forecasted earnings.
 ICTOP10 focuses on likely yearly winners, accordingly, the list includes some of the best companies in the market but not always. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.
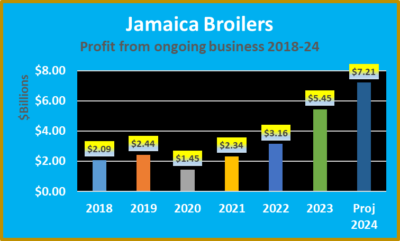 Administrative costs declined marginally from $2.98 billion to $2.92 billion in the current period, distribution costs rose four percent from $690 million to $720 million, finance costs almost doubled, moving from $320 million to $633 million, taxation moved up from $332 million to $393 million during the 2023 quarter.
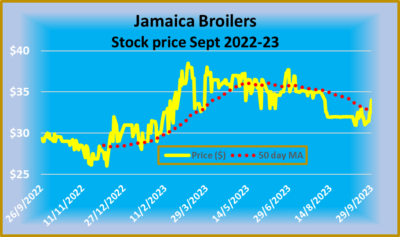 Cash inflows before working capital requirements for $3.4 billion and is up from $2.6 billion in the previous year after working capital funding rose, the group ended up with a negative cash flow of $2 billion that is up from $1 billion in the previous year.