Honey Bun doubles Q2 profit.
For the second quarter to March, revenues increased 15.5 percent over the correspondent quarter last year to $406 million from $352 million in 2018, with the growth bettering the 14.2 percent or $36 million revenues in the first quarter to December.
“Revenues from export sales have increased by 16 percent over the prior period, sales growth is attributable to our meeting customer demand having invested in increasing our production capacity over the period,” the director informed shareholders in their report accompanying the quarterly results. For the six months period, revenues increased by 15 percent over the correspondent of last year to $775 million, up from $675 million in 2018 while profits before tax increased by 57 percent to $112 million and after tax profit grew 75 percent to $109 million. The financial performance was driven by improvements in productivity, process efficiencies and other cost savings initiatives. Administrative, Marketing and finance cost rose 13 percent in the second quart and 17 percent for the half year compared to the similar periods in 2018.
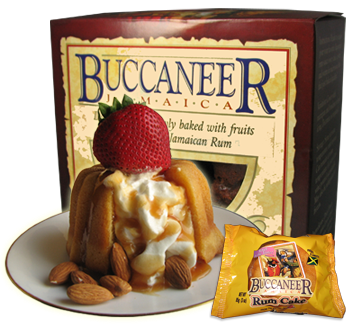
One Honey Bun’s Products.
Total current assets less current liabilities amounted to $178 million, up from $115 million in 2018. The company’s cash as stood at $166 million with investments at $85 million while borrowed funds amount to just $26 million. Shareholders’ equity ended the period at $713 million.
The stock traded last on the Junior Market of the Jamaica Stock Exchange at $5.01 at a PE ratio of 11 times 2019 earnings, well below that of the majority of companies.
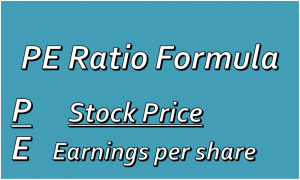 The bulk of investors who would be buying the vast quantity are more professional than not and are versed on the valuation levels of stocks. Accordingly, they are unlikely to be buying a stock that has doubtful expansion credentials at an inflated value. The most popular valuation tool, the PE ratio does not support a price much higher than $1.20, with EPS of 6 cents per share. A price of $1.20 equates to a relatively high PE ratio of 20. Only a few stocks are valued close to this multiple and many of them have prospects for profits to grow. Wigton has no immediate prospects for growth in earnings, pricing it at 20 times EPS would, therefore, be unwise. The market will speak but the heavy selling on Friday is more in line with the thinking that the top is not far off. Investors who buy shares above the accepted market norm will likely get crushed unless they have a long term investment horizon on their minds. PE ratios are there to give a sense of appropriate values. When investors try to break away from where the bulk of investments funds place the value of a stock at, they usually end up regretting the move.
Wigton price collapses
Wigton Windfarms’ shares traded below the IPO price of 50 cents on Friday as attempts to shield the price from falling after announcing a drop in revenues is finally giving way to selling pressure. The Wigton syndrome continues to plaque the Jamaica Stock market with irrational behavior of investors to be seen in the prices of many stocks.
Wigton traded nearly 90% of shares on Thursday.
On August 25, investors bought 5 million shares of Future Energy, up to $2.85 and for the next two trading day’s they just over 10 million units up to $3.29, with 15 million shares trading on the 30th at an average of $2.96. The stock is now trading at $2.04, with a PE ratio of 16, to be one of the more highly priced Junior Market stocks. What is happening here, when viewed against stocks with much lower PEs and good growth prospects?
 There are thousands of new investors in the market brought on by several new listings on the market, with most listings creating good returns in a relatively short time for early investors.
Radio Jamaica another stock that traded as high as $4.65 on August 25, traded on Friday at $3.11 at a PE ratio of 7. Salada Foods continues to trade around the $7 region at a PE ratio of 43 times current year’s earnings. Wigton Windfarms that investors were not informed until late last year that the contract for their number 2 turbine provide for a reduction in rates for the supplying of electricity to JPS, belatedly traded down to 46 cents on Friday with few bids left in the system, and now trades at a PE of 12.5.
The stock market is a wonderful creation that has helped to enrich participants over the years, like any endeavor the more time spent studying and understanding it the better off those investors will be.
In the past, investors and scholars developed systems and methods to act as a guide to better investment decisions and thus reduce the love or dislike for a stock or other types of investments and thus reduce emotional decisions.
Technical analysis is a very useful tool used in the investment arena that carries coded messages for persons who understand them. They help investors to avoid excessive behavior in markets and telegraph future trends by using past market movements as the base.
The recent price movements for Radio Jamaica and Fesco show them breaking out of a channel that goes back for months, both companies released results that were price movers and both broke out, with the market not fully there as yet as prices moved too far too fast as such prices pulled back.
A few months after Wigton shares were listed in 2019, ICINsider.com wrote a piece to help investors better understand stock market behavior and prevent losses in the market. The piece captioned “Wigton price dreamers” was published in May of 2019. In light of the irrational trading in Fesco and Salada shares, elements of the article are highlighted below.
Salada Foods traded at a all-time high of $18 on Tuesday.
“Buy now, Ride the $3 wave”. That is the advice of one online investor to another, regarding the likely performance of the Wigton Windfarm stock after trading, on the first day of listing at 83 cents with a PE of 14, placing the value in the upper half of the most valued main market stocks. The premium over net asset value another measure of valuation is 291 percent above the net asset value. At $3, the stock would trade at a stunningly high PE ratio of 50 times 2019 and 2020 earnings. The only main market stock close to that valuation is Kingston Wharves (KW) at 35 times 2019 earnings and that is coming down from more than 50 times 2018 earnings when it traded at $85.
Unlike KW, which has less than 10 percent of the shareholding that will trade, amounting to a few million units, Wigton has billion of shares that will trade. The high liquidity of the shares almost ensures that they will not become overvalued.
Most investors who would be big buyers are more professional and are versed in the valuation levels of stocks. Accordingly, they are unlikely to be buying a stock that has doubtful expansion credentials at an inflated value. The most popular valuation tool, the PE ratio does not support a price much higher than $1.20, with EPS of 60 cents per share. A price of $1.20 equates to a high PE ratio of 20. Only a few stocks are valued close to this multiple and many of them have prospects for profits to grow. Wigton has no immediate prospects for growth in earnings, pricing it at 20 times EPS would therefore be unwise. The market will speak but the heavy selling on Friday when it first traded is more in line with the thinking that the top is not far off. Investors who buy shares above the accepted market norm will likely get crushed.
In the investment world staying close to the crowd with pricing is a prudent investment practice that tends to be less costly than trying to predict lofty heights for stocks to reach.
PE ratios are there to give a sense of appropriate values, when investors try to break away from where the bulk of investors place a value of a stock, they usually end up regret the move.