 Profit at Gleaner Company, for the three months to September is up strongly, but that’s coming from a low level for 2013. Most of the improved figures came from a big upswing in finance income and not from the main activity of media.
Profit after tax rose 271 percent, to $16 million, up from just $4 million in 2013, and for the six months, growth was up 301 percent to reach $58.6 million from $14.6 million, but that is just 5 cents per share. Profit margins improved in 2014 over 2013 rising only 4 percent for the nine months and 11 percent in the quarter, but administration and other cost rose 11 percent in the quarter and a lesser 5 percent in the year to date period.
The other good news is the vast improvement in the results of the subsidiaries, for the year so far, having produced a profit of $10.5 million in the September quarter from a loss of $19 million last year and a reduced loss of $2 million for the year to September compared with a loss of $31 million in 2013.
 Sales revenue remains flat, at just over $813 million for the 2014 and 2013 quarters and up a mere 2 percent for the nine months to September, at $2.43 billion. The economic conditions the country is in, coupled with stringent fiscal policies being pursued by the government, is not the environment that the media house relishes. The situation has been made worse by Claro mobile exiting the system, a few years ago. The acquisition of Flow by Cable & Wireless could well put more pressure on revenues down the road, depending on how the acquisition is handled. In the end, the acquisition will mean less advertising spend, nationally by the telecom sector if the acquisition goes through. Another negative, is that newspapers are not the in thing anymore, with newer readers preferring the internet, but they are not yet prepared to buy news on line the same way that news was sold in the past. Although, the Gleaner owns a radio station its profitability is at best small and can’t deliver much to the bottom line.
The company’s stock price is low compared to its historical norm, but compared with others in the market, it can be considered overpriced at a PE that is around 10 times current year’s earnings, with no sign of a major turnaround in its operations soon.
Gleaner awaiting economic up turn
Carreras profit up margin squeezed
 Profit at Carreras for the three months to September, is up 26 percent to $614 million, from $485 million in 2013, for the six months growth was less robust, at 20 percent to reach $1.17 billion from $9,71 million.
Revenues recovered considerable grounds, from the lost sales in 2013, from the front loading by merchants of inventories ahead of a pending price increase of cigarettes that the company implemented in March 2013. For the quarter, sales revenues rose 18.5 percent over that of 2013 and 19.3 percent for the six months to September. During last year September quarter, revenues fell 16 percent, so there is still a fall out, but that is usually the case whenever there is sizeable price increase, is effected.
Profit margins got squeezed, rising only 13 percent for the six months and 10 percent in the quarter, no doubt, due to the devaluation of the local dollar and the lack of a price increase so far. Carreras was able to hold cost well below the increased sales revenues for the quarter and year to date. The company is on track to earn somewhere in the region of $6 per share, for the current year and that will help move the price up. The stock remains IC Insider BUY RATED.
 Carreras will pay a special capital cash distribution, on December 18, following an interim dividend of $1.20 per stock unit, to be paid on December 11, 2014. The payments will bring to total distribution for 2014 to $8.09.
The stock closed trading on the Jamaica Stock Exchange, at $37 on Friday, putting the PE ratio, at 6 times the current fiscal year earnings.
Dolphin Cove Profit up 14%
Dolphin Cove’s profit for the September quarter, rose 14 percent to $109 million and for the nine months to September, its up a strong 25 percent to $397 million. Cost generally rose slightly faster than revenues, but that did not impair the results by much.
 Direct cost 16 percent for the quarter and 18 percent year to date, administrative and other costs were up 18 percent for quarter, but was in line with revenues, at 15 percent for the nine months, to September. Margins were held for the quarter and rose for the nine months period. Revenues climbed 16 percent for the quarter, and 15 percent year to date. At the end of the financial year to December, earnings should be just over $1.20, for this major tourist attraction.
Attendant with the growth in profit, the company increase the amount paid out in dividend in 2014 over 2013.
Rich year for Carreras’ shareholders
 Carreras declared yet another dividend payable to shareholder in December, with the latest being $1 per stock unit to be paid out of proceeds received from the liquidation of a subsidiary. The payment is pending the granting of a transfer tax exemption pursuant to the Transfer Tax Act.
The interim special capital cash distribution will be paid on December 18, to stockholders on record as at December 1, 2014. The ex-dividend date is November 27. The distribution follows the interim dividend of $1.20 per stock unit due for payment on December 11, 2014, to stockholders on record at November 20. The payment will bring to total for 2014 to $8.09 for a return of 22 percent for the year based on the stock price of $36.75 at the end of 2013. The stock closed at $37 on Friday on the Jamaica Stock Exchange.
In September, Carreras paid an interim dividend of $1.20 per stock unit, the company also paid an interim dividend of $1.75 per stock unit on June 26. On March 13 they paid $1.62 per share.
A special capital cash distribution of $1.34 per stock unit was paid on July 31 and a special capital cash distribution of $1.18 was last paid on January 30, this year.
Profit up|Carreras just announced results for the six months to September, with an 18.5 percent increase in revenues for the quarter, over that of 2013 and 19.3 percent for the six months, to September.
Profit after tax, rose 28 percent in the quarter, to reach $614 million, up from $485 million in 2013, and for the six months, growth was less robust, at 12 percent, to reach $1.22 billion from $970 million.
Profit margins got squeezed, rising only 13 percent for the six months and 9 percent in the quarter, no doubt due to the devaluation of the local dollar and the lack of a price increase so far. Revenues are recovering from the 2013 price increase, and from the front loading by merchant of inventories ahead of the increase. The company is on track to earn somewhere in the region of $6 per share for the current year, that will help move the price up. The stock remains IC Insider BUY RATED.
Witco sales down, profits up
 West Indian Tobacco reported profit before taxation of TT$436.4 million for the nine months ended September, 2014, an increase of 13 percent over the corresponding period in 2013.
Profit after taxation for the period amounted to TT$329.3 million, 16 percent increase. For the quarter, profit of $106 million was achieved, versus $97 million, in 2013, but revenues fell to $282 million from $287 million, in the 2013 quarter. Revenues increased from $843 million to $872 million for the nine months.
Cost of sales improved in the 204 quarter, and raised gross profit to $714 million versus $171 million and for the nine month, to $542 million from $496 million. Cost was mostly down with distribution cost falling from $14 million to $11.4 million and administrative expenses reaching $70.45 million in 2014 compared with $74.93 million in 2013. Other Operating Expenses rose to $23.55 million from $21.15 million.
The company seems on target to hit $6 per share for the year to December. For the coming year the recent price adjustment, is set to help push dollar sales and move profits up for 2015.
The Board approved the payment of a third interim dividend of $1.39 per ordinary share payable on 13 November. For the year to date Witco would have paid $3.57 inclusive of the November payment, compared with $2.93 last year.
The company is a subsidiary of BATCO and is listed on the Trinidad Stock Exchange.
Q3 profit up 20% at Hardware & Lumber
 Hardware & Lumber recovered somewhat from the poor results in the second quarter, with sales revenue of $1.72 billion for both quarters, with the latest quarter just slightly higher than the same period last year, with sales of $1.71 billion.
Hardware and Lumber reported a 20 percent increase in profit for the September quarter to $44 million or $0.54 per stock unit, compared to last year’s $37 million or $0.46 per stock unit. The latest result is in contrast to a 34 percent fall in profit for the June quarter, year over year. Profit after tax for the nine months was $113 million, or 26 percent more than the $90 million, for the same period in 2013. Earnings per stock unit for the nine to September months is $1.40, up from $1.11 for the comparative period in 2013.
Gross profit for the nine-month period, fell to $1.22 billion compared to $1.3 billion for the comparative period last year, but for the latest quarter, it ended at $422 million, just slightly lower than the $435 million in 2013. Gross margin fell to 32.5 percent from 34.17 percent, in 2013, for the quarter and for the 9 months period 30.4 percent and 35.1 percent in 2013. Total revenues for the nine months is $5.25 billion, an increase of 5 percent ahead of $5 billion achieved in the same period last year.
Operating cost for the quarter was down to $370 million from $380 million in 2013 and for the nine months, cost fell to $1.123 million from $1.17million in 2013.
Looking ahead, the company increased inventories to $1.6 billion, from $1.1 billion in 2013 and reduced cash to $257 million from $388 million while borrowings fell from $494 million in September 2013 to $320 million, helping to reduce finance cost from $36 million down to $23 million for the nine months. For the latest quarter finance cost was slashed from $12 million down to $7 million.
The company results recovered from the poor June quarter and puts them on track to post $4.35 per share for the full year, with the December quarter being their biggest, for revenues and profits.
The stock remains Buy Rated with the price at $6.50 with much upside gains ahead.
NCB books $1B loan loss in Q4
 National Commercial Bank pushed provision for loan losses to $988 million in the September quarter, well up from $357 million in the June quarter and $283 million for September 2013, to reach $2.2 billion for the year, compared to $2.07 billion.
Despite the losses in this area NCB reported profit after tax of $2.9 billion, for the September quarter and $11.6 billion for the fiscal year.
Non-performing loans totalled $8.7 billion as at September 2014 versus $7 billion at September, 2013, representing 5.4 percent of the gross loans compared to 4.8 percent as at September 2013. The total provision for the year amounts to a high 8 percent of total interest income, for the segments that lend and would be much higher as a percentage of loan income.
After the provision for credit losses, loans and advances, totaled $157.6 billion at September this year and grew by 12 percent, or $16.5 billion, compared to the loan portfolio, at September 2013.
NCB hikes dividend, profit up 36%
 National Commercial Bank has hiked the final for this year to 96 cents per share to stockholders on Thursday December 11, from only 16 cents last year December.
The dividend will be due to Stockholders on record at November 28. The banking group paid 16 cents per share in December, last year. NCB reported net profit of $11.6 billion, an increase of 36 percent or $3.1 billion to generate earnings per stock unit of $4.73 for the year to September.
The final payment for 2014, brings the total dividends, for the year to $1.98. National Commercial Bank made dividend payment of 35 cents per share in August 25, on May 22, the payment was 35 cents per share and 32 cents per share on February 20 this year.
Republic’s flat year
 Operating expenses rose 20.5 percent for Trinidad’s Republic Bank and loans loss provisions more than doubled to $119 million from $57 million in 2013, to help keep profit virtually flat, for the 2014 financial year ending September.
These expenses, grew at a much faster pace than the 11 percent increase in revenues of $3.75 billion. In the end, profit after tax crawled to $1.2 billion from $1.15 billion in 2013. Republic declared a dividend of $3 per share which will results in a total payment for the year of $4.25. Earnings share for the year is $7.39 the stock traded last at TT$120, putting the PE to 16. increased profit going forward will be needed to make a major he stock price at this PE ratio.
Republic increased loan provisions in Guyana but suffered from weak economic conditions in Grenada and Barbados. The bank closed the year with total assets amounting to $59.4 billion and equity of $8.7 billion.
While on the surface 2015 should show improved results, the sharp drop in the price of oil below 80 per barrel, could create uncertainty for investors, who may want to be cautious in taking on debt in the Trinidad economy and it could create economic problems for the oil dependent nation if it remains low for a prolonged period.
Looking for a more affordable apartment
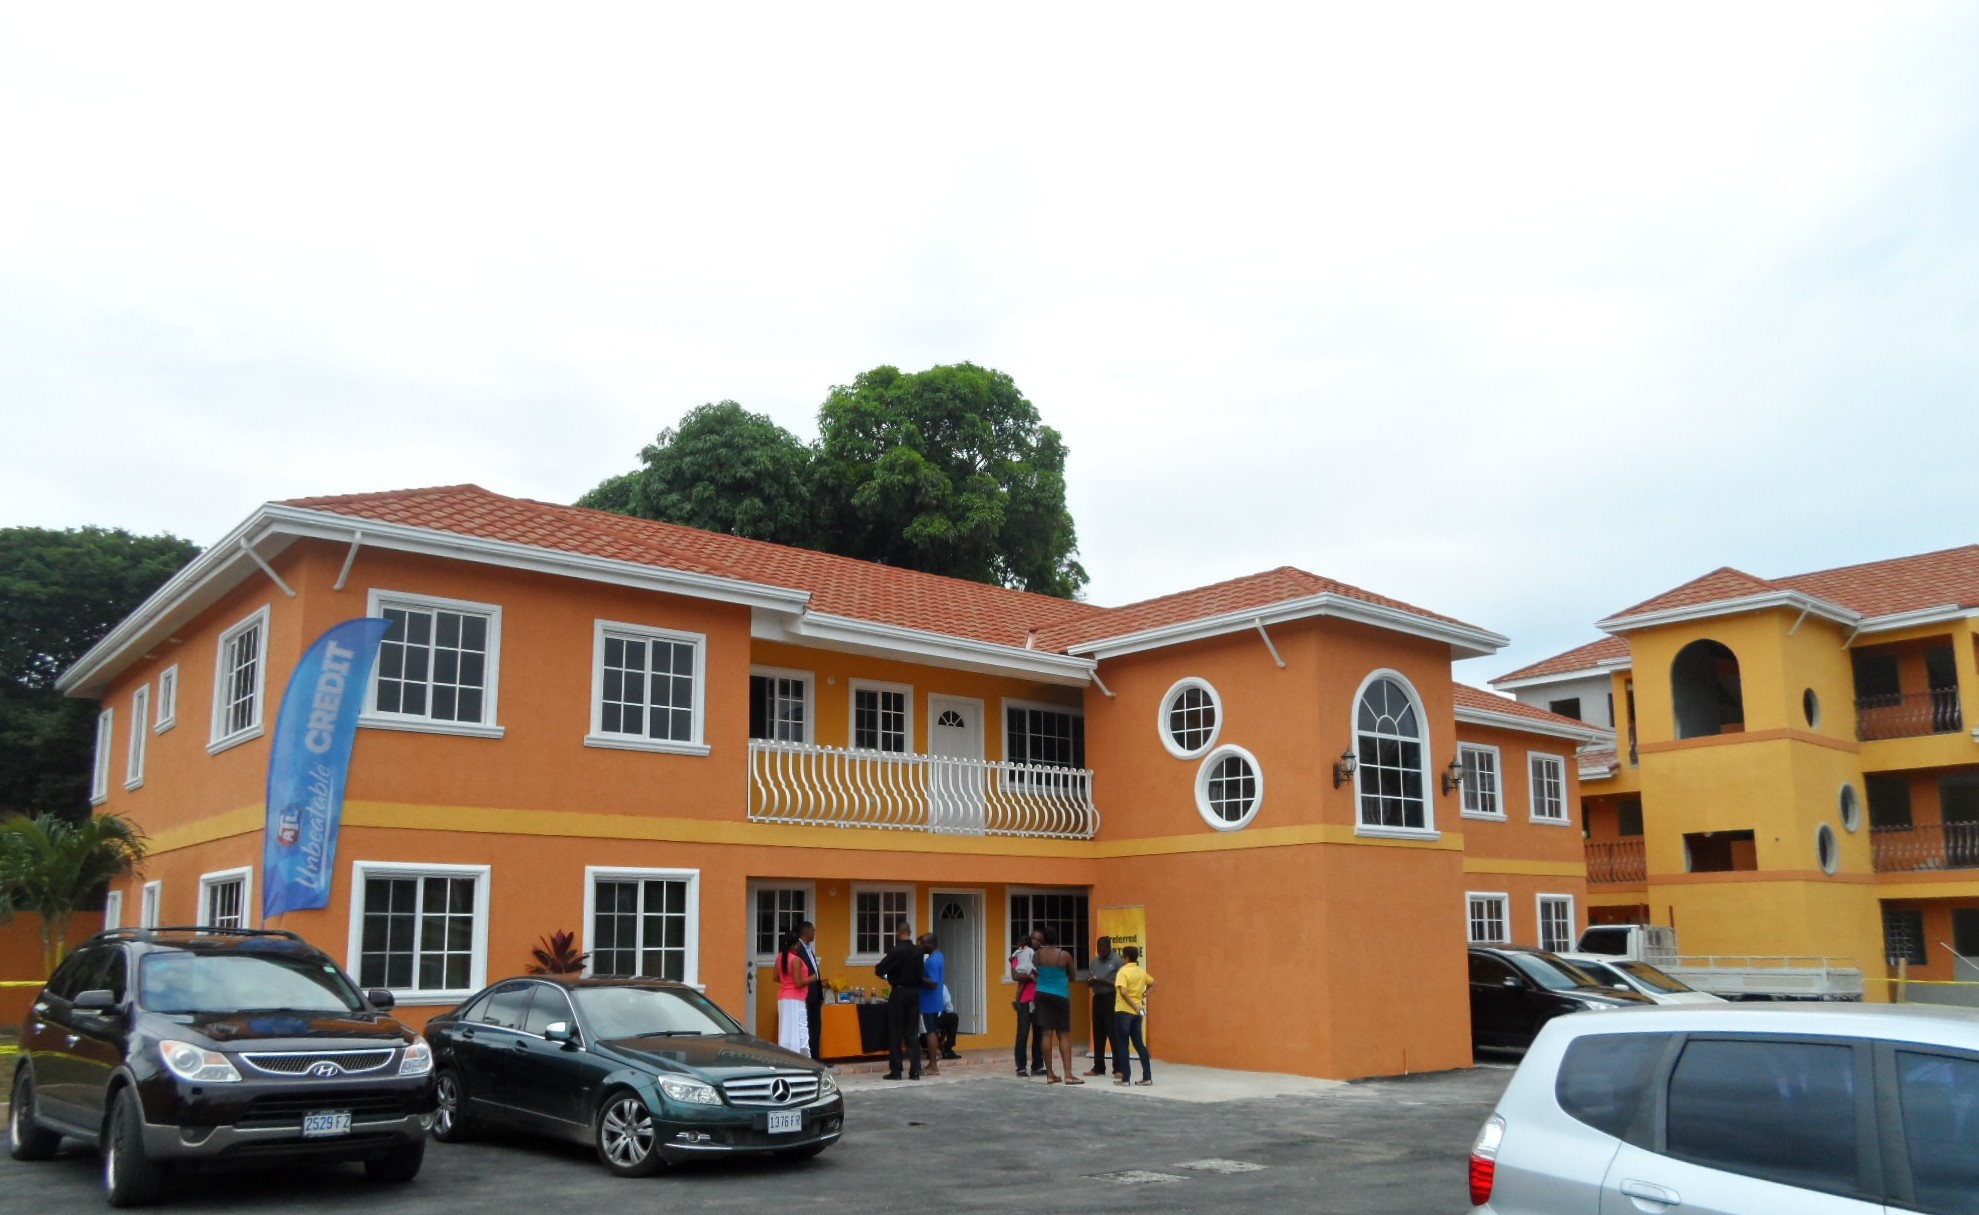 The corporate area in Jamaica has the densest working population. Most workers would prefer to live close to work, property prices preclude many, from living within the urban area of Kingston and St Andrew.
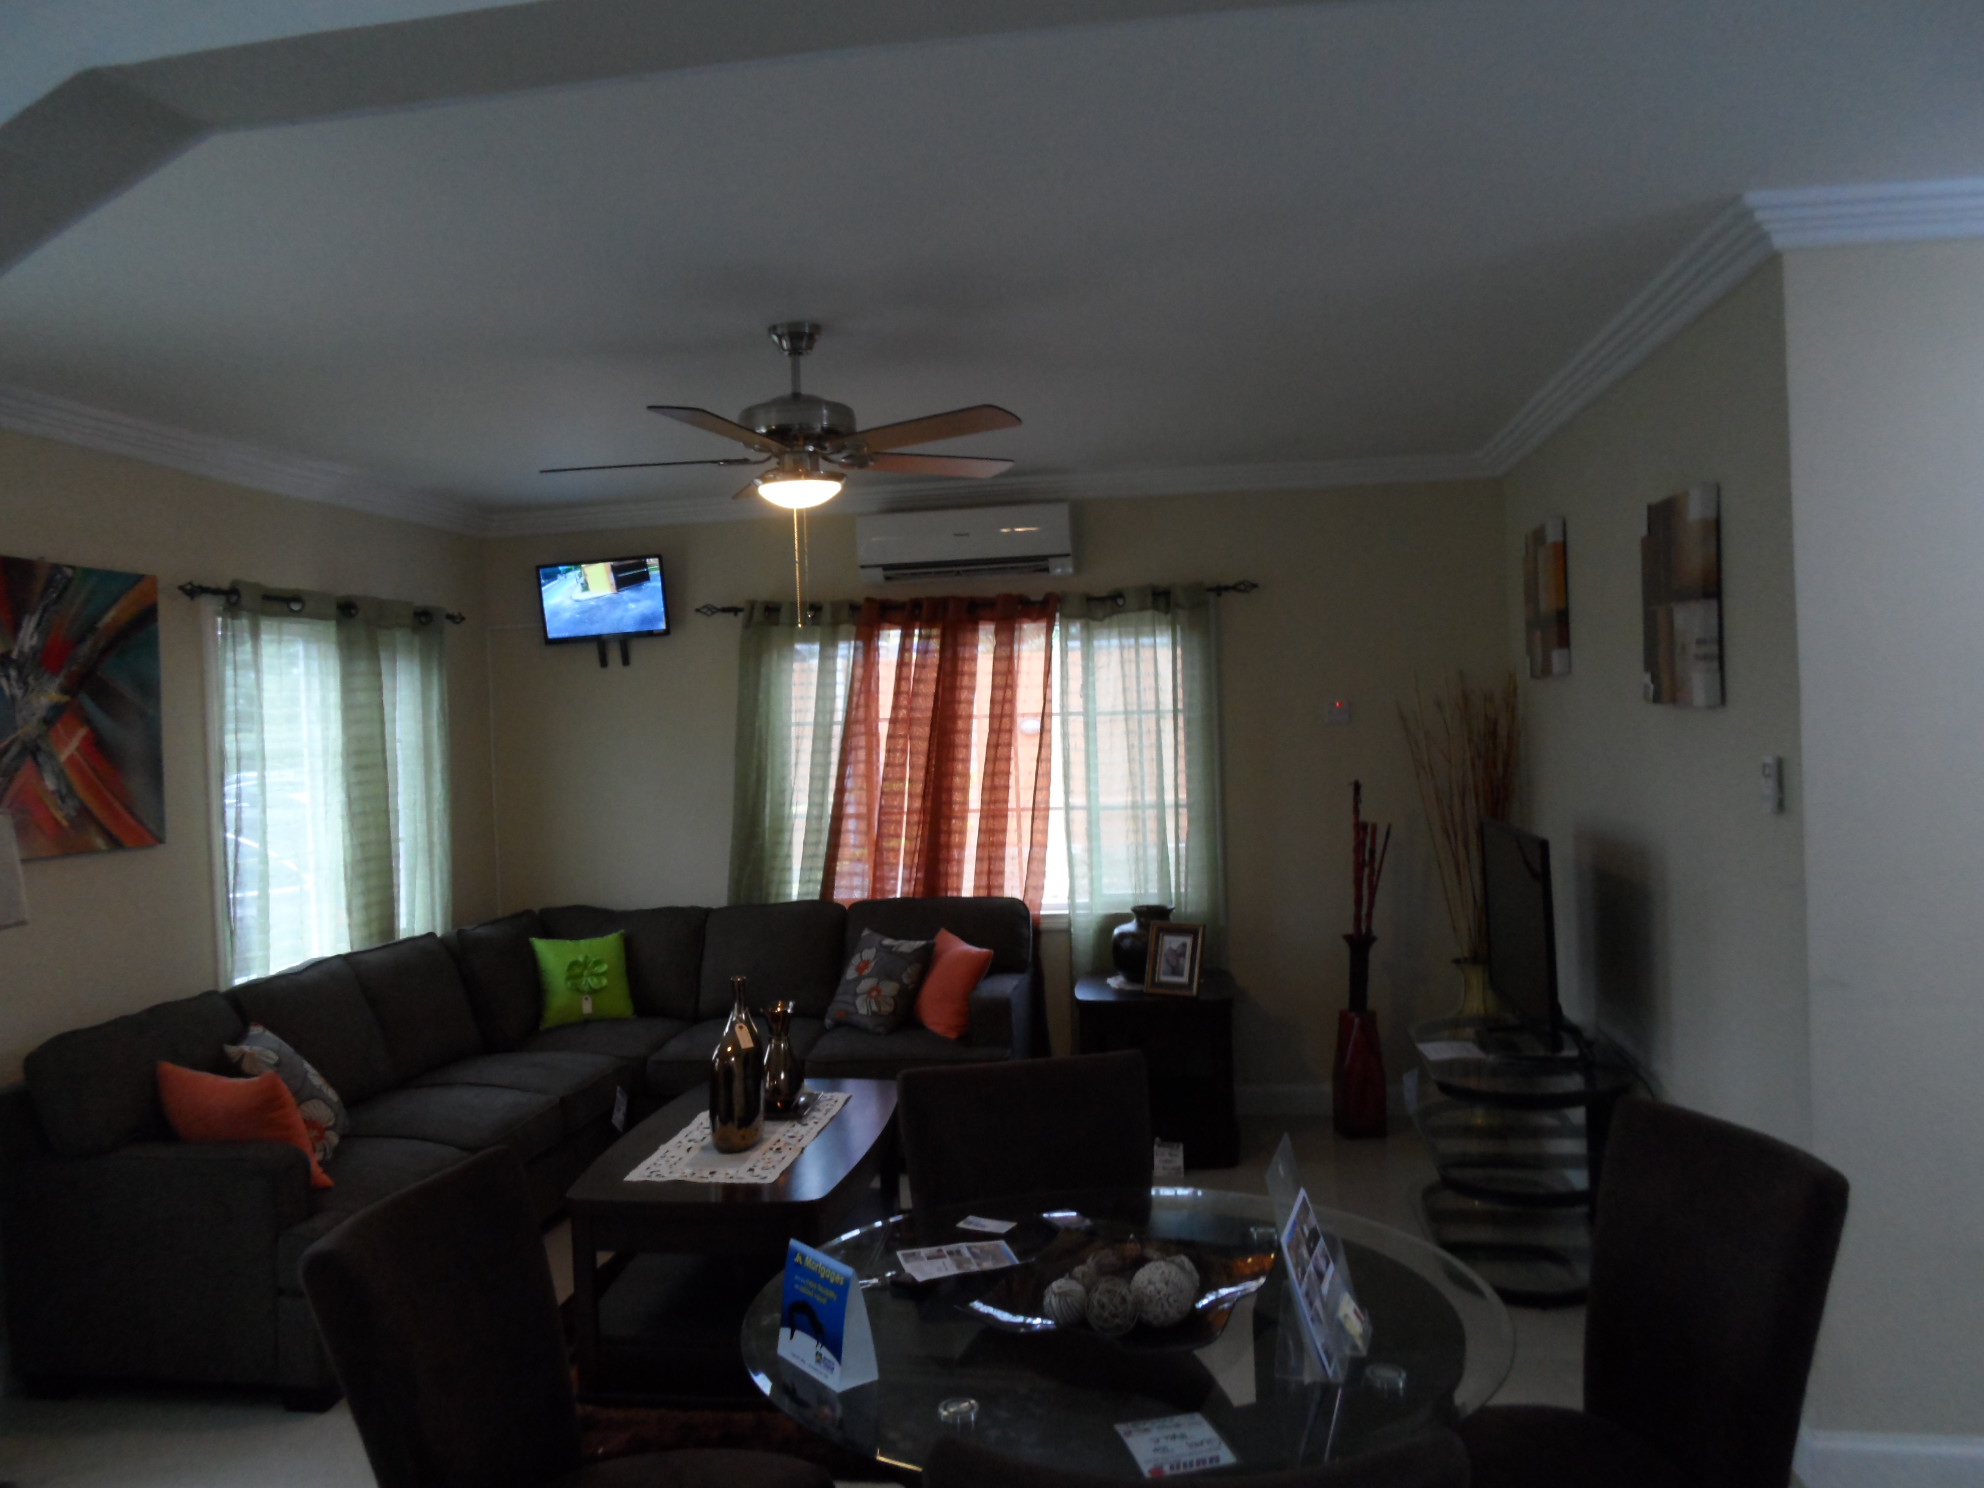
2 bedroom unit living area
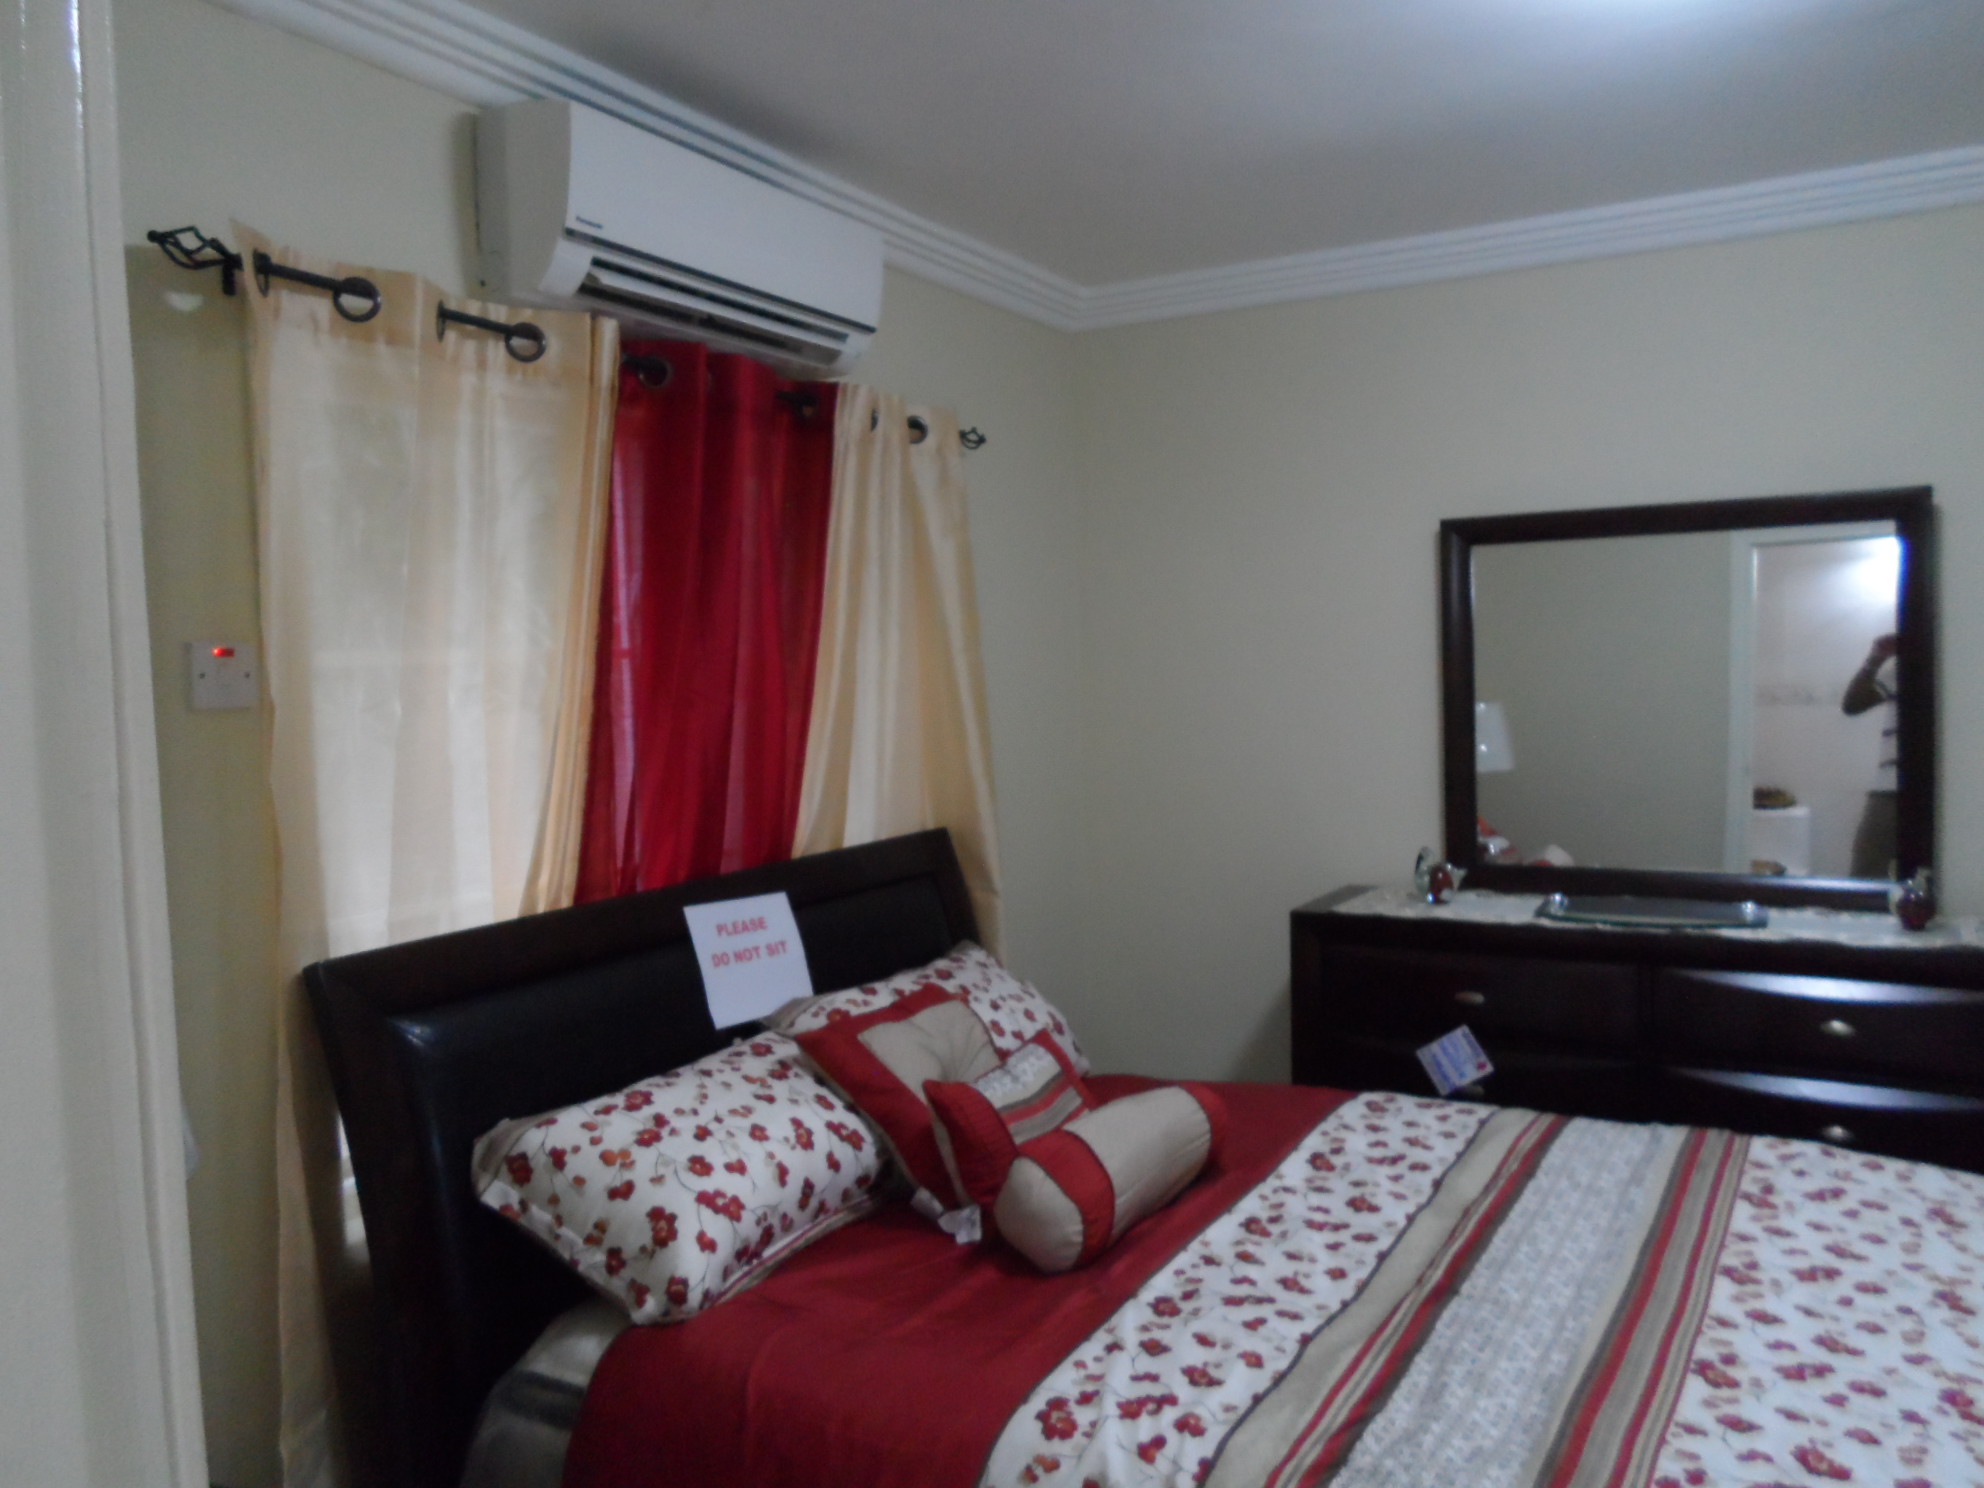
Bedroom of 1 bedroom unit
As more units are built in what is considered the preferred residential areas, there is a trend that has seen units being built some distant from the main areas.
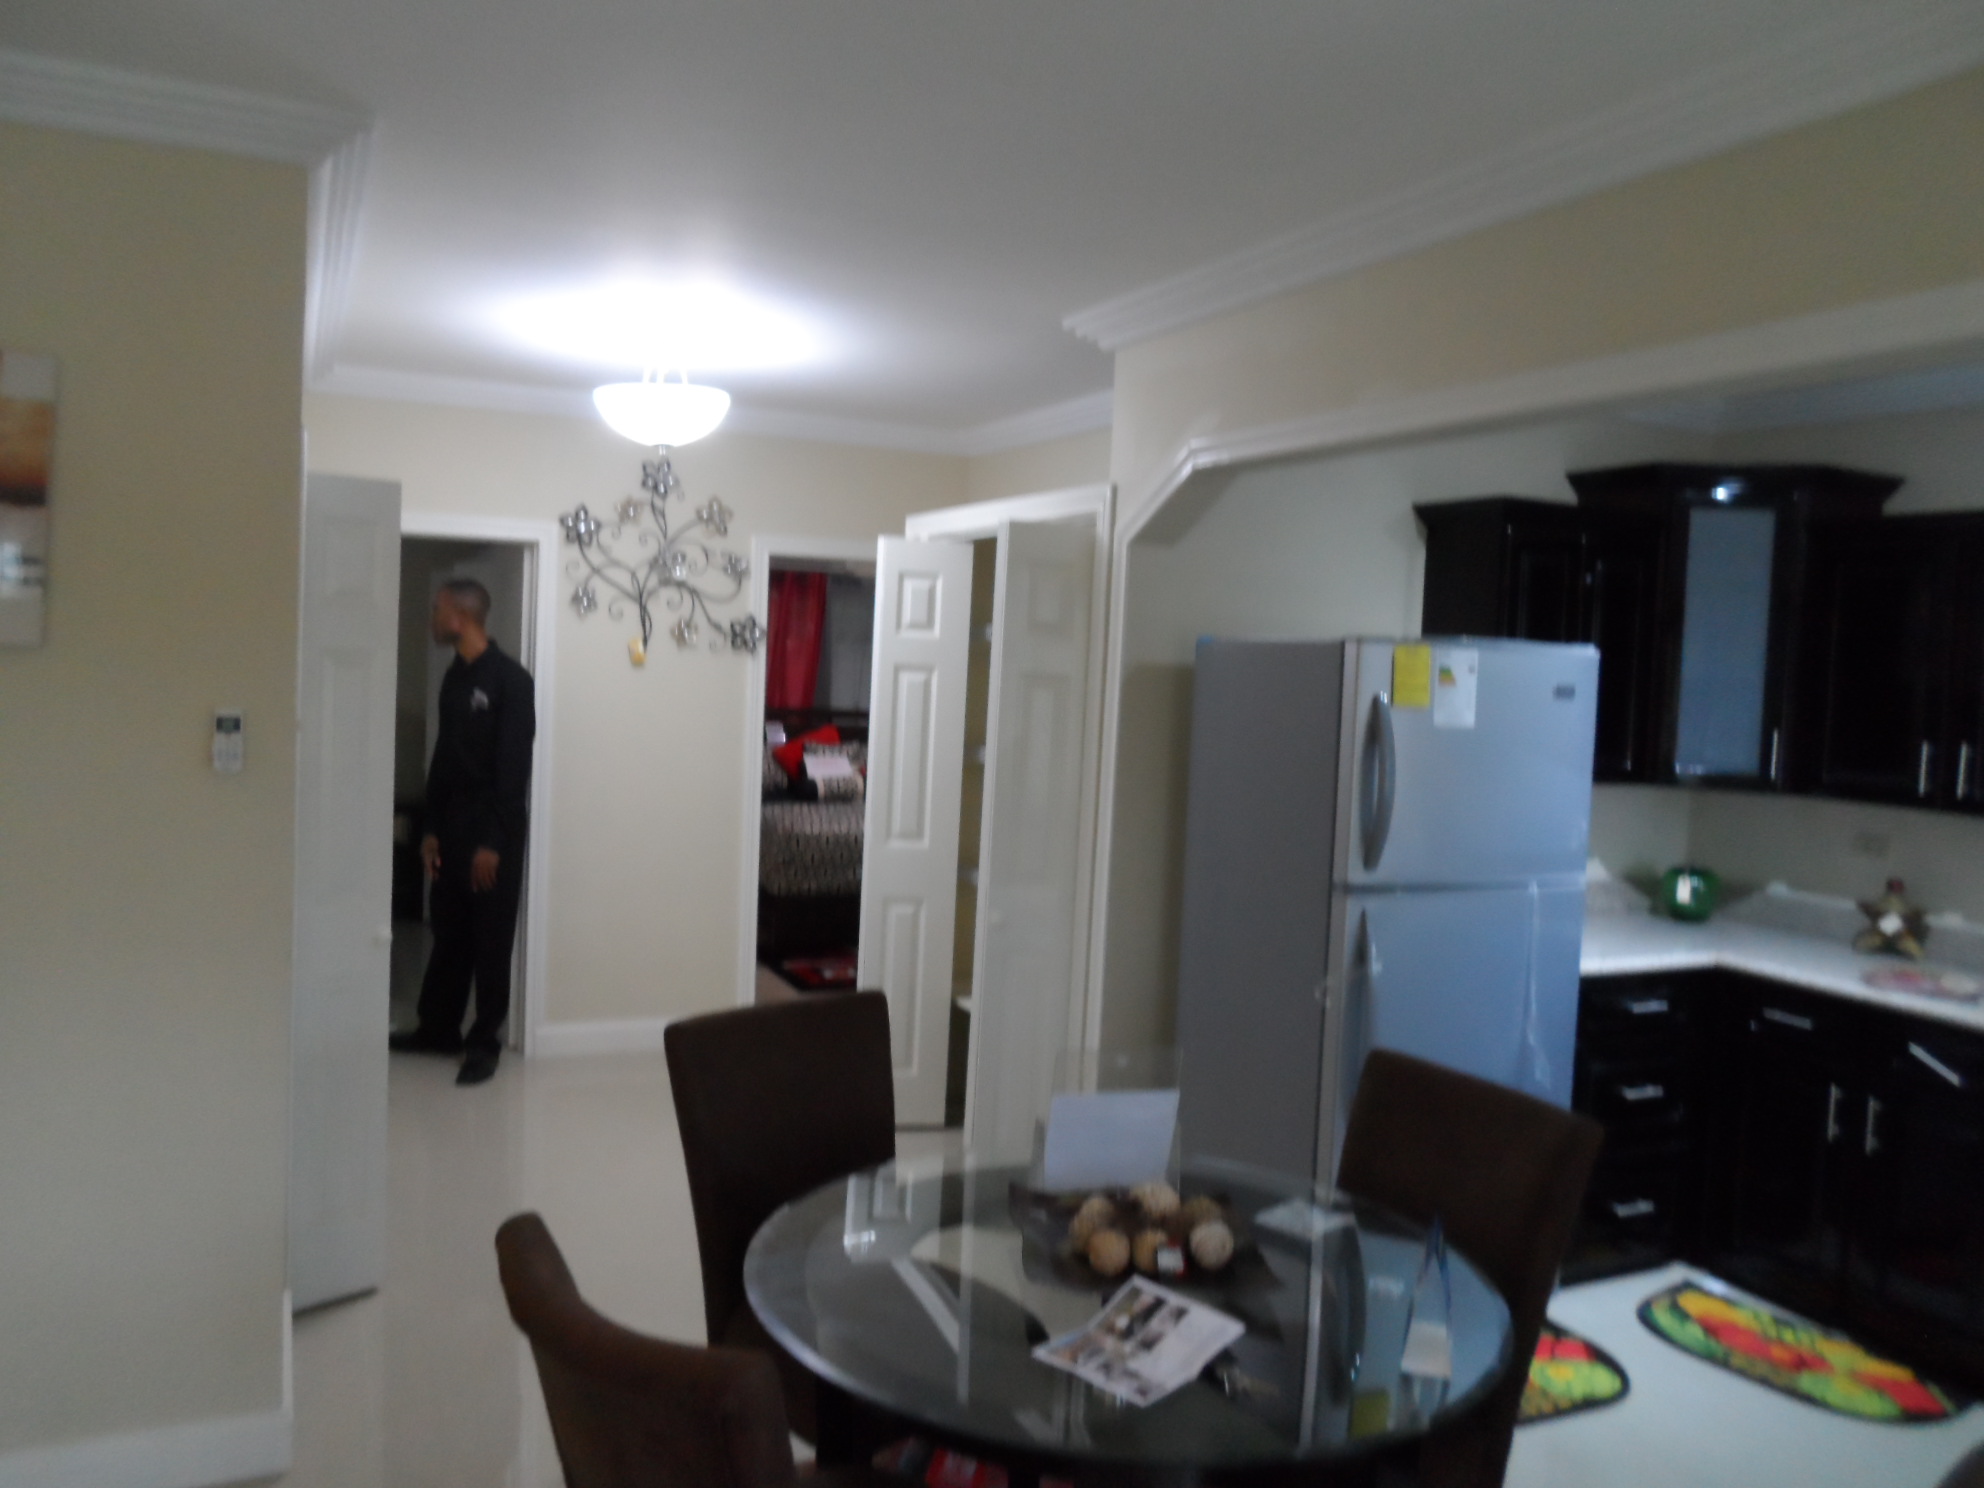
Living room for 1 bedroom unit
The complex is gated, units are floored with porcelain tiles and have granite counter tops. The sizes are, 1 bedroom units 531 square feet, 2 bedroom – 816 square feet and penthouses 769 square feet.
The selling price per square foot works out at $19,585 for the 1 bedroom and $16,409 for the 2 bedroom units.