 Revenues shot up 15 percent for the six months to June this year to $2.33 billion at Kingston Wharves from $1.94 billion over the corresponding period of 2014. Revenues for the quarter reflected an increased 19 percent to $1.19 billion or over the June quarter last year.
The increased revenues, generated net profit attributable to shareholders that grew by 21 percent over in the prior year, from $354 million to $427 million for the half year and for the June quarter and only 10 percent to $240 million and resulted in earnings per stock of 17 cents for the quarter and 30 cents for the half year. Earnings for the full year should end around 70 cents per share compared to 59 cents for 2014.
The Group experienced lower foreign exchange gains associated with the depreciation of the Jamaica dollar resulting in a reduction in other income.
Direct operating expenses rose faster than growth in revenues with an increase of 26 percent from $1 billion in 2014 to $1.26 billion for the six months period and jumped 30 percent from $510 million to $663 million for the June 2015 quarter.  Administrative expenses rose marginally from $393 million in 2014 to $397 million for the six months period and fell slightly from $200 million to $198 million for the June 2015 quarter.
“Transhipment container volumes handled at the KWL Terminal, during the six months period, increased by 20 percent over the prior year, while domestic container volumes and motor units grew by a further 22 percent and 7 percent respectively” Jeffery Hall, Chairman for the group said in a report to shareholders.
Purchase of property, plant and equipment amounts to $437 million up to June compared to $513 million in the 2014 half year period as the company expands and modernize to attract more business with the opening up of the Panama canal.
The company’s stock closed on Friday with a price of $7.10 compared a net book value of $12 a sells at a PE around 10 this year’s earnings. Less than 5 percent of the company’s shares are held by shareholders outside of the top 10 shareholders. That has helped with the relative higher price of the stock compared with the overall market with a much lower PE.
Kingston Wharves Q2 profit up 10%
Profit jumps 45% at Lasco Distributors
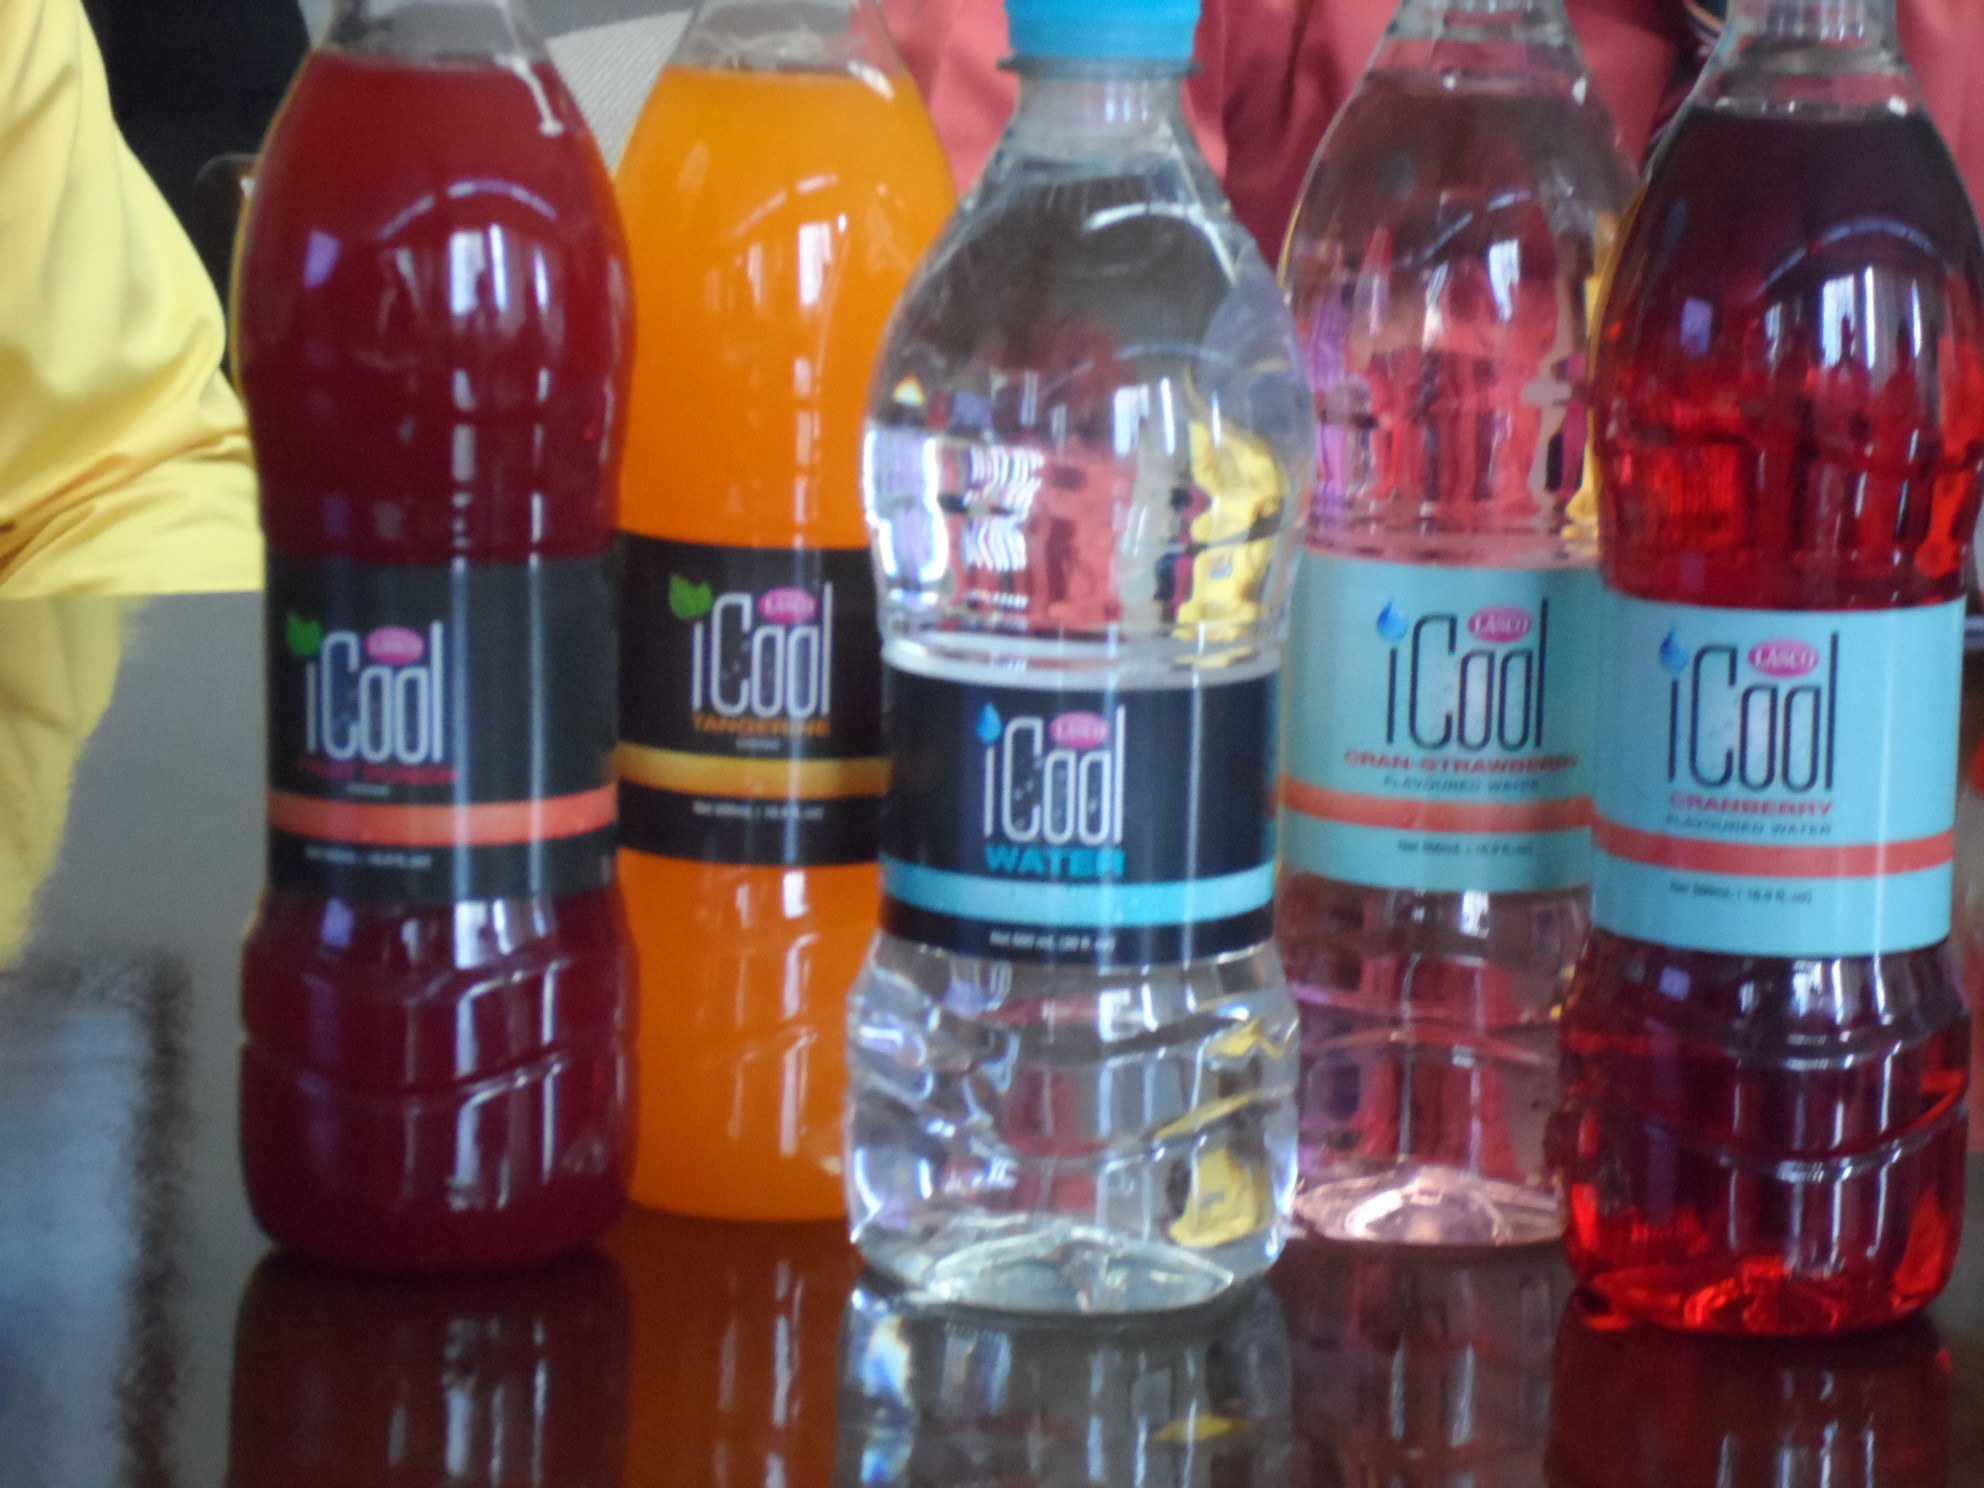
Lasco Distributors” hot new “I Cool” drink.
“The main contributing factors to the increase revenues were the increase in volumes of iCool beverages and additional revenue from the distribution of the full range of Unilever Products”, Peter M. Chin, Managing Director reported to shareholders in the directors’ report accompanying the financial data.
“Increase logistics costs for the period and the continued aggressive selling and marketing activities resulting in the gross profit margin being lower by 1.4 percentage points than the prior year. The aggressive efforts to drive demand for our newly launched iCool brand of beverages has been successful as the company achieved a significant increase in volumes’, Chin went on to say.
 Cost of sales rose 41 percent to $1.75 billion faster than revenue growth but still allowed for the strong increase in profit. Gross profit margin came out at 16.9 percent down from 18.25 percent in 2014 and declined to 17.94 percent for the 12 months to March 2015 from 19.37 percent in 2014. Administrative, selling and other expenses rose 22 percent to $441 million during the June quarter, from $361 million in 2014.
“For the reporting period Current Assets increased by 24.5 percent or $951 million. The major contributory factor was Trade and Other Receivables category which increased by 48.1 percent or $776 million, this was a result of the increased Credit Sales and Principal activities. Inventories increased by 33.6 percent or $436.7 million due to new products to market and new business agreements, Trade and Other Payables increased by 34.4 percent or $615 million over the corresponding period,” Peter M. Chin, reported.
Earnings per share ended at 4 cents, and IC Insider is forecasting 35 cents per share for the full year which would be well ahead of the 16 cents earned for the 2015 fiscal year.
While the stock is trading at $1.90 or 5.5 times current year’s earnings, making the stock attractive especially as profits are likely enjoy a big uptick in 2017 as well with more products to distribute. Investors need to bear in mind that profits become taxable at 12.5 percent starting in the second half of this fiscal year, for five years.
Producers’ office sale shores up cash
Charles Johnston – Chairman of JP Group
Borrowings have gone up considerably to $2.15 billion from $1.18 billion at the end of June 2014, not something the group is known for in the past.
The real story shows up in the cash flow statement. Cash generated from operations was negative $340 million for the half-year and possible $700 million for the full year, with loan repayments to be made and cash and investments which are down from what use to obtain in pass years, with $730 million at the end of June this year. Producers needed to shore up the cash position and may need to do so again before too long. The company’s investment in associated companies and Joint Ventures is the area generating most profit. Management has less direct control over cash generated by these entities and profits booked may only realise a very small cash return.
The group reported earnings for the second quarter attributable to shareholders of $414 million but the bulk of that, $319 million, came from gain on sale of fixed assets. For the year to June, net profit attributable to JP shareholders was $589 million compared to $138 million in 2014 of which $429 million came from gains on disposal of fixed assets and investments.
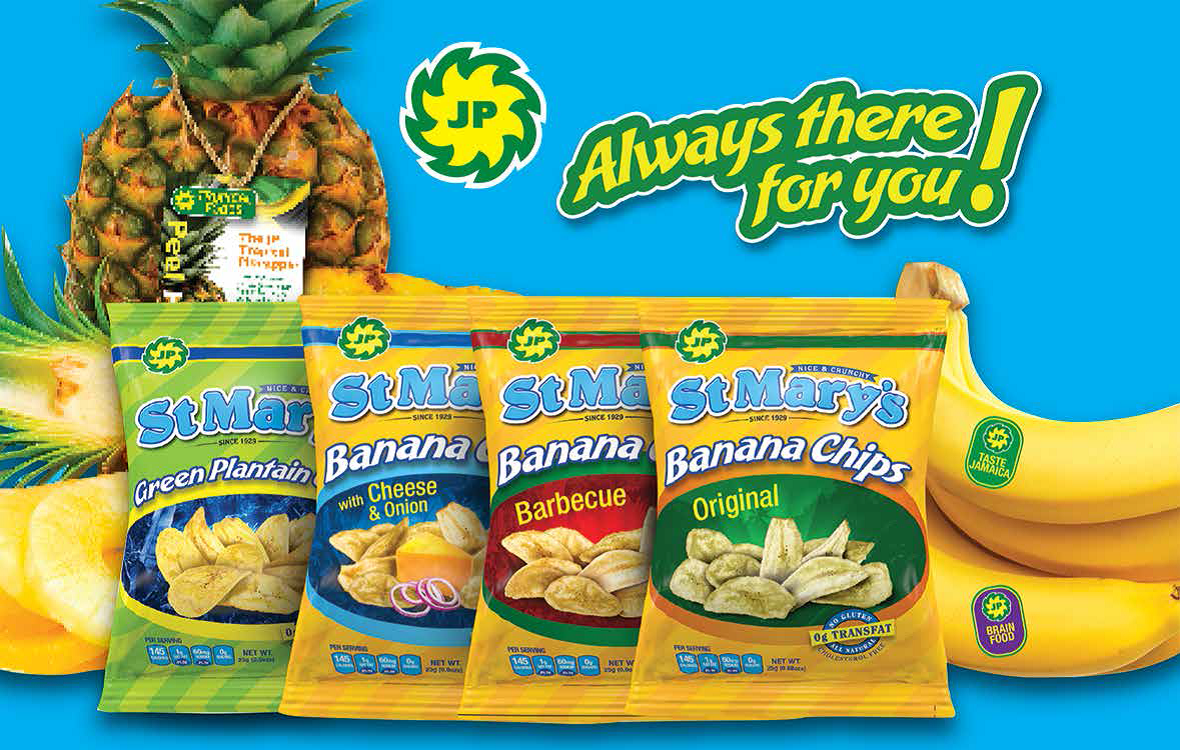
Some of JP consumer products
Take that has a given, but end in 2014, the net results before associate and joint ventures income was just $63 million for the quarter and $42 million for the half year, not earth shattering considering revenues of more than $4 billion for the half year.
Share of profit in associated companies and joint ventures delivered increased results of $172 up from $99 million for 2015 and 2014 quarters, respectively and for the half year $274 million and $167 million partly due to increase shareholdings in Kingston Wharves.
JP management has been hard at work to radically change the group, based on results for the past few years it isn’t easy, although there are now clear enough signs that things are coming together. Producers stock is no longer the darling of investors the way it was in the 1990s and will need to rev up profit and grow at a good clip.
Cable & Wireless’ makeover
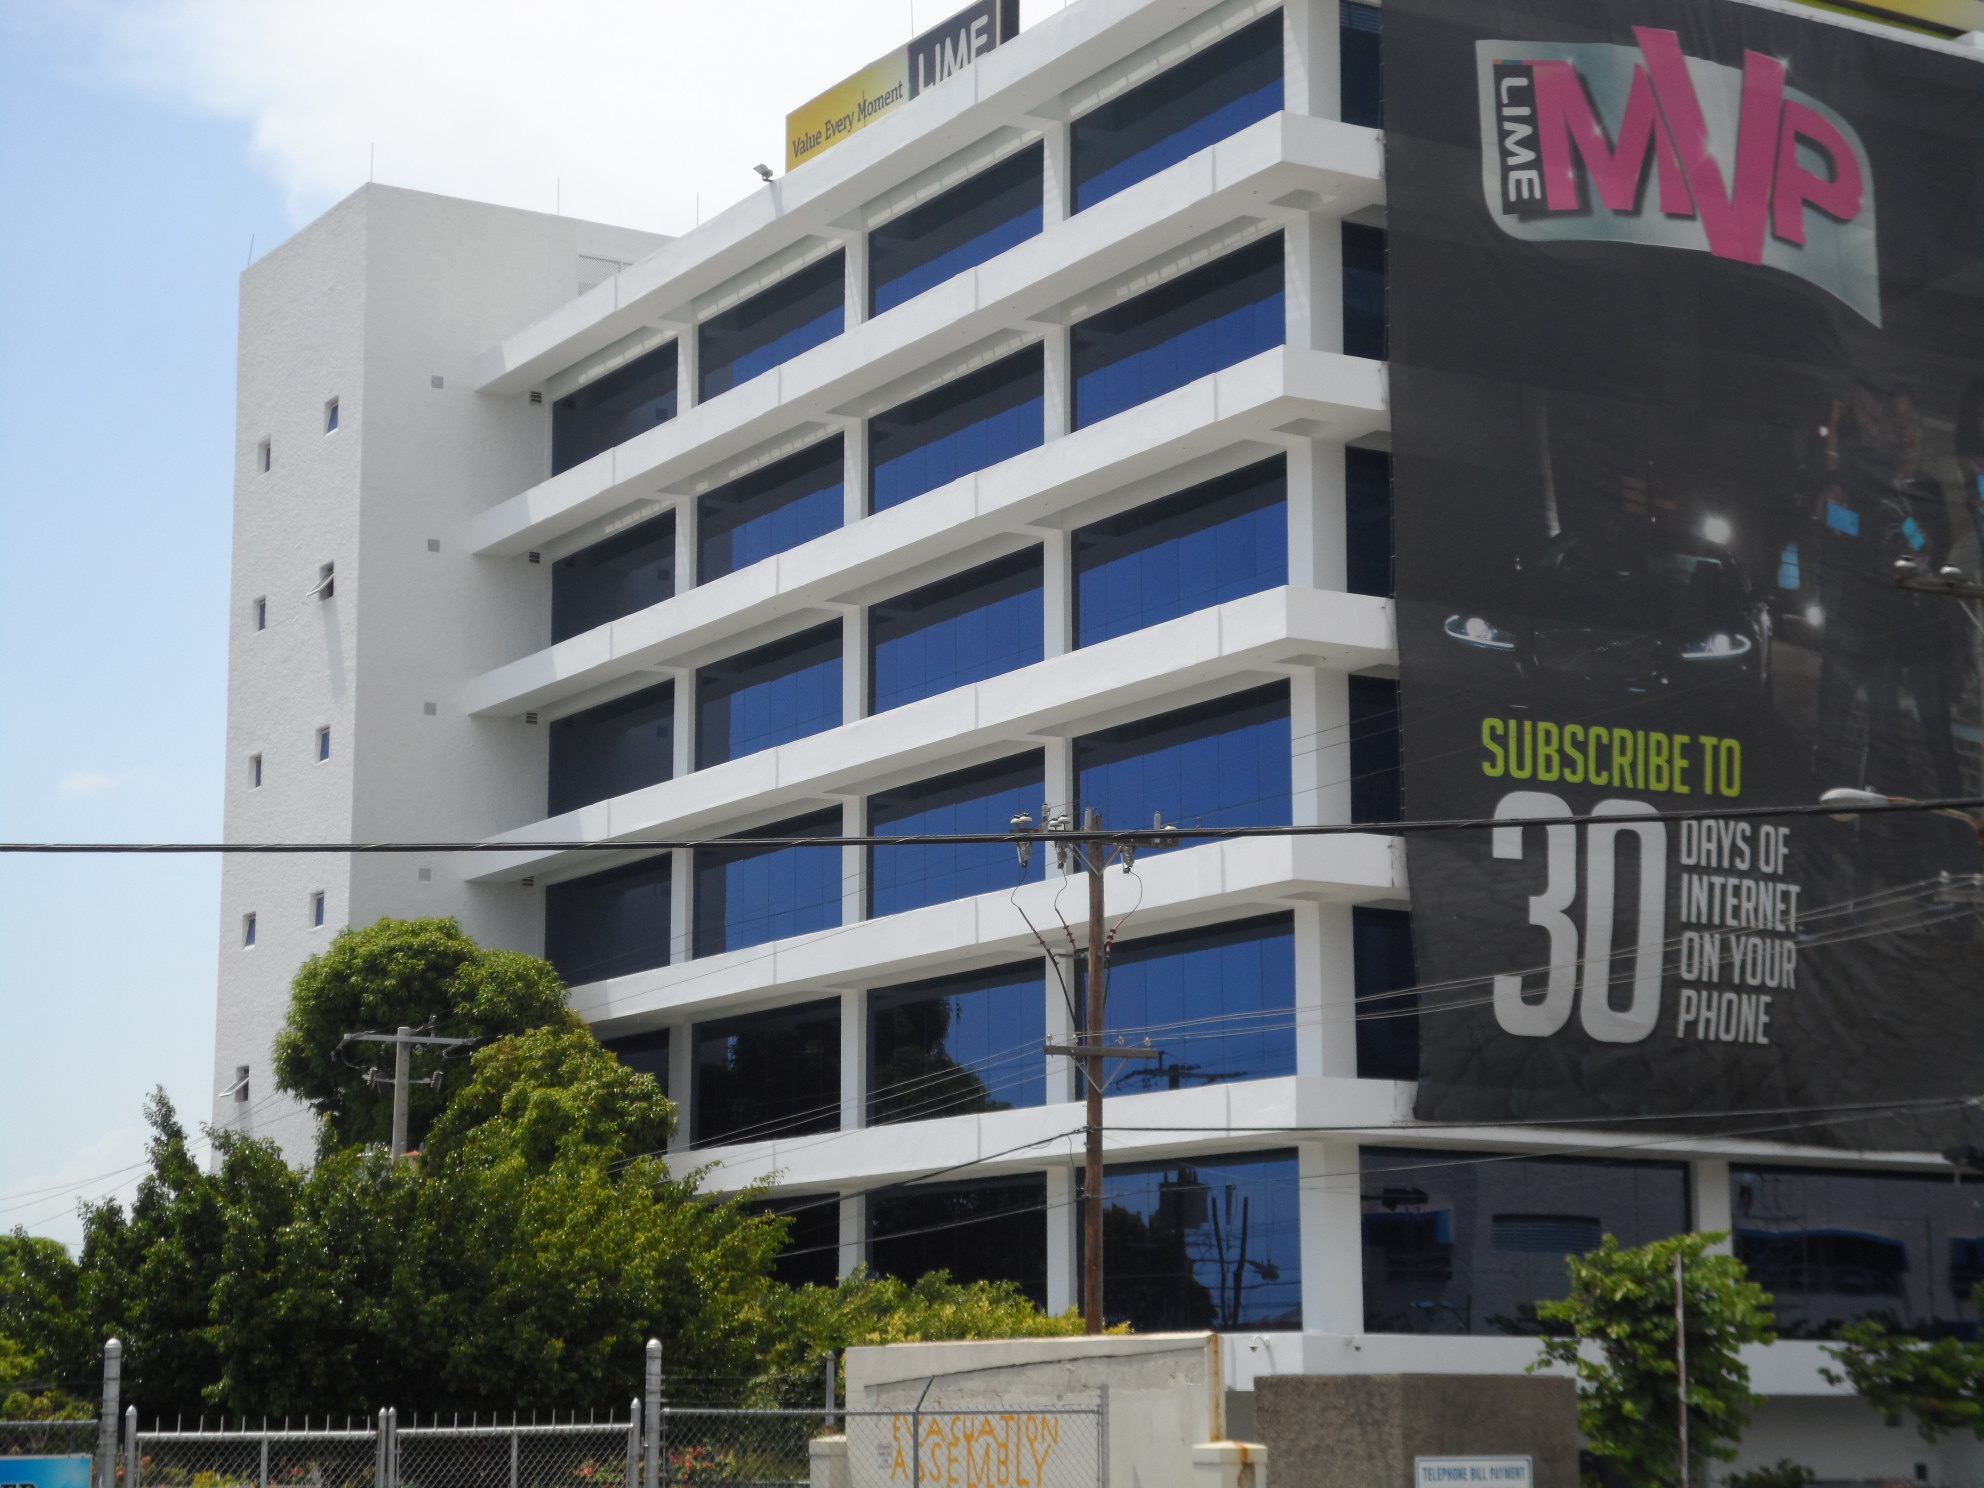
Cable & Wireless HQ – the stock is in demand with the merger of Flow and C&W gathers pace.
There was much growth in the financial year to March and since then the industry has seen much change, with number portability, Flow being acquired by Cable & Wireless and Digicel acquiring Sportsmax.
“We gained around 20,000 new prepaid mobile customers resulting from number portability almost the same as left, revenue for the average new customer is more than the ones we lost” Garfield Sinclair, Chief Executive officer of Cable & Wireless (C&W) stated in a presentation to shareholders and some C&W senior staff at Wednesday’s annual general meeting of the company. Sinclair also stated “we gained four more postpaid customers to each one lost as a result of number portability”.
In a wide ranging presentation at the AGM the C&W CEO stated that the merger of the Flow and C&W has many challenges, none more so than the integration of the staff. The physical plant with differing technologies also pose challenges and with take time to be fully complete. But the CEO stated that they were making progress on all fronts as he commended the Human Resource team in the work they have done in the staff integration so far.
C&W CEO Gary Sinclair
“We now have almost 900,000 cell phone customers, 250,000 landlines and 80,000 data only customers”, Sinclairstated. At the end of the fiscal year to March C&W indicated that the cell phone numbers were around 820,000 but Sinclair confirmed to IC Insider that the numbers are now at 875,000. The annual report stated that in the “peak season Christmas a record 65,000 mobile customers were added to the network”. The 2015 numbers suggest a continuation of the strong gains being made in the acquisition of mobile customers. The name change from LIME to Flow is likely to enhance the prospects for increased mobile customers. The continued growth augurs well for increased revenues and the company’s move to restart generating positive profit.
“Investors have to judge us on the EBITDA not on accounting profits that is the basis used in our industry”, Sinclair said. In this regard he said that by the end of the current fiscal year EBITDA that was at 20% of revenues in 2015 should be at 30 percent. This would work out at around $7.5 billion assuming revenues continue to grow at the 2015 pace on a standalone basis and would result in an absolute profit for the company, the first for several years. In the June quarter EBITDA rose a very strong 82 percent, with net results seeing a sharp fall to a loss of just $303 million, from a loss of $712 million in 2014 as revenues grew 13 percent to $5.45 billion, for the June 2015 quarter, aided by a 17 percent growth in mobile subscribers and 27 percent increased mobile revenues. Operating expenses were static at $4 billion but finance cost was up to $1.1 billion from $962 million in 2014, depreciation was down and amortization up.
EBITDA while an important measure, especially in the expansion phase it cannot be the sole target, ultimately investors want a return on investment and net profit ultimately is the most important measure so that dividends can be paid.
While there were few details of the merger with the Flow operations, that is expected to be a big boost to the system with more revenues and lower cost with some of the cost squeezed out from the elimination of duplications.
ICooled profits hike at Lasco Manufacturing
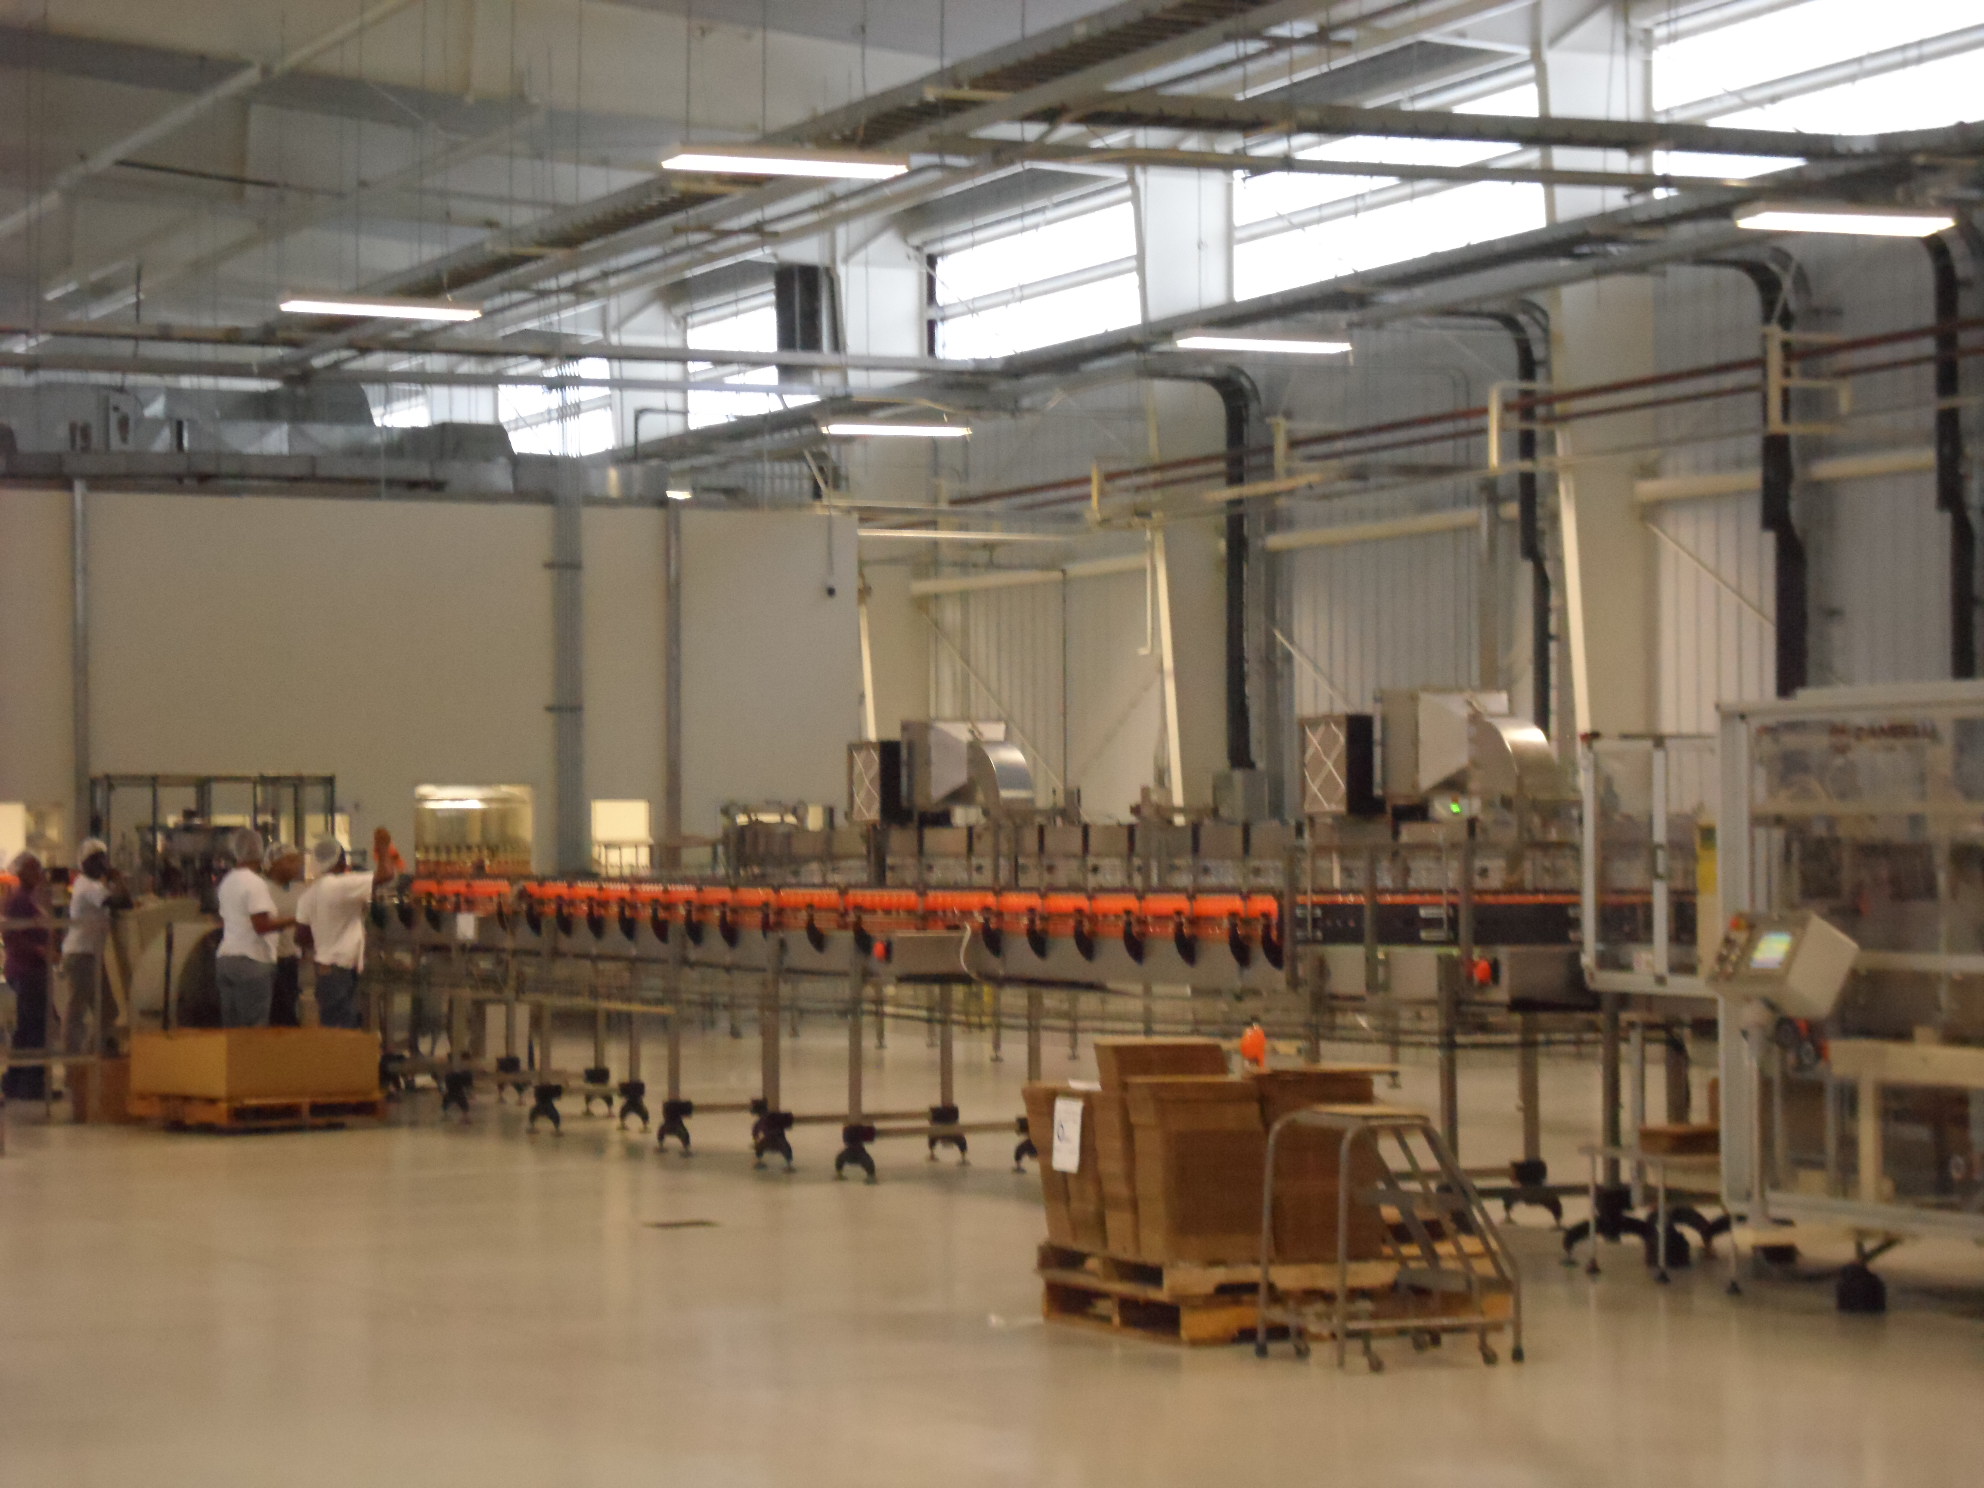
Lasco Manufacturing’s bottling line.
Gross profit margin for the quarter climbed to 33 percent from 29 percent in 2014 but gross profit jumped 50.50 percent well above the growth in revenues, a positive development for continued strong growth in profit going forward.
Operating Expenses climbed 29 percent to $185 while finance cost rose from $32 million to $42 million as a result of construction phase of the factory completed, resulting in the interest on the funds used in construction being expensed as opposed to being capitalised during the construction phase.
With new factory facilities completed and in use, depreciation ended at $67 million for the fiscal year up from $27 million in 2014 but is set to jump in 2016 with only a fraction of the annual charge being booked to March 2015. With more monies to be transferred to fixed assets for the year to March 2016 depreciation cost should climb. At the end of March, net book value of property, plant and equipment amounts to $3.4 billion and includes assets under construction of $1.34 billion. The cost of assets under construction will be depreciated once the property is complete and in use. The estimated additional cost of completion of the facility was $373 million at March, since then more than $150 million was added to fixed assets.
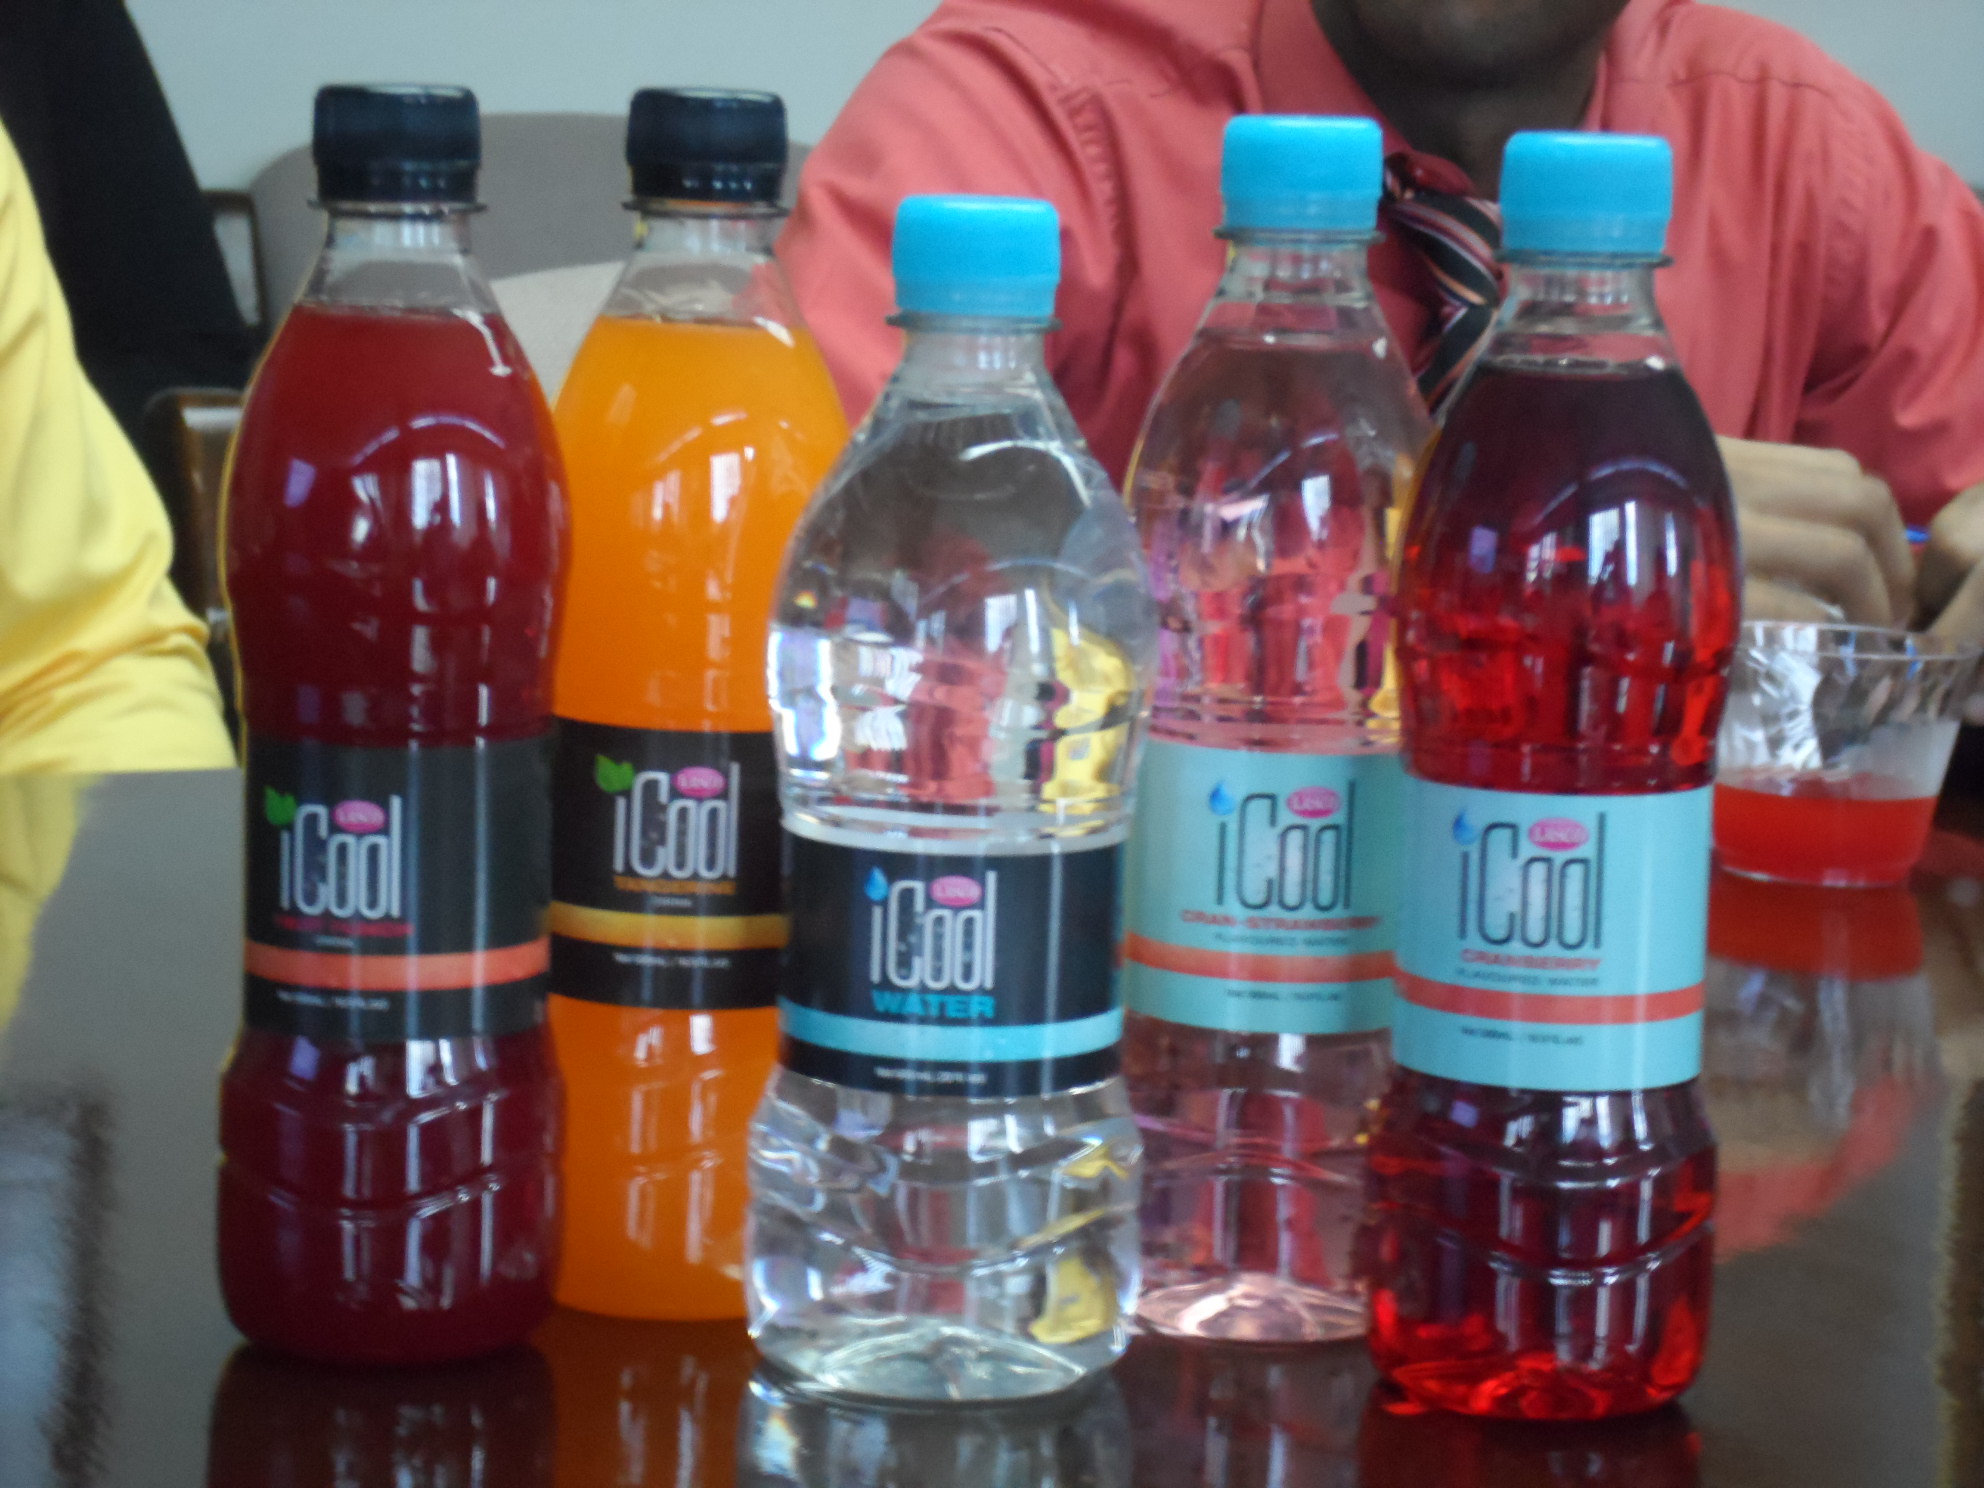
Lasco’s new I Cool drink distributed locally by Lasco Distributors, produced by Lasco Manufacturing.
At the end of the June quarter, Inventories stood at $736 million and is up from $433 million and Receivables jumped to $1.26 billion from $846 million at the end of June 2014. Borrowing stands at $1.86 million against equity capital of $5.8 billion.
IC Insider projects profit at $1.6 billion for the year or 40 cents per share for the year to March 2016, that should jump to around 60 cents for 2017. While the company becomes taxable this year capital allowances plus tax will be a 12.5 percent will result in little or no taxes being paid on profit for the year.
The company is listed on the junior market of the Jamaica Stock Exchange and last traded at $1.90 for a PE of just less than 5 based on IC Insider’s projected earnings. The stock should deliver a healthy increase in price during the fiscal year and the next as the expanded product lines and the new factory deliver increased revenues at reduced cost.
Lasco Manufacturing has been a BUY RATED stock for some time and remains with that status.
Knutsford’s flawed audited statements
 If the Jamaica Stock Exchange and the Financial Services Commission have the interest of investors at the forefront for protection they would demand the total withdrawal Knutsford Express’ audited reports for 2014 and 2015. The audited statements for both years, are filled with errors or questionable treatment of transactions, raising questions about the accuracy of the entire reports.
The report for 2015 has profit of $69 million or 69 cents per share versus $50 million in 2014 or $1.07 cents per share after deferred taxation of $5 million (2014: $5.6 million). Revenues amount to $454 million, a big 38 percent increase over the $329 million in 2014. Problem is that the earnings per share for 2014 is overstated due to inaccurate computation of the average number of shares issued in 2013. Further, the audited statement while showing earnings per share of $1.07 for 2014 in the income statement, goes on to state erroneously by way of a note, that “using the weighted average number of shares at end of 2015 would result in earnings being 50 cents for 2014”.
Since Knutsford is not taxable for the next 4 years it is difficult to see why the company would need to compute differed tax charge when whatever timing difference is likely to be less than 4 years on which no tax would be payable, the report does not give details so it is difficult to determine what items would result in such differences, but a look at the detailed expenses suggest that at best it would be a one year difference hence there is no need to book the differed tax.
 The audited financial report states “During January 2014, the Company raised additional capital of $99,862,700 from its initial public offering of 99,999,003 shares for its enlistment on the Jamaica Stock Exchange Junior Market”. This of course is completely wrong since the company issued 26 million bonus shares in 2013. While the public offering was for 20,000,000 ordinary shares, only 4,867,338 shares were offered by the company and 15,132,662 shares were existing shares of the pre IPO shareholders. At the time the IPO came, 95,132,662 ordinary shares were already issued, the average number of shares should be around 60 million rather than 46.8 million used to compute the 2014 EPS which would have worked out around 83 cents. That is around what it is and should be reported as. In addition there is no need to re-compute this figure and the 100 million shares in existence won’t change it one bit.
In the taxation note it states that the company at the end of 5 years “is required to delist and pay all exempted taxes within 5 years or opt to list on the main exchange for the next 5 years to maintain tax exemption received in the last 5 years. That seems to be stated incorrectly, IC Insider went to the manager of the stock exchange for clarification.
“ Those companies that have been given five (5) years will have to remain listed for 10 years as compared to 15 years had they been given 10 years incentive. They are not compelled though to migrate to the main market but can remain on the Junior Market if they are in compliance with capitalization and other Junior Market requirements”, the Stock Exchange reply stated.
 The junior market rules require a mentor for these companies. One reason is to ensure that slip up like the above don’t happen. The issue begs the question what are the board of directors doing, after all they sign off on the financial report, they should ensure that information included that they are aware of, are not incorrectly stated.
Income statement| It would have been very informative if the profit and loss statement carried cost relating to functions such as direct operating cost, marketing and sales rather than all cost being lumped into administrative and other expenses, then one would easily see how the operating side of the business is doing before administrative cost.
But other questions remain, the listing of expenses show employer’s statutory payroll contributions at $31.84 million for 2015 and $16.58 million in 2014 versus salaries and related expenses at $86.86 million in 2015 and $54.65 million in 2014, these work out at 27 percent and 33 percent respectively. That of course cannot be correct as it should not be more than roughly 10 percent for Education taxes, National Housing Trust, Heart and National Insurance.
Small profit gain for T&T’s Republic
 Trinidad’s Republic Bank reported slightly improved results to June, with profits attributable to the group of $325 million in the June quarter up on the $308 million generated in 2014 and an increase to $898 million for the nine months against $869 million in 2014.
Earnings per share for the quarter is $2 cents and year to date $5.56, earnings for the full year should end around $7.60 up from $7.39 in 2014, placing the PE at a $113.99 stock price at just over 15 time earnings.
Net interest income is up 8.7 percent to $618 million for the June quarter and a slower 5.4 percent for the nine months from a year ago to $1.79 million. Total net revenues climbed 26.7 percent to $1.1 billion for the quarter and 3.3 percent for the nine months to June to $2.9 billion. Expenses rose in the June quarter, to $554 million, from $454 million, is down for the year to date, to $1.56 million from $1.58 billion. Loan loss provisions are sharply in the quarter to $122 million and for the nine months, $145 million was booked versus $79 million in 2014. The bank reports that increased provisions were done for the new acquired subsidiary, Ghana HFC Bank to bring the provisioning policy in line with the group’s and impairment loans and goodwill for the Cayman Islands subsidiary.
With strong growth in loans in the June quarter over March, loans which grew to $27.6 billion in March now stands at $29.7 billion and is up 11.65 percent over June 2014 and 9.7 percent over September 2014 and 10.76 percent over April. A big part of the growth is the consolidation of the financial statements of the 57 percent controlled, HFC Bank into the group, adding loans of $1.27 billion in the June quarter. The Ghanian bank was previously treated as an associate with 39.87 percent ownership but Republic who acquired an additional 17.25 percent under a mandatory takeover offer, raising the holdings to 57 percent in May this year.
In July Republic completed the acquisition of the bank in Suriname that was previously owned by RBC Royal Bank with assets of $3.3 billion, a small increase to the groups $62.33 billion in assets at the end of June.
Loans & profit up at T&T’s Scotiabank
 Trinidad’s Scotiabank reported improved results to July, with profits of $157 million in the July quarter, up by 12 percent on the $140 million generated in 2014 and much slower 7 percent increase to $417 million for the nine months against $390 million in 2014.
Earnings per share for the quarter is 89 cents and year to date $2.36, earnings for the full year should end around $3.40 up from $3.18 in 2014, placing the PE just over 18 time earnings based on the stock price of $62.50 it last traded at on the Trinidad & Tobago Stock Exchange. For 2016 earnings should end up around $4 per share all things being equal. All things may not be equal, with reports of negative economic growth in the first quarter of this year and low oil prices, that could result in lower consumption and weaker economic activity.
The July quarterly profit gain is down on the 18.4 percent reported for the April but much more than the $125 million earned in that quarter. For the July quarter revenues jumped sharply by $31 million over April and operating expenses dived by $13 million while loan loss provision was down by nearly $5 million.
Net interest income is up 11 percent to $251 million for the July quarter and a slower 7 percent for the nine months from a year ago to $711 million. Total net revenues climbed 9.3 percent to $378 million for the quarter and 8.2 percent for the nine months to July to $1.08 billion. Expenses fell in the July quarter, to $152 million, from $156 million, is up for the year to date, to $481 million from $466 million. Loan loss provisions are down in the quarter to just $4.5 million and for the nine months $30 million was booked versus $19 million in 2014.
Growth in the loan portfolio is one of the main contributor to increased profit. With only moderate growth in loans in the July quarter over April, loans which grew to $12.8 billion in April now stands at $13 billion and is up 11.3 percent over July 2014 and 11 percent over October 2014. If the bank can maintain this level of growth in loans into 2016 then profits should continue to increase double digit growth levels.
The bank will be paying a 40 cents dividend on October 9 to shareholders on record at September 11, the stock now generates a dividend yield of 2.5 percent.
Knutsford’s sales up 38% cost 44%
 Knutsford Express’ audited report for 2015 shows a big 38 percent surge in profit to $69 million over the $50 million in 2014, from revenues of $454 million, 38 percent more than the $329 million generated in 2014. With that level of revenue increase profit should have grown much faster than it did, and should have been closer to doubling.
New routes added could have been a factor as passenger traffic takes time to build up, more importantly, increased cost in a number of areas seems more the culprit. Expenses for 2015 are up 41 percent but excluding $4.58 million of IPO cost included in 2014, the increase would have been 43.5 percent. The overall increase comes against the fact that fuel rose only 12 percent to $70 million and accounted for 19 percent of cost, down from 24 percent in 2014. Excluding fuel, all other costs are up 50 percent over 2014 and 54 percent, excluding the IPO cost, well over the revenue increase of 38 percent.
Staff and labour cost jumped 72 percent to $126 million and now accounts for 34 percent of cost up from 28 percent.
Telephone cost rose 68 percent to $7.9 million. Rent grew 61 percent to $7.8 million, travelling was up 160 percent to $6 million, advertising and promotion grew only 30 percent to $12.4 million and is one of the items that grew more slowly than revenues.
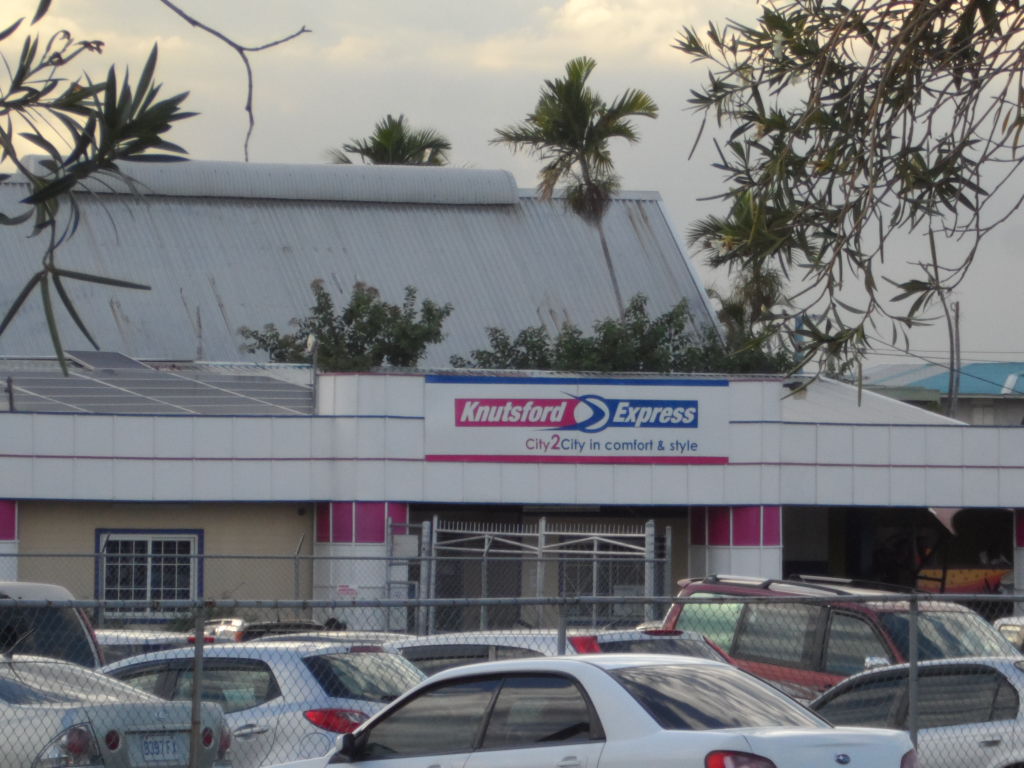
Knutsford’s New Kingston depot
Some items of cost such as repairs and maintenance actually fell while others such as electricity and office supplies rose more moderately than those above.
Profit falls at Massy
 The results for the nine months for Massy Holdings showed improved profit after tax for both the nine months and the third quarter ending June, in reality profits from normal operations fell in both periods. Revenues increased by 12.7 percent to $9 billion for the first three quarters of the 2015 financial year from $8 billion, due mainly to the acquisition of a subsidiary in Columbia in the last quarter of 2014 that contributed $650 million to revenue and $10 million to pretax profit.
Profit before tax increased by 5 percent from $558 million to $586 million. For the June 2015 quarter profits fell before rebranding cost to $175 million versus $208 million in 2014. In 2014, Massy group incurred $59 million in rebranding before tax and would have suffered a decline in both the quarter and nine months results, excluding this one off cost. Additionally, there was increased interest expense of $29 million above that of 2014 from raising $1.2 billion in 2014 to refinance short-term debt and to fund new projects. Earnings per share for the nine months come out at $3.95 and $1.19 for the June quarter.
Operating profit before finance costs declined to $180 million from $208 million, for June 2014 quarter and for the six months $625 million versus $616 million.
During the nine months, the Insurance division contributed 23 percent more to revenues to reach $249 million percent, and delivered $36 million to profits up from $26 million in 2014. Automotive & Industrial Equipment had revenues of $1.78 billion and profit of $171 million, for 2014 revenues amounted to $1.58 billion with profit of $154 million. Retailing had revenues of $5 billion compared with $4.6 billion and profit of $268 million in 2015 versus $273 million in 2014. Energy & Industrial Gases saw slightly lower profit of $154 million versus $168 million in 2014 from revenues $1.15 billion in 2015 and $772 million in 2014. Information technology revenues of $410 million slightly higher than the $414 million in 2014 and profit of $45 million from $53 million and Other Investments experienced revenues of $349 million, down on the $374 million in 2014 and profit of $60 million from $71 million.
Massy had lower revenue in the critical and home market with reports indicating a contraction in the economy and continued tightness in the Eastern Caribbean markets. With oil prices set to remain at low levels for a while the company could be challenged to grow profits in the near term.