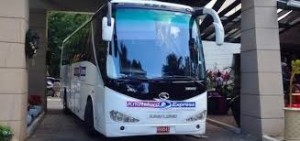
Knutsford Express revving up

One of Knutsford Express buses.

Jamaica’s intra island transport company, Knutsford Express, is enjoying extraordinary times, with a sharp increase in revenues and profits but the company’s management is not sitting on their laurels as they actively seek areas for future growth and profits.
In the latest quarter to August, revenues jumped a strong 37 percent, to $237 million and spawned a 57 percent rise in profit of $57 million. Of interest is the continued growth, on top of previous year’s increases. For while revenues in the August 2016 quarter rose 21 percent with flat profit, by the second quarter revenues climbed 37 percent over the 2015 levels, to $176 million and profit rose 19 percent to $30 million.
Revenues rose 33 percent for the third quarter to $203 million and profit almost doubled to $53.7 million, thanks partially to an $8.5 million gain on sale of fixed assets. Excluding the one off gain, profit would be up 63 percent for the quarter. Expenses increased 25 percent, quite a bit slower than revenues, helping in the growth in profit. Knutsford, unfortunately does not break out direct operating expenses from administration cost but data shows that certain direct cost not counting labour cost, to be around a third of revenues. Increased revenues would have added close to 50 percent of the increase in overall cost.

Knutsford’s New Kingston depot

By the end of 2017 fiscal year revenues climbed 29 percent over 2016 and profit by 28 percent, just below the 35 percent increase for the nine months to February. Operating revenues for the last quarter of the just concluded fiscal year was in line with the amount generated in the third quarter.
When the company went public, it had 54 employees in 2013, up from 47 in the previous year, climbing to 100 by May 2016, and remaining there to May this year, resulting in some economies of scale.
IC Insider.com is forecasting revenues to pass the $1 billion mark for the first time, by the end of the fiscal year with profits ended up around $280 million or 50 cents per share, with the next fiscal year’s earnings hitting 90 cents per share. The stock trades on the Junior Market of the Jamaica Stock Exchange around $15 with a PE ratio of 27 and 16 times 2019 earnings versus 14 for the market currently.
Knutsford generated $73 million in cash flow for the quarter and expended $69 million on the acquisition of fixed assets to end up with $85 million in cash and bank balances and investments $92 million. The company owes $55 million in loans and boast net worth of $539 million.
Big jump in Paramount profit

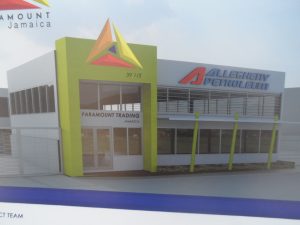
Paramount new designed offices.

Junior Market listed Paramount Trading, enjoyed a big turn-around in profit for the first quarter to August this year, with an increase of 126 percent, to $34 million from a 31 percent increase in revenues to $331 million.
Importantly, Paramount incurred exceptional expenses in the first quarter, last year, as the company celebrated its 25 anniversary, IC Insider.com estimates the cost to be around $20 million, excluding this one off cost, profit would have been flat, in both periods.
Administrative and other expenses jumped from $44 million to $62.7 million, but selling and marketing cost dropped from $24 million to $2.8 million. Direct cost rose 35 percent, reducing gross profit margin with gross profit rising slower than the increase in revenues, at 23 percent to reach $101 million.
Earnings per share amounts to 2.2 cents. IC Insider.com places full year’s earnings at 19 cents and for the 2019 fiscal year to May 30 cents with the coming on stream of the joint venture lubricant plant.
The directors’ report stated that they have “an optimistic outlook for the rest of the year and is very excited by the opportunities that will be realized. The construction of the blending plant and laboratory, in conjunction with Alllegheny Petroleum is slated to be complete during the next quarter.”
The balance sheet shows net current assets of US$463 million, including inventories of $338 million, receivables of $283 million and cash funds and investments at $97 million. Borrowings are at $55 million up from only $16 million in August 2016.
The stock currently trades at a PE ratio of 15 with the price at $2.90 on the Junior Market against the market average of 14 and seems to be line with the market. What is true, is the nimbleness of management to identify new income generated opportunities that makes staying close to the stock potentially profitable.

Profit surges 137% at Express Catering

Starbucks one of the brands Express Catering will sell at the Montego Bay Airport.

Recent Junior Market listed Express Catering, enjoyed a big surge in profit of 137 percent to US$834,447 for the quarter to August, this year.
With management fees removed and revenues jumping 9.7 percent, in line with increased visitor arrivals to Jamaica, Express Catering, operators of a series of restaurants within the Montego Bay’s Sangster International Airport good performance, came from revenues of US$3.8 million for the quarter.
The removal of management fees saw administrative and other expenses falling from US$2 million to US$1.7 million, but gross profit rose by US$157,000 as cost of sales grew faster than the top line, at 21 percent thus reducing profit margin. Management in their commentary on the results states that “they have since raised prices to compensate for increased input cost.” Express reported earnings per share of 0.051 US cents. IC Insider.com places full year’s earnings at 26 Jamaican cents and that for 2019 at 40 Jamaican cents.
“The addition of the Starbucks Coffee to the offerings in the airport is expected to be completed during the third quarter. Work as already commenced on this initiative and will see 3 locations within the Airport,” the directors’ report stated.
The balance sheet shows US$4.56 million due from related party an increase from $3.64 million at the end of May and cash funds at $497,000.
The stock currently trades at a PE ratio of 19 with the price at $4.95 against the market average of 13.6.

Carib Cement Q3 profit $748m

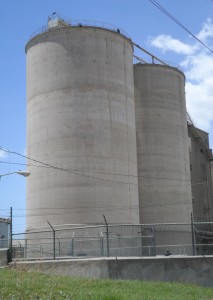
Carib Cement silos.

The Jamaican based Caribbean Cement, sole producers of cement in the country, is reporting profit of $748 million after taxation of $99 million for the September quarter.
Profits arose from revenues of $4.18 billion, up from sales of $3.68 billion in 2016, due mainly to a 15 percent increase in volume sales locally. The result compares to a loss of $81 million in the similar quarter last year. For the nine months to September, profit after tax ends at $1.8 billion versus $973 million in 2016 and well ahead of the $1.3 million reported for the 12 months to December 2016. Revenues for the nine months, amounted to $12.26 billion, up from $12 billion in 2016.
Cost were mostly kept within the levels incurred in 2016 except for a sharp increase in fuel and electricity cost that jumped from $530 million to $759 million in the quarter and moved from $1.87 billion to $2.2 billion for the nine months, but repairs and maintenance fell to $254 million from $358 million in the 2016 third quarter but was slightly down for the nine months at $650 million.
Cement ended the quarter with cash at $1.6 billion after $1.57 billion was expended on additional fixed assets.
Earnings per share for the quarter amounted to 88 cents and $2.13 for the nine months, with the full year looking to exceed $3. Importantly, the results should be looked at not so much for the out turn for 2017, but what it means for full year earnings in 2018. IC Insider.com expects demand for cement to continue to rise as the economy gathers steam and the company renegotiates the leasing arrangement for equipment that is expected to lower the cost in that area going forward, pushing earnings well over $4 per share. The stock closed on the Jamaica Stock Exchange on Wednesday at $29.01.

KIW rises from ashes set to relist

KIW international holds its annual general meeting on Wednesday 18. The company that was previously listed on the Jamaica Stock Exchange is planning to seek relisting by 2018.
In preparation of relisting the company is recommending a 15 to 1 stock bonus for approval at the general meeting to facilitate the issued capital reaching just over $50 million. If approved, the resultant effect is for the number of issued shares to increase from just under 16 million units, to 255.45 million shares.
In addition, the directors approved a dividend payment of 60 cents per share to cost approximately $10 million and payable later in the year.
The company suffered from liquidity problems in the 1990s, but gradually clawed its way back with a combination of moderate rental income from leasing the property at Spanish Town Road and in more recent years, income and gains from a growing investment portfolio.
Internal results show a profit of $24 million to March 2017 compared to $31 million in 2016 as gains on investments slipped in 2017 to $21 million from $28 million previously.
The Company is estimated to have assets of approximately $220 million at March this year. The assets include Jamaica Stock Exchange listed stocks, valued around $65 million and benefited from growth in portfolio from $13 million in 2013.
In April the Government of Jamaica sold their interest of approximately 43 percent in the company to Jamaica Teas.
Subsequent to the acquisition of the above shares the board was expanded and reviewed the options for continued ownership of the property at 138 Spanish Town Road. A decision was made to dispose of the property, having received an attractive offer. The proceeds of the sale are expected to be put into investments as the company embarks on a deeper involvement in the investment arena.
The directors of KIW are John Jackson, Chairman, John Mahfood, CEO of Jamaican Teas, Kemillee Mclymont, Attorney at law, Karl Wright, former president of Victoria Mutual Building Society and David Stephens CEO of Apex Perimeter Protection Ltd.

Increased cost squeezes Kremi’s profit

Caribbean Cream delivered better results in the August quarter than in May period with an increase in revenues of 18 percent versus a 1 percent increase in the first quarter.
Profit declined in the latest quarter but by 23 percent, to $35.6 million versus a 40 percent fall in for the six months to $70 million, down from $117.6 million. Cash generated from operations came in at $98 million but Kremi spent $102 million on acquisition of fixed assets.
Gross profit declined by just 4 percent in August quarter versus 14 percent in the May quarter as increase of direct cost outpaced the rise in revenues. In the end revenues came in at $354 million in the August quarter up from $319 million in the May quarter and $300 million in yin 2016 and for the six months $673 million from $615 million in 2016.
Administrative, selling and distribution expenses increased moderately from $71 million to $76 million in the quarter and form $136 million to $147 million for the half year.
At the end of August cash and equivalent amounted to $175 million and borrowed funds $90 million. Shareholders’ equity stands at $662 million.
Earnings per share for the half year is 19 cents and 9 cents for the August quarter. IC Insider.com is forecasting earnings of 50 cents for the full year to February 2018 and 75 cents for 2019. The stock last traded at $6.70 for a PE of 13.4 which is in line with the Junior Market valuation.

Profit doubles at Palace

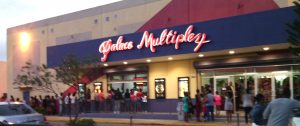
Palace Multiplex in Montego Bay.

Movie house, Palace Amusement doubled profit after tax for the year to June 2017 from an 11 percent rise in revenues for the year and profits could well double again in the 2018 fiscal year, IC Insider.com’s forecast shows.
After accounting for $9 million in taxation, the company ended with nearly $33 million in profit or $22.97 per share. The operation generated $72 million in cash for the year, an improvement from $48 million in 2016.
Revenues from box office, rose by 7.5 percent at the Carib cinema, 8.3 percent at Cineplex and 10 percent at Montego Bay Multiplex. Overall revenues from box office, confectionaries sales, screen advertising and others rose a strong 14.5 percent at Carib, 9 percent in Montego Bay and 7.2 percent at Cineplex, all ahead of inflation of 4.4 percent for the period. Based on the trend in revenue growth, fiscal year 2018 should see $100 million increase and profit per share rising to $50, assuming good quality box office offerings during the period. Pickup in economic activity is great for the company, as its patrons will have more disposable income from increased employment and the recent reduction of taxation on their income and relatively low inflation.
Depreciation remained relatively steady at $33 million while administrative cost grew a mere $3 million to $171 million.
At end of June, Palace had cash funds of $141 million and quoted equity of $16 million, up from $100 million and $15 million respectively in 2016. Only $29 million is in borrowed funds while working capital stood at $122 million, a great improvement over the $76 million at June 2016.
The stock is listed on the Jamaica Stock Exchange and last traded at $550, earlier this year and now boast a price earnings ratio based on the above forecast of 11.

Profit jumps 69% at Main Event

Main Event should earn 50 cents per sahre for 2017.

Revenues at Main Event, rose 14.8 percent in the July quarter, to $290 million, compared to only 10 percent for the year to date to reach $942 million.
The strong growth in revenues coupled with reduction in cost in some areas resulted in a loss of $4.7 million in the 2016 quarter, transformed to a profit of $26 million in this year’s third quarter and $101 million for the nine months, versus $60 million in 2016, for a strong increase of 69 percent.
Revenues in the quarter to April was flat, at $319 million compared to the 2016 period, but contributed $25 million more profit than the July quarter. Direct operating cost as reported were $147 million in both quarters in 2017, as a result, gross profit margin in the July period was less than in April. In the July quarter, administrative cost ended at $92 million, the same as in the April quarter but depreciation rose to $22 million, from $16 million, as the company acquired more equipment for its own use rather than hiring them.
Assuming the growth level in revenues for the third quarter continues, the company seems heading for profit of 50 cents per share for the 2017 fiscal year to October and 70 cents for 2018, providing room for the stock to deliver a good return for investors who get in at the right price.

Three directors of Main Event, including the mentor who is respossible to ensure compliance with the JSE rules.

“We remain very confident in our strategies and the company’s prospects for further growth and new business opportunities,” the company’s Chairman, Ian Blair and CEO, Solomon Sharpe stated in their comments on the nine months results.
The balance sheet shows fixed assets growing to $420 million from $342 million at July 2016 and improved working capital of more than $100 million versus just $12 million in 2016, while borrowings have declined from $156 million to $122 million. With increasing profit, the finances should be looking better by year end and into 2018.
The stock is BUY RATED but closer to the $5 level currently and for a limited time, as it may not trade back down there.

The stock is listed on the Junior Market of the Jamaica Stock exchange and is trading at $5.60, just over a PE of 11 compared to 13.7 for the junior market.

Profit jumps 146% at SOS in Q2

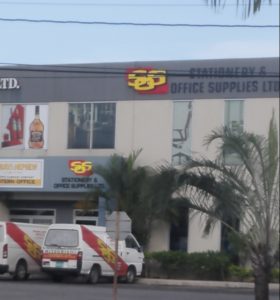
Stationery & Office Supplies Montego Bay office.

Profit jumped 146 percent at the recent Junior Market listing, Stationery & Office Supplies, to $20.3 million in the June quarter this year, before corporation tax of $8.8 million. For the six months period to June, profit before tax rose 33.4 percent to $50.4 million.
Revenues climbed 23.7 percent in the latest quarter to $212 million and 22 percent to $432 million for the six months. Gross profit climbed 25.5 percent to $99.5 million for the June quarter, flowing from increased gross profit margin while year to date, the increase was lower at 20.5 percent to $208 million. Expenses closed the June quarter at $79.2 million versus $71 million, an increase of 11.6 percent. For the year to date, the increase is a high 17 percent but still lower than the increase in revenues.
The 2017 result to date, is almost equal to the total 2016 results before tax of $53 million. Gross cash flow resulted in cash of $23 million being generated after an increase in working capital $28 million. The company spent $32 million on acquisition of fixed assets which required borrowing $4 and utilizing some cash on hand.
Businesses need adequate capital to grow and when debt reaches a certain level it becomes more challenging to access borrowed funding. Sometimes owners become concerned with increasing debt and this may hold back the performance of the business. Growth in the SOS’ business was putting pressure on cash resources resulting in borrowings rising, with $141 million outstanding at the end of June amounting to 50 percent of the equity. The need to expand to meet an increasing demand for its products would have placed added pressure on the owners to find the funds to finance the expansion.
The capital that came from the Issue of shares to the public will go a far way in improving the company’s finances and allow it to fund expansion, including paying for additional fixed assets which it was committed to at the time of the IPO.

Some team members at SOS who helped in the growth in prfoits for 2017

The Stationery and Office Supplies executive body that helped to grow profit in 2017

IC Insider.com’s observations are that listing on the stock exchange brings huge benefits to companies. The constant exposure results in increased business, the capital injection allows for increased focus on inventory selection and choices, all of which feed into increased sales. The increased pace of sales growth in the second quarter may well be connected with the publicity received prior to listing and it would be surprising if the pace of growth does not pick up in the second half of the year and well into 2018.
At a last traded price of $4.20 on the Junior Market of the Jamaica Stock Exchange, the stock remains a buy to benefit from future growth. IC Insider.com projects earnings before tax at 50 cents per share based on the average number of shares issued for the year, up from 40 cents when the shares were offered for sale and $1 for 2018 which is projected to continue to show strong growth in revenues. IC insider.com gathers that sales have picked up strongly after the IPO with many more walk in customers being seen than before. later in 2017, online marketing website and increased sales to the Eastern Caribbean will commence which should add to growth in sales going forward.
The company, under the stock exchange rules need not have put out the six months report, having been listed in August. The release is to be applauded. It is in the investing public’s interest, to have pertinent information on which they can make their investment decisions.

JMMB pretax profit up 16%

JMMB Group profits up 16% before tax to June.

JMMB Group posted a 16 percent increase in pretax profit, for the June 2017 quarter over 2016, but increased taxation left shareholders with a much smaller 4 percent increase to $617 million, as taxes climbed from $264 million to $381 million.
Net revenues jumped 19.4 percent to $4.1 billion from $3.44 billion in 2016, operating expenses rose even faster at 20.5 percent to $3.1 billion. Net interest income improved noticeably, moving from $1.55 to $1.9 billion as interest income grew to $1.96 billion, from $3.62 billion and cost fell modestly to $2.04 billion. Gains from securities trading rose to $1.54 billion from $1.1 billion but with revaluation of the Jamaican dollar, the group earned $238 million in the quarter, down from $443 million as the group also benefited from one off gains in 2016.
The Jamaican operations contributed 23 percent to growth in operating revenues, putting it at 75 percent of overall group revenues while Trinidad with its economic challenges, remained flat with just a one percent increase and Dominican Republic generated an increase of 18 percent.
Growth in managing pension funds, unit trust and money market funds, with assets under management moving from $89.5 billion in June 2016 to $114.75 billion helped in moving fee income up from $298 million to $364 million over the same period.
The group gained commercial banking license approval in Jamaica, in the September quarter, started to convert some branches to accommodate the new thrust and were also preparing for the roll out of their pension fund management in the Dominican Republic.
Total assets grew from $252 billion to $268 billion between March this year and June, shareholders’ equity moved from $25.9 billion to $26.8 billion including $2 billion in investment revaluation reserves at June this year, lending was almost static at $48 billion versus $47 at March. Investment in resale agreements stood at $173.8 billion versus March’s $172.5 billion. Customers’ deposits rose to $50.87 billion from $49 billion in March, while securities sold under repurchase agreements stood at $169.5 billion, up from $156.6 billion as of March, representing a fairly significant increase of $14 billion in just one quarter.
On Monday, JMMB Group closed at $21.50 on the Jamaica Stock Exchange and TT$1.20 (J$22.80) in Trinidad on Monday. IC Insider.com projects earnings of $3 for 2017 up from $2.03 as of March this year, putting the PE at 7 times the March 2018 earnings. The stock continues to be IC Insider.com BUY RATED.