Access Financial Q3 profit up 12%

Access Financial reports profit of $158 million in the December quarter, up 12 percent from $142 million in 2016, from trading revenues that grew 18 percent to $423 million from $358 million net of interest cost.
Net profit rose to $505 million, for the nine months over 2016, an increase of just $10.6 million, a mere 3 percent over the similar period in 2016, with provision for loan losses doubling.
Total trading income for the nine months to December, grew 23 percent to $1.22 billion, an increase of $225 million over 2016 and for the December quarter the increase was $65 million to $423 million from $358 million for an increase of 18 percent.
Loans income, rose $97 million or 10 percent to $1.04 billion for the nine months and by 21 percent to $379 million for the December quarter. Net fees and commission income jumped by 91 percent for the nine months to $270 million but by just 5 percent to $73 million in the December quarter.
Amounts set aside for loan losses increased just 12 percent in the quarter to $63 million and a sharp increase of 99 percent for the nine months, to $186 million, with the latter being well ahead of the increase in income for the period. Staff cost rose 24 percent for the December quarter to $99 million and by 42 percent to $277 million for the year to date period.

Access has a long history of consistent growth in income & profits

Total operating expenses for the nine months, increased by 33 percent to $698 million over 2016 and by just 10 percent to $238 million for the last quarter.
Total assets climbed to $3.43 billion at the end of December, from $2.96 billion in the prior year with the loan portfolio rising to $2.87 billion from $2.65 billion at the end of 2016 and $2.62 billion as of March 2017. Shareholders’ equity rose to just over $2 billion.
Earnings per share for the December quarter came in at 58 cents and for the year to date period to $1.84 and should end the full year around $2.60 for the full year for a PE of 17 times. IC Insider.com is forecasting earnings of $4.50 for the 2019 fiscal year for a PE of 10 times projected earnings. The stock last traded on the Junior Market of the Jamaica Stock Exchange at $45.15.

Profit jumps 49% at Salada Foods

Salada Foods profit jumped 49 percent to $27 million in the December quarter from just $18 million in 2016, from sales revenues that rose 17 percent to $228 million from $195 million in 2016.
Improvement in profit margin, helped in boosting profit for the quarter as gross profit climbed 34.5 percent to $84.47 million for the quarter from $62.79 million in 2016. Gross profit margin rose sharply from 32.15 percent to 37 percent for the quarter.
Operating expenses rose by 10.4 percent to $32.4 million in the quarter, while distribution cost fell from $13.6 million to $12 million.
Earnings per share came out at 26 cents for the current quarter from 17 cents for the 2016 period and should end around $1.20 for the fiscal year to September.
Gross cash flow brought in $42 million but after paying dividends of $52 million cash funds were reduced from $159 million at the end of December 2016 to $128 million and Investments of $254 million. Current assets stand at $765 million and current liabilities at just $155 million. Shareholders’ equity stands at $777 million with borrowings at just $11 million. Net current assets stands at $609 million.
The stock has a long history of volatility with the trend in profit being inconsistent. The company’s stock traded at $10.51 on the Jamaica Stock Exchange with a PE ratio of 9 times 2018 earnings.

Profit jumps 237% at Lasco Distributors


Lasco Distributors

Lasco Distributors profit jumped sharply in the December quarter by 237 percent to $127 million from just $38 million in 2016.
For the nine months period profit is up just 28 percent to $535 million form $417 million.
Sales revenues were down slightly for the quarter to $3.89 billion from $3.91 billion and was marginally higher for the year to date at $12.24 billion from $12.06 billion in 2016.
Improvement in profit margin along with a rise in other income to $50 million from $19 million in 2016, helped in boosting profit for the December quarter.
Gross profit climbed 21 percent to $676 million for the quarter and 18 percent for the nine months to $2.19 billion from $2 billion in 2016 as margins improved. Gross profit margin rose sharply to 17.4 percent from 14.3 percent for the quarter and for the year to date 17.9 percent from 16.6 percent for the 2016 period.
Operating expenses rose by 9.2 percent to $589 million in the quarter and by 8.3 percent in the nine months period to $1.67 billion.
Earnings per share came out at 4 cents for the quarter and 16 cents for the nine months period and should end around 20 cents for the fiscal year.

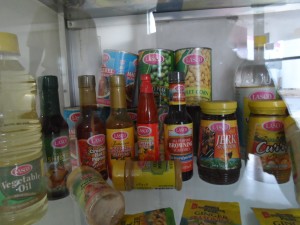
Lasco’s products

Gross cash flow brought in $600 million but growth in receivables and advances to related companies, resulted in a rise of just $30 million from operating activities. After paying dividends of $155 million cash funds were reduced from $1 billion at the end of December 2016 to $879 million. Shareholders’ equity stands at $8.1 billion with borrowings at just $215 million. Net current assets is $3 billion just a little below Payables of $3.2 billion.
The company rolled out new flavours in the instant Chocolate range and iCool brand in the quarter. In the coming months, Lasco will expand its product offers.
The stock traded at $3.91 on the Junior Market of the Jamaica Stock Exchange with a PE ratio of 19 times 2018 earnings. The company will go into a new year, come April, that should result in a lowering of the PE.

Wisynco profit up 23% for Q2

Wisynco profit rose 23% in the December quarter last year.

Wisynco recorded a 23 percent rise in profit after tax, for the December quarter of $578 million or 16 cents per share, compared to 13 cents per share for the corresponding quarter of 2016.
For the six months to December, net profit ended at $1.22 billion, up just 7 percent over the $1.15 billion earned in 2016 or 34 cents per share versus 32 cents for the corresponding period of 2016.
Revenues for the quarter of $6.14 billion, rose 14.5 percent over the $5.36 billion generated in the corresponding quarter of 2016. Six months’ revenues climbed 15.8 percent to $12.25 billion from $10.59 billion. Gross profit for the quarter rose much faster than revenues, for both the quarter and for the half year. The latest quarter recorded an increase of 26.3 percent, to $2.39 billion over $1.90 billion generated in 2016 and by 20 percent for the half year to $4.58 billion, compared to $3.5 billion, in the previous year.

Wisynco, producers of Wata..

Gross profit margin improved to 39 percent for the quarter compared to 35.3 percent for corresponding quarter of the previous year. For the 6 months ended December, gross profit margin was ahead by 1.4 percent of 2016 to 37.4 percent.
Selling, Distribution and Administrative Expenses for the quarter totaled $1.54 billion or 15.7 percent more than the $1.33 billion for the corresponding quarter of the prior year. “Expenses for the quarter included $26 million of costs related to the May 2016 fire and $71 million for the year to date, and the Directors feel these should be fully behind us by the middle of the 4th Quarter” the directors reports stated.

Selling and distribution expenses rose 13 percent to $2.6 billion for the six months while Administration cost climbed sharply to $235 billion from $134 million for the December quarter and for the six months, cost rose to $312 from $255 million in 2016.
Finance Costs for the quarter rose to $133 million from $31 million in 2016 and for the six months, finance cost moved from $74 million, to $145 million. According to the directors report to shareholders part of the increase “is a loss on the revaluation of our US dollar deposits of approximately $79 million due to the Jamaican dollar revaluation to a quarter end rate of 125, at the end of December 2017.”

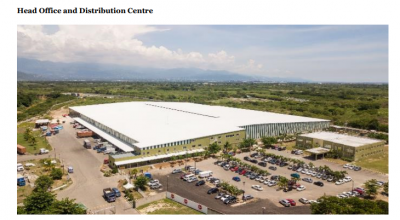
Wisynco operates at two main locations situated in St. Catherine: White Marl and Lakes Pen.

The directors reported that, “the quarter in question saw some challenges even as we recorded fairly good growth in top line revenue. We had some of the highest level of rainfall in many years during the quarter which does not auger well for our customers’ businesses as well as beverage sales generally. The construction of our cold storage facilities has also been delayed slightly due to the rains and this would have impacted on our chilled and frozen business. We now expect our cold storage facility to be complete during the 4th quarter which will result in improved distribution and cost synergies. During the quarter we continued to look at ways to reduce sugar intake for consumers through initiatives such as reducing portion sizes in our full sugar products as well as reduced sugar formulas for our beverage portfolio.”
At the end of the year current assets stood at $7.9 billion with cash funds of $3.3 billion, against current liabilities of $2.9 billion. Borrowings amounted to $2.8 billion with equity capital of $7.8 billion that reflects the sale of shares to the public in December that brought in $1.1 billion and after paying dividend of just over $1 billion.
Based on the results for the quarter and half the company is on target to deliver earnings around 70 cents for share for the full year. The stock last traded at $10.55 on the Jamaica Stock Exchange for a PE of 15, for the 2019 fiscal year IC Insider.com is forecasting $1.10 per share in earnings for a PE of 10.

Big payday for Ciboney’s shareholders

Ciboney Group‘s shareholders are in for a treat with a capital distribution of 34 cents per share to be paid in March. The funds come from cash generated from the sale of land previously owned by the company.
Having struggled for years with operating losses, resulting from poor management decisions a sizable portion of their asset was wiped out as they ploughed through cash funds which stood at $41 million in 2011. By November last year cash held was less than $1 million.
The sale of property located in Westmoreland netted $226 million resulted in the net value moving from a negative value of $50 million to a positive position of $132 million. The distribution will cost $185 million.
The distribution will be paid on March 9 to shareholders on record at the close of business on February 16. The company’s next Annual General Meeting will be held on April 10 at which, to have this ratified. No doubt the future of the company will take up quite a bit of time at that meeting. After the stock starts trading, excluding the right to the distribution the price should fall back sharply, thereafter it will depend on what future the company could have.
For the six months to November, Ciboney reported a loss of $2.55 million and for the fiscal year to May a loss of $5.2 million was incurred after taxation charge of $180,000.

Lasco Financial beats 2017 profit in 9 months

Lasco Financial reports profit for 9 months at $222 million.

Lasco Financial’s profit for the nine months to December, has already eclipsed the full 2017 fiscal year profit of $188 million as nine months profit climbed 36.6 percent to $222 million, from a 35 percent revenue increase from $830 million to $1.12 billion.
Profit after tax, suffered a decline in the third quarter, falling to $54.7 million from $62 million in 2016, as revenues increased by 36 percent to $405 million from $298 million in the 2016 period. The results reflect just one month’s of CrediScotia’s operation.
Responding to the growth in the December quarter results, Lasco’s Managing director, Jacinth Hall-Tracey stated in her report to shareholders, “This is attributed to seasonally strong remittance and cambio inflows bolstered by the income from its new acquisition of CreditScotia, renamed LASCO Microfinance. After recognizing some direct expenses for the acquisition and normal seasonal operational increases, profit from operations for the quarter closed at $91.4 million, an increase of 18.5 percent.” Interest cost associated with the funding of the acquisition was pushed up by $20 million in the quarter and reduced the positive gains in operating profit below pretax profit in 2016 of $75 million to $69 million.
Administrative and other expenses, jumped a sharp 63 percent to $179 million in the third quarter, but for the nine months, it rose by a more moderate 41 percent, to $531 million, well ahead of the increased revenues. Marketing cost rose 22 percent in the quarter to $135 million and 20 percent for the nine months, to $389 million.
Total assets jumped from $1.55 billion at the end of March 2017 to $3.3 billion with the acquisition of the CrediScotia shares, funded by $1.27 billion from by short-term loans, from related companies. The short-term loans will be repaid in full from a long term instrument being arranged.

Access Financial has assets of $3.3 billion at September 2017.

The acquisition pushed Lasco’s assets to the same amount that Access Financial had at the end of September. There are two differences, Access Financial is valued by the stock market at twice the market value of Lasco’s market value of $6.6 billion, with Access at $11.55 billion. Access’s loan portfolio stood at $2.68 billion at September while Lasco is less than $1.5 billion at the end of December last year.
According to the quarterly report, in the coming months, the loan business will be combined into the subsidiary company. The combined businesses own a network of 13 branches, a large customer base and a billion dollar loan portfolio.
The company looks like it will end 2018 fiscal year with profits around $300 million level with earnings per share of 25 cents. The stock last traded on the Junior Market of the Stock Exchange at$5.24 at a PE around 20 times current fiscal year’s earning, but the focus will be on the next fiscal year when the full benefits of the acquisition of the CrediScotia is fully reflected in the results and one off cost are removed.

Republic Financial reports more profit

Republic Bank pretax profit rise 8% in Q1.

Trinidad’s Republic Financial Holdings reported net profit of $340 million for the quarter ended December 2017. Profit after tax increased a mere 3 percent or $10 million over 2016.
Revenues net of interest cost rose 13 percent to $560 million from $496 million in 2016 and profit before tax rose 8 percent to $508 million, but increase taxation in the quarter reduced the net results.
According to the directors, the improved results came from better performance in the overseas territories while results in Trinidad and Tobago declined due to a $34 million increase in loan loss provision.
Segment results were mixed with Trinidad and Tobago contributing flat results of $1.08 billion. Barbados rose from $55 million to $102 million. Guyana fell from $39 million to $34 million. Cayman, Suriname and the Eastern Caribbean continues contributed $55 million versus $40 million in 2016 and Ghana jumped from just $724,000 to $31 million.
The performance also benefitted by a reduction in operating expenses that fell from $698 million to $667 million.
Loans net of loan loss provisions, grew 6 percent to $37 billion from $34.8 billion in 2016 and from $35.5 billion at the end of September 2017. Republic closed on the Trinidad Stock Exchange at $101.50 on Thursday with a PE ratio of 12.
All figures are in TT$

NCB reports 28% profit growth but..

NCB Financial Group reported net profit of $4.6 billion for the quarter ended December 2017 and hiked their dividend. Profit increased 28 percent or $1 billion over 2016. Revenues net of interest cost rose 17 percent to $16.7 billion from $14.2 billion in 2016.
On the surface the gains in profit sounds great, but closer examination reveals that $1.5 billion comes from a one off gain resulting from the acquisition of majority shares in Clarien. The group incurred cost associated with staff separation that help swell staff cost to $5.9 billion from $3.75 billion in 2016 while Policyholders’ and annuitants’ benefits and reserves rose from $1.03 billion in the first quarter of 2016 to $1.78 billion.
Return on average equity increased to 15.7 percent from 14.0 percent in 2016. Net loans grew 63 percent to $322.4 billion from $197.9 billion and from $218.6 billion at the end of September 2017. Growth was due to the consolidation of Clarien Group, accounting for $93 billion and increases in retail loan portfolio
Segment results were mixed with consumer and small and medium enterprise Retail and SME being worse off in 2017 than 2016 by $290 million and Payment Services for the sector increasing profit by $325 million to $1.2 billion. Corporate banking enjoyed lower operating profit of $95 million leading to $710 million in the quarter, Treasury & Correspondent Banking was virtually flat at $1.6 billion. Wealth, Asset Management and Investment Banking grew strongly by $440 million to $1.2 billion, Life and Pensions had strong growth of $438 million to $1.3 billion but general Insurance was $536 million worse off in ending with a loss of $108 million.
NCB hiked interim dividend to 70 cents per share up from 60 cents in 2017. The dividend is payable on February 26, for stockholders on record as at February 9, 2018.
NCB Financial, closed at J$100.85 trading 59,911 shares on the Jamaica Stock Exchange and TT$6.60 ($J$123) trading 261,082 shares, on the Trinidad and Tobago Exchange on Thursday.

CAC 2000 profit rise but

CAC2000 the air condition engineering company, reported improved profits for the year to October 2017, after accounting for a provision of $104 million for court judgement claim in the 2016 results.
Profit excluding the amount of the claim fell slightly to $100.5 million in 2017 from $115 million in 2016. Revenues rose 19 percent to $1.2 billion. The situation would have been worse but for a $20 million swing around in bad debts which reduced cost in 2017 by $9.8 million compared to cost of a similar amount in 2016.. Operating cash flows before movements in working capital brought in $121 million up from $49 million in 2016.
Even as revenues climbed strongly, gross profit hardly moved rising to $424 million from $410 million in 2016 as direct cost rose faster than revenues with an increase of 29.5 percent to $786 million.
Directors’ remuneration climbed 25 percent to $41.2 million from $32.5 million, well ahead of the 5 percent increase in staff cost to $116.3 million for the year. Legal and professional fees jumped 47 percent, to $33 million.
Earnings per share ended the year at 78 cents, the stock traded at $7.50 on Friday, before the close of the market. Borrowings ended the fiscal year at $260 million up from $165 million at the end of the 2016 fiscal year, shareholders’ equity rose to $423 million from $322 million in 2016. Cash funds stands at $192 million even as trade receivables climbed $180 million to $536 million but inventories fell $80 million to $209 million.

.

Profit surge 79% at Main Event

Main Event was the 4th best performing Junior Market stock for 2017.

A 15.6 percent decline in revenues in Main Event’s October quarter, pulled a 10 percent increase in the year to July, down to just 3.9 percent for fiscal year, but that was enough to spark a big jump in profit for the year.
The improvement in the topline, was sufficient to deliver a strong 79 percent increase in profit for the year, to reach $101 million after tax, up from $56.5 million, as the company made profit in the last half compared to a loss in 2016. For the final quarter, in spite of the reduction in revenues to $234 million versus $277 million in 2016, a small profit of $7 million was achieved versus a break even position in 2016.
Cash flow from operation provided $188 million up from $118 million in 2016, but the company purchased fixed assets of $137 million and reduced net liabilities having received proceeds from the issue of shares amounting to $103 million.
Importantly, direct cost fell by $94 million for the year compared to 2016, but administrative and depreciation cost rose by the same amount. With the rise in revenues, gross profit margin improved leading to a strong increase profit for the year. Some of the improved gross profit seemed to have been achieved by cost ending in administrative and depreciation expenses.
The company’s working capital has improved over 2016 with current assets at $292 million compared to current liabilities of $184 million, in 2016 it was $186 million to $212 million. Equity capital is up to $446 million from $242 million in 2016 while borrowings are down to $170 million versus $204 million, with cash funds of $91 million.
Earnings per share adjusted for tax is 38 cents and IC Insider.com projects 55 cents for 2018.
The stock traded at $5.80 on the Junior Market of the Jamaica Stock Exchange at the close on Thursday for a PE ratio of 11.
The nature of the business exposes it to possible swings in revenues some of it being weather related and others based on the timing of major entertainment events. The effect of such movements suggest that investors may be best rewarded based on a longer term investment posture to benefit from positive surprises in increased business.