Growth surges at Omni Industries


Following the third quarter jump of 37 percent, revenue surged 50 percent to $616 million in the December quarter at Omni Industries. The surge was driven primarily by construction products, which accounted for 57 percent of total sales and delivered a solid turnaround in profits for the 2025 fourth quarter, with a profit of $28 million, compared with a loss of $25 million in the final quarter of 2024. Earnings per share jumped from a loss of 10 cents in 2024 to 11 cents.
For the 2025 fiscal year, revenues climbed a respectable 14 percent to $2.22 billion, up from $1.95 billion in 2024, with profit increasing a solid 34 percent to $170 million over the $127 million in 2024. Earnings per share amount to 6.8 cents and 5.3 cents in 2024.  

This significant growth in the fourth quarter reflects heightened demand following Hurricane Melissa, as customers accelerated procurement of essential construction and storage materials, Management stated in the report to shareholders. This raises the question about the level of sustainability of increased sales, particularly the increase in the December quarter over and above the third quarter.

The quarterly gross profit margin amounts to 39.3 percent, up from 37.7 percent in the prior year and ended with gross profit of $242 million, a 57 percent improvement over the $154 million in 2024, outpacing revenue growth.

The year-to-date gross margin dropped from 44.8 percent to 40.1 percent, reflecting higher input costs as the company sourced raw materials from non-traditional suppliers to navigate global trade tensions and supply chain disruptions. Notably, operating expenses remained flat year-over-year at $719 million.
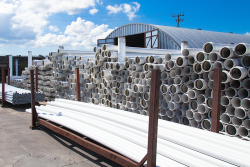
The operations generated $220 million in cash flows and $171 million after changes in working capital, but $219 million went into Property, Plant and Equipment that expanded by 37 percent to $603 million, from $441 million in 2024.

Shareholders’ equity increased to $1.097 billion from $927 million in 2024.  Long-term loans increased from $207 million to $272 million. Current assets amount to $1.25 billion, up slightly over the end of 2024, while current liabilities ended at $484 million, down from $526 million at the end of the previous year.

ICInsider.com projects 12 cents in earnings per share for 2026. Growth in revenues in the December quarter, if sustained, could drive revenues and profits higher than projected. At a current price of $0.98, the current PE is 8.2 versus the market average of 14.2, leaving room for growth in the stock price.
50% jump in profit at Wisynco


Profit jumped 50 percent after tax for Wisynco Group for the December quarter to $1.5 billion, compared to $1 billion in 2024, with earnings per share of 39 cents compared to 26 cents in the December 2024 quarter. The solid profit performance was firmly grounded on a 14 percent revenue bounce to $16.2 billion, from $14.2 billion in the group’s 2024 second quarter and up a mere 2 percent for the first quarter revenues.

Wisynco Q2 profits jump 50%.

Revenues for the half year rose by a slower 12.2 percent pace than the second quarter, to $32.4 billion, from $28.9 billion in 2024, while profit after tax rose by just 19 percent to $2.96 billion from $2.49 billion. “The sustained improvement in sales is a result of our significant capital outlay in production capacity, therefore being able to meet demand and the introduction of new product lines, including our new brewed products and an improvement of 14 percent in our exports. We formally launched our brewed product at the start of Q2 and the response to the products that have been placed on the market has been encouraging,“ Andrew and William Mahfood stated in their report to investors.

Gross Profits jumped 26.7 percent over the prior year second quarter to $5.9 billion from $4.7 billion of the prior year, whilst gross margins climbed to 36.6 percent up from 32.9 percent for the same quarter last year.  For the half year gross profit climbed 15.4 percent to $11.56 billion from $10 billion in 2025 with gross profit margins of 35.72 versus 34.72 in 2025.

Wata one of Wisynco best known brands

Selling and Distribution expenses rose 7.7 percent during the second quarter to $3.47 billion from $2.95 in 2024 and climbed 10.5 percent for the six months to $20.8 billion from $18.8 billion in 2024. Administrative expenses for the quarter amount to $631 million, 10.4 percent more than the $571 million for the 2024 quarter. It rose 2.8 percent to $1.2 billion for the six months from $1.18 billion in 2024. Finance costs jumped from $115 million to $245 million in the latest quarter and rose from $118 million to $401 million in the six months. Finance expenses were partially offset by finance income of $139 million in the 2025 first quarter, up from $119 million in 2024 and for the half year, $291 million up from $245 million.

The operations generated Gross cash flow of $4.7 million, growth mainly in receivables, inventories, addition to fixed assets and investment in associated companies of $2.45 billion, offset by proceeds from investments and funding the payment of $866 million dividends, resulted in a $2 billion outflow of funds, reducing Cash and Cash Equivalents to $5.2 billion, at the end of the period.
Current assets ended the period at $21.4 billion, including trade and other receivables of $6.9 million, cash, bank balances and investment securities of $10.3 billion.
Current liabilities ended the period at $8.6 billion and net current assets at $12.7 billion.
At the end of December, shareholders’ equity amounts to $30.6 billion with long term borrowings at $5.9 billion and short term at $955 million.

ICInsider.com computation projects earnings of $1.80 per share for the fiscal year ending June 2026, with a PE of 13 times the current year’s earnings based on the last traded price of $23.62 on the Jamaica Stock Exchange Main Market. Net asset value is $8.17, with the stock selling at a premium of 2.77 times book value, well above the average for Main Market companies.  The company declared a dividend of 23 cents payable of March 4 versus a similar amount in April 2025.

Woodcats International heading to the JSE Junior Market


Woodcats International, manufacturer of wooden pallets and related products, in Jamaica, along with the majority owner are offering to the public by way of an Initial Public Offering (IPO) up to 833.33 million ordinary shares at J$0.90 per share, that will raise J$750 million, if fully taken up and is expected to list on the Jamaica Stock Exchange Junior Market, that will permit them to enjoy 10 year period of tax reduction.

Founded in 1999, the company was acquired by Derrimon Trading Company in 2018, and grown appreciably, with net profit increasing more than sevenfold over five years while doubling revenues to J$1.08 billion in 2024. Interim results show a much slower growth of just 3.8 percent to $840 million, slightly better than the 3.2 percent increase enjoyed in 2024.
The PE ratio at the IPO price of 90 cents is just 11.5, based on the latest profit results, which is below the Junior Market average of over 13, with several stocks priced around 18. ICInsider.com projects a rise in the price following the IPO and listing on the junior Market of the Jamaica Stock Exchange.
The issue opens on February 2, 2026 and is scheduled to close on February 20,
The board of directors comprises. Earl Anthony Richards, Derrick Cotterell, Ian Kelly, Patrick Mignott, Nicole Burgher, Jermaine Burrell, Carlton Samuels.
The Company effected cost controlled measures with a 6.2 percent reduction in cost despite inflationary pressures. This reduction was achieved while expanding operations, highlighting operational efficiency. Finance costs increased due to higher lease interest expense from additional warehouse space to facilitate growth.
Current Assets amount to $479 million as of September 2025, compared to $490 million in 2024.
Cash and cash equivalents ended the period at $55 million, compared with $59 million in 2024. The company also hold investments amounting to $108 million, including 30 million Derrimon Trading Company shares with a market value of $60 million. Shareholders’ equity stands at $633 million, with non-current liabilities at $144 million, while current liabilities sit at $124 million.

PROSPECTS FOR 2026
Woodcats seems positioned for continued growth with a three-to-five year plan targeting 20 percent compound annual revenue growth through 2028. Actual outcomes can vary from plans. Key strategic initiatives include expanding certified heat treatment capacity by 50 percent within three years, launching composite wood-plastic pallets by Q4 2026, increasing pallet production output by 30 percent by 2027, and growing the Summerland retail brand with five distribution points across Jamaica and CARICOM by 2027. The Company aims to diversify revenue streams with ancillary sales contributing 20 percent of total revenue by 2028, while establishing Woodcats as the recognised regional hub for sustainable pallet solutions with entry into two new CARICOM markets by 2026. Process automation targeting 40 percent of production by 2026 is expected to reduce production time per pallet by 20 percent, supported by full adoption of digital supply chain management tools by 2027.

NCB Capital Markets is the broker for the issue.

Concerns over WI Petroleum 1,300% Rally


West Indies Petroleum Terminal closed trading on Friday at $7.25 per share, capping a remarkable 1,300% surge since its December 23 debut at $0.50. The spectacular gains resulted in the stock trading at valuation levels that defy conventional metrics, with a huge decline clearly on the cards.

At Friday’s close, WIPT trades at 244 times 2024 earnings, according to data compiled by ICInsider.com, after eliminating the one off impairment cost mentioned below, a stark contrast to the broader Jamaica Stock Exchange with an average PE of 18 times earnings. The company was initially valued at roughly 11 times earnings at listing.
The rally reflects scarcity more than fundamentals. WIPT was listed by introduction, with no new shares issued, resulting in a minimal float, fuelling speculative demand.

The company has not released any results for 2025, but profitability remains modest, with net profit of just US$1.04 million on revenue of US$8.21 million for 2025, a 51.9% earnings decline from 2023. The results for 2024 were driven by higher finance costs and a US$1.04 million impairment charge, which is not expected to repeat.

The extreme valuation disconnect suggests investors are pricing in dramatic earnings growth that has yet to materialise. Management has signed third-party storage agreements with Musket Corp, TotalEnergies, and Sunoco to supply fuel across Jamaica, which diversifies revenue, but the path to justifying a 244x multiple remains unclear.

For value investors, the math is sobering: at $7.25, the market is betting WIPT will transform from a US$2 million profit company into something vastly larger, in the order of 17 times, amounting to a profit of US$34 million that is not going to happen.

WI Petroleum reporting slackness


West Indies Petroleum Terminal Limited (WIPT) was listed on the Jamaica Stock Exchange in December, with the last financial statements up to December 2024. In a release to the stock exchange, the company indicates that it will exercise the option to submit its unaudited financial statements for the fourth quarter ending December 31, 2025 and its audited financial statements within 90 days of its year end.

There is something completely wrong with this listing. The stock is currently trading at a PE of 51 based on 2024 earnings adjusted for a one off expense, with very little supply coming on the market. Since listing, only 16,003 shares have traded to date, with the stock in heavy buying demand.
WIPT is the only company currently listed with no financial report after more than a year since the last report. Investors are trading blindly, with only old information available to use to assess the company.

The Jamaica Stock Exchange and the Financial Security Commission have a responsibility to the public to ensure investors have up to date information to base their trading on. It cannot be right for a company to list so late in the year, without releasing interim results. For the company to now state that they are going to release interim figures in 90 days of the 2025 last quarter is not acceptable when the requirement is 45 days.

The stock exchange cannot have two rules for companies listing by invitation and those listing through an IPO when it comes to financial data. An IPO has to report up to date financials no more than a few months old so why was WIPT allowed to list with 12 months old financials?
The company’s management would do itself and the company a great deal of good by immediately releasing the interim results for the March, June and September quarters and releasing the December quarterly results within 45 days, as is the JSE requirement.
The above and other grave unresolved issues in the stock market call for action to protect investors, not just a few.

Profits climb at NCB Group


Jamaica’s largest financial conglomerate, NCB Financial Group, reported profits for the fiscal year to September of $23 billion, attributable to shareholders of the Group or $9.59 per share, with profit of $4.2 billion or $1.73 per share for the September quarter compared with a loss of $330 million in 2024.

The group benefited from a $15 billion one-time gain on the sale of a subsidiary; excluding this, earnings would have been just $13 billion for the year, compared to $13.3 billion generated in 2024 and earnings per share from continuing operations would be $7.60, up from $5.62 in 2024.
The group declared a dividend of 50 cents per share, which will be paid in December and will bring the full year to $2.per share.

The stock is severely undervalued, with a PE ratio of only 5.2 times 2025 earnings and even less based on 2026 earnings, which ICInsider.com projects to rise. The stock, which now trades around $40 each, trades well below the net asset value of $77. Holding back the group is the stagnation in lending, with loans falling to $618 billion from $626 billion in 2024.
NCB is accorded the ICInsider.com BUY RATED award.

Profit inches up at Scotia Group


Profit declined 7.3 percent to S5 billion at Scotia Group for the April 2025 quarter, compared to $5.4 billion in the similar period last year, as total operating revenues rose by a billion dollars to $15.6 billion from $14.6 billion in the comparable quarter in 2024.

Profit grew 7.8 percent to $9.2 billion after tax for the six months to April, over the previous year. A drop in loan loss provisions to $651 million in the latest quarter from $1 billion in the 2024 second quarter and $1 billion for the half year, down from $1.25 billion in 2024, helped to boost the group’s profit performance.
Operating expenses grew faster than revenues, climbing 23 percent, with an increase of $1.5 billion to $8.3 billion, wiping out the increase in operating income in the second quarter. Corporation taxes amounted to $2.3 billion in the quarter, compared to $2.4 billion in the prior year.

Total operating revenues for the six months ended April 2025, net of expected credit losses, grew by 9.5 percent, or $2.9 billion, to $33.4 billion from $30.5 billion in 2024. This was primarily driven by the growth in loans, which led to an increase in net interest income of $1.9 billion, or 8.5 percent, and an increase in other revenue of 13 percent.

The Group’s asset base grew by $87 billion or 12.9 percent to $764 billion as at April 2025, with loans increasing 14.7 percent to $324 billion. Since the October close of the 2024 fiscal year, loans only grew in the second quarter, at 15 percent per annum, much slower than the 16.3 percent increase in the 2024 fiscal year.

According to the Group, “loan book continues to perform well with mortgages increasing year over year by 24 percent, consumer loans by 14 percent, credit cards by 8 percent and commercial loans by 7 percent.” Deposits, an important fuel for funding loans and investments, increased 10 percent to $514 billion from $467 billion a year ago.

Scotia Group declared a dividend of 45 cents to be paid on July 17, bringing the half-year payment to 90 cents, up from 80 cents for the similar 2024 period.
Earnings per share for the April quarter amount to $1.61 and $2.96 for the half year. ICInsider.com projects earnings of $8.20 for the year ending October 2025.
The stock is ICInsider.com BUY RATED. At the last traded price of $54.91, the stock trades at an attractive PE of 6.7, well below the market average of more than 13. Most importantly, the critical aspect of the business is lending, and the ability to generate reasonable yearly increases in amounts lent out, thus driving revenue growth.

The present state of the Jamaican economy, including lower debt-to-GDP, which allows for greater fiscal space that will facilitate continued lower interest rates, should result in growth in earnings for years to come. With that, investors can look forward to increased dividend payments and stock price appreciation.

Profit surges at Jamaica Stock Exchange


Profit at the Jamaica Stock Exchange jumped a sharp 155.5 percent in the March 2025 first quarter, to $236 million after corporate Tax, up from just $93 million in 2024.

Expenses increased 12.4 percent over 2024, to $554 from $493 million in 2024, the increase was much less than the 36 percent growth in revenues of $861 million, up from $634 million in 2024, growth was driven by improved market conditions and heightened market activity, leading to a substantial 245.7 percent rise in income form Cess of $256 million over, just $74 million in 2024.
Earnings per share amount to 34 cents, up from 13 cents last year and compare well with full year earnings last year of 71 cents. Based on these results, the company is on target for earnings in the $1.60 region, with a PE of 8 based on the last traded price of $12.75 and placing it on the ICInsider.com coveted Buy Rated accolade.

Equity capital stands at $3 billion and cash and investments amount to more than $1 billion.

With interest rates much lower this year than last year, more funds should flow into stocks and boost the existing income levels of the exchange. In addition, more companies are expected to be listed in 2025 and future years and existing companies are raising more equity capital, all of which should boost revenues for the exchange in the years ahead. The future looks very promising for investors in this stock in the years ahead.

Big income gains drive Transjamaican profit


Profit at Transjamaican Highway jumped a solid 33 percent before tax for the quarter ending March this year, to US$12.1 million, from US$9.1 million for the same period in 2024. The strong performance was largely driven by increased revenues of US$22.5 million, up 14 percent over the US$19.8 million recorded in the March quarter of 2024.

Profit after the provision for taxation of US$3 million for the quarter amounts to US$9.1 million, an increase of 32 percent over the net profit of US$6.9 million for the 2024 first quarter.
Although profit after tax was $9 billion, cash generated from operating activities amounted to a healthy $15 billion.
Earnings per share rose to US$0.0007, with ICInsider.com forecasting J$0.52 per share for the full year and putting the PE of the stock at an attractive 7 times the current year’s earnings, compared to 13.3 for the market average.
The company paid an interim dividend of J$0.1258 in April this year. A second dividend payment is expected later in the year, which should take the full year amount to 25 cents, with a dividend yield of nearly 7 percent. Most importantly, according to the prospectus issued in 2020, the dividend payment as a percent of profit ranges from 43 percent in the earlier years up to 2025, to a high of 85 percent, from 2026 to 2034. If the company adheres to this projection, dividends should double next year, and so should the stock price, all things being equal.

With these results and prospects for continued increased revenues, profit and good dividend payments, Transjamaican Highway is crowned an ICInsider.com BUYRATED stock.

Omni Industries revised audited accounts


Audited financial statements for 2024 of Omni Industries have now been corrected following ICInsider.com’s highlighting of an overstatement of earnings per share arising from an error in the computation of the average number of shares issued in 2024.

Neither the company nor its auditors originally, properly accounted for the increased number of shares arising from a stock split of the issued shares in early 2024.
The revised audited account, posted to the Jamaica Stock Exchange website this morning, shows the revised earnings per share for 2024 and has corrected for the omission of earnings per share for 2023.
The report now shows the average number of shares is just over 2.389 billion units with earnings per share of 5 cents, with 7 cents for 2023 from 2.25 billion shares.
Omni generated revenues of $1.923 billion in 2024, a 6 percent decline from $2.039 billion in 2023. Profit after taxation declined by 16 percent to $127 million from $151 million in 2023.
The company reported an improved gross profit margin of 33.1 percent, up from 29.5 percent in 2023. A sharp 31 percent jump in administrative and selling expenses to 483 million from $368 million eroded by benefit from improvement in the gross profit.
The company now needs to post corrected accounts for all the interim reports for 2024 that were based on the incorrect number of shares and, therefore, overstated earnings per share.
The stock that traded at $1 on Friday collapsed to 75 cents on Monday, with trading in the stock suspended after triggering the circuit breaker.