Profit inches up at Scotia Group


Profit declined 7.3 percent to S5 billion at Scotia Group for the April 2025 quarter, compared to $5.4 billion in the similar period last year, as total operating revenues rose by a billion dollars to $15.6 billion from $14.6 billion in the comparable quarter in 2024.
Profit grew 7.8 percent to $9.2 billion after tax for the six months to April, over the previous year. A drop in loan loss provisions to $651 million in the latest quarter from $1 billion in the 2024 second quarter and $1 billion for the half year, down from $1.25 billion in 2024, helped to boost the group’s profit performance.

Operating expenses grew faster than revenues, climbing 23 percent, with an increase of $1.5 billion to $8.3 billion, wiping out the increase in operating income in the second quarter. Corporation taxes amounted to $2.3 billion in the quarter, compared to $2.4 billion in the prior year.

Total operating revenues for the six months ended April 2025, net of expected credit losses, grew by 9.5 percent, or $2.9 billion, to $33.4 billion from $30.5 billion in 2024. This was primarily driven by the growth in loans, which led to an increase in net interest income of $1.9 billion, or 8.5 percent, and an increase in other revenue of 13 percent.

The Group’s asset base grew by $87 billion or 12.9 percent to $764 billion as at April 2025, with loans increasing 14.7 percent to $324 billion. Since the October close of the 2024 fiscal year, loans only grew in the second quarter, at 15 percent per annum, much slower than the 16.3 percent increase in the 2024 fiscal year.
According to the Group, “loan book continues to perform well with mortgages increasing year over year by 24 percent, consumer loans by 14 percent, credit cards by 8 percent and commercial loans by 7 percent.” Deposits, an important fuel for funding loans and investments, increased 10 percent to $514 billion from $467 billion a year ago.

Scotia Group declared a dividend of 45 cents to be paid on July 17, bringing the half-year payment to 90 cents, up from 80 cents for the similar 2024 period.
Earnings per share for the April quarter amount to $1.61 and $2.96 for the half year. ICInsider.com projects earnings of $8.20 for the year ending October 2025.
The stock is ICInsider.com BUY RATED. At the last traded price of $54.91, the stock trades at an attractive PE of 6.7, well below the market average of more than 13. Most importantly, the critical aspect of the business is lending, and the ability to generate reasonable yearly increases in amounts lent out, thus driving revenue growth.

The present state of the Jamaican economy, including lower debt-to-GDP, which allows for greater fiscal space that will facilitate continued lower interest rates, should result in growth in earnings for years to come. With that, investors can look forward to increased dividend payments and stock price appreciation.

Profit surges at Jamaica Stock Exchange


Profit at the Jamaica Stock Exchange jumped a sharp 155.5 percent in the March 2025 first quarter, to $236 million after corporate Tax, up from just $93 million in 2024.

Expenses increased 12.4 percent over 2024, to $554 from $493 million in 2024, the increase was much less than the 36 percent growth in revenues of $861 million, up from $634 million in 2024, growth was driven by improved market conditions and heightened market activity, leading to a substantial 245.7 percent rise in income form Cess of $256 million over, just $74 million in 2024.
Earnings per share amount to 34 cents, up from 13 cents last year and compare well with full year earnings last year of 71 cents. Based on these results, the company is on target for earnings in the $1.60 region, with a PE of 8 based on the last traded price of $12.75 and placing it on the ICInsider.com coveted Buy Rated accolade.

Equity capital stands at $3 billion and cash and investments amount to more than $1 billion.

With interest rates much lower this year than last year, more funds should flow into stocks and boost the existing income levels of the exchange. In addition, more companies are expected to be listed in 2025 and future years and existing companies are raising more equity capital, all of which should boost revenues for the exchange in the years ahead. The future looks very promising for investors in this stock in the years ahead.

Profits continue to send mixed signals

Early profit results for the first 2024 quarter show some positives, with the Montego Bay-based Knutsford Express reporting b revenue growth and profit for the quarter and the nine months to February, followed by positive results for AMG Packaging and Express Catering, but there were also some disappointing ones.

Knutsford Express

The directors of Knutsford Express stated that “strong and steady demand for our courier services complemented our passenger services have combined in delivering year to date profit of $268 million, up 27.1 percent from $211 million at the end of February 2023. We, therefore, recorded a 20.9 percent growth in our total revenue in this quarter moving to $565 million from $468 million in the comparative period in 2023. Similarly, our nine-month year-to-date revenue has increased by 19.5 percent from $1,281 million in 2023 to $1,530 million in 2024.”
Innovative Energy, formerly Ciboney reported no revenues in the February quarter and a loss of $4.4 million with the year to date, ending with $500,000 in income and a loss of $7.8 million.
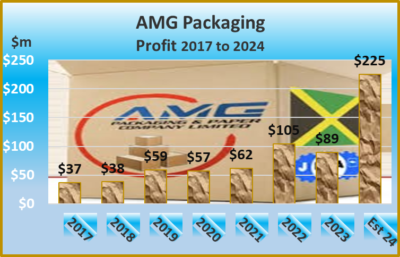
AMG Packaging grew profit by 79 percent to $32 million from $18 million in 2023, better than the 72 percent rise in the first quarter. For the six months to February, profit was up by 79 percent to $84 million from $47 million in 2023.
Revenues climbed from US$6 million to US$7 million at Express Catering, up 17.6 percent in the quarter and increased by 23 percent from US$15 million to US$18.7 million, delivering a profit of US$2 million for the year to date and US$1 million for the latest quarter, compared with US$1.9 million for the nine months in 2023 and $1.15 million in the February 2023 quarter. Ian Dear, the company’s CEO confirmed that added cost in the third quarter would have been associated with new restaurants opened close to the quarter as such, some of the cost would not be fully covered by revenues.
The revenue at Margaritaville (Turks) rose just 5 percent to US$5.25 million for the current year, compared to US$4.98 million for the same period last year, with a net profit of US$521,909, earnings per share of 0.773 US cents compared with the similar period of 2023, with a net profit of US$1.18 million which includes non-recurring gains of US$658,000 for EPS of 1.749 US cents.
For the third quarter, revenues fell to US$1.9 million from US$2.2 million in 2023, delivering a profit of US$222,174 versus US$725,000 in 2023 including one time income of US$340,000.
Sygnus Real Estate Finance fell by 43 percent in the February quarter from $67 million in 2023 to $44 million in 2024. For six months revenues reached $88 million down 38 percent from $142 million in the prior year. The company incurred a loss of $187 million in the 2024 second quarter 45 percent worse than the $129 million and for the six months, a loss of $320 million was incurred marginally more than $302 million in 2023.

Paramount Trading is expanding into Chlorine and bleach processing.

Paramount Trading reported reduced revenues and profit for the third quarter and the nine months. Revenues in the February quarter declined 8.5 percent from $438 million in 2023 to $401 million in 2024. For the nine months, revenues fell 23 percent from $1.63 billion down to $1.266 billion with profits coming in at 40 percent lower at $18 million for the quarter from $30 million in 2023 and 44 percent to $100 million for the nine months of February this year from $179 million in the previous year.
One On One Educational Services reported revenues of $57 million in the February quarter down 12 percent from $73 million in 2023 and fell 27 percent to $111 million for the six months to February from $153 million in 2023.
A loss of $20 million million was incurred in the February quarter down from a profit of $6 million in 2023 and a loss of $41 million for the six months, down from a profit of $17 million in 2023 for the 6 months.

Main Event Q3 stunner

Main Event put in a stunning performance in the July quarter, this year with revenues rising 147 percent to a quarterly record of $601 million from just $243 million in the 2021 quarter, and profit surging 432 percent to $124 million from just $2 million for the 2021 quarter and investors immediately welcomed the good news by driving the stock up $8.57, the day the news broke on the JSE, trading in the halted in the first hour of trading on Thursday but it has since cooled to be trading around $8.

Main Event revenues growing nicely profit profit jumps.

The third quarter results helped push performance for the nine months, with revenues climbing 85 percent to $1.094 billion from $501 million, with profit ending at $104 million for the nine months, for a 332 percent increase from just $9 million in 2021. “The improved performance this quarter is underpinned by increased activity in our core business. The entertainment industry has seen a strong return to outdoor events and lifestyle experiences after a 2-year hiatus. The quarter is a historic one and reinforces our optimism for a sustainable shift following the Pandemic,” Chairman, Ian Blair and CEO Solomon Sharpe advised investors in their jointly signed report that commented on the results.
Gross profit rose 95 percent in the July quarter to $298 million from $163 million in 2021 and rose
48.6 percent from $344 million in 2021 to $511 million in the nine months to July this year. Gross profit margin ended the July 2022 quarter at 49.5 percent, down from 62.9 percent in 2021. For the nine months to July gross margin ended at 45.7 percent versus 58 percent in 2021.
Operating expenses rose 35 percent to $156 million, from $115 million in the July quarters and for the nine months, it rose a more moderate 19 percent to $3884 million from $322 million in 2021. Finance costs for the nine months fell from $12.7 million to $9.6 million.
Earnings per share for the latest quarter came out at 41 cents and 35 cents for the nine months.
The company generated $222 million in gross cash inflows before working capital changes and used up all the inflows for working capital needs of $200 million repaid loans amounting to $50 million and expended $33 million on the purchase of fixed assets.
The healthy top line performance resulted in receivables climbing from $150 last year July to 404 million at the end of July while cash on hand and bank slipped from $154 million to $132 million.
Borrowings declined from $206 million to $102 million, while payables rose from $100 million to $164 million. Shareholders equity rose from $543 million at the end of July last year to $654 million.
While the fourth quarter tends to be the weakest, investors should not bank on a repeat of the third quarter, but the 2023 fiscal year could be exciting.
ICInsider.com forecast is for earnings per share to end up at 45 cents for the year to November this year and 90 cents next year, putting the PE at 18 and 9 times 2023 earnings. The company could benefit from above average growth flowing from the full opening of the economy as was the case in the July quarter.

Profit climbs 20% at Paramount

Reduced administrative, selling and distribution expenses overcame a fall in revenues for the Junior Market listed Paramount Trading, for the fiscal year ending May 2021, to deliver a 20 percent rise in after tax profit to $64 million from $53 million in 2020 after profit surged more than nine times in the final quarter versus the similar period in 2020.

Paramount Trading had expanded into Chlorine and bleach processing.

In the final quarter, revenues rose 15 percent to $421 million from $366 million in 2020 and netted a profit of $36 million versus just $4 million in 2020. Sales revenue slipped 5 percent for the year to $1.44 billion, from $1.52 billion. Other income slipped from $25 million to $23 million, but foreign exchange gains contributed $19 million in 2021 versus $10 million in 2020.
Improvement in profit margin in the year saw margins rise from 30.9 percent in 2020 to 31.6 percent in 2021, but gross profit slipped 3 percent to $454 million, from $468 million in 2020.
Administrative expenses fell 32 percent to $68 million in the quarter, up from $100 million in 2020, and slipped 3 percent for the year, to $355 million from $367 million, a fall of $27 million in staff costs accounted for the bulk of the decline as salaries and wages fell from $179 million to $152 million as the average number of workers employed fell from 91 to 70. Distribution and sales expenses dipped from $19 million to $11 million. Finance cost inched higher from $48 million to $49 million in 2021.
The operations delivered gross cash flow of $121 million, but after changes in working capital, net cash flow from operations ended at $135 million. The company increased fixed assets by $9 million, had a net $15 million repayment of loans and paid $62 million in dividends, ended with increased funds at the end of the year of $49 million, pushing cash and investments to $261 million at the end of the fiscal year.

Paramount lubricant factory.

At the end of May, net current assets stood at $472 million. Current assets ended the period at $836 million inclusive of trade and other receivables of $323 million, cash and bank balances of $91 million. Current liabilities closed the year with $364 million. Non-current Investments being held for more than a year stood at $170 million. Shareholders’ equity ended at $796 million with long term borrowings at $473 million, down from $492 million in 2020 and short term loans amounted to $47 million versus $43 million in 2020.
Earnings per share amount to 4.1 cents for the year. ICInsider.com forecasts 10 cents per share for the fiscal year ending May 2022 with a PE of 12.5 at the last traded stock price at $1.25 on the Junior Market of the Jamaica Stock Exchange. Net asset value is 52 cents per share, with the stock selling at 2.5 net book value.
The Company’s principal activity is the importation and distribution of chemicals, lubricants and other related products, provision of haulage services and blends lubricants.

Profit up 21% at Lasco Distributors

Lasco Distributors reported full-year results to March, with revenues rising 7.5 percent to $19.5 billion and profit increasing 21.4 percent to $726 million. The year’s performance reflects a big recovery after profit fell 30 percent in the first quarter to June last year, and 10 percent to the end of the third quarter.
The company enjoyed an 8.24 percent rise in revenues for the March quarter to $5.2 billion, with profit after tax for the quarter at $183 million, up 961 percent from just $17 million in 2019. The quarter suffered from a fall in gross profit margin to 18.4 percent versus 19.2 percent in 2019. Gross profit was 19.4 percent for the fiscal year versus 19.6 percent in 2019.
Other income in the fourth quarter climbed to $60 million, a turnaround from a loss of $37 million in the March quarter in 2019, but was nearly flat at $130 million for the year to March.
The increase in cost for the year was kept close to the growth in revenues, with Administrative expenses rising 8 percent to $2.37 billion while selling and promotion expenses fell 9 percent to $703 million for the year.
Segment results show revenues rising 3.6 percent for the Consumer division for the fiscal year to $15.7 billion while the Pharmaceutical division jumped 27.7 percent to $3.8 billion. Segment profit jumped 36.5 percent for the Consumer division to $557 million but the Pharmaceutical division dropped by 18.6 percent to $154 million even as revenues rose strongly.
Earnings per share ended at 21.27 cents and IC Insider.com projects 38 cents per share for the 2021 fiscal year, with the stock trading at a PE ratio at 7.7 at the last traded price of $2.91, well below its sister company, Lasco Manufacturing.
Cash flows from operating resulted in the generation of $1 billion before working capital changes. Current assets stood at $6.9 billion, including Cash and cash equivalents of $1.47 billion at the end of March with current liabilities closing the year at $3.38 billion. Shareholders’ equity ended the year at $5.7 billion, with borrowed funds being just $116 million.
The company paid a dividend amounting to $151 million last year, with profit rising, a large pool of cash and virtually no borrowed debt, there is room for a big increase in future dividend payments that could make the stock an attractive dividend payer.