TheJSE Market Index fell 547.63 points to 99,126.83,  theJSE All Jamaican Composite index lost 612.11 points to close at 109,736.10 and the JSE combined index lost 485.94 points to end at 101,383.99 and the junior market index rose 3.35 to 874.63.Thirty three securities traded up to 11 am, including 12 junior market stocks, with Cargo Handlers trading 205,972 units at a new high of $22.29 as Mayberry Investments crossed the shares from their in house inventory to a client. Four new 52 weeks’ highs have been recorded, Hardware & Limber at $19, Jamaica Stock Exchange at $4.80, Cargo Handlers at $22.29 and Derrimon preference shares trading at $2.50.
The preference shares section was active with 4 securities trading as investors seek higher yielding investments.
Main market slips junior up
Buy Rated blooming

Hardware & Lumber with its Rapid True Value retail arm gained 291% since place on BUY RATED list
Trinidadian stocks have hardly gone anywhere the Jamaican ones are soaring after a long period of drought. There are three triple winners in the main Jamaican market including Hardware and lumber that is up 291 percent since we selected it as Buy Rated. Interestingly, they are no losing stocks in this market. The junior stocks have erased most of the losses suffered earlier and now only two stocks record any losses. Technical indicators are pointing to
 the Jamaican rally continuing for the rest of the year with lower inflation and interest rates coupled with continued strong profit gains. Trinidad stocks will continue to be under pressure but there are a few severely undervalued ones in that market that could post decent gains in the months ahead.
Access still has further to go as the future looks good for growth in profits but the price of the stock could be trading around current levels for some time but there is limited volumes available, this one becomes a longer term buy with the price where is currently lies. Caribbean Cream and Paramount seems to have quite some gains to deliver in the months ahead as improving results encourage investors to buy into the growth prospects. Lasco Financial could be going anywhere with Mayberry buying 20 percent and buying more in the market of a stock with limited float and Medical Disposables has good potential to deliver a decent gain.
The main market may have had lots of gains so far but there is much more to come from even some of the top performers such as Jamaica Stock Exchange, National Commercial Bank, Caribbean Cement and Carreras to name a few. Over in Trinidad, Guardian Holdings is undervalued but National Flour is severely undervalued, Trinidad Cement is a huge buy with much upside potential especially with debt restructuring leading to lower interest cost and lower energy cost in Jamaica and Barbados.
Caribbean Cream profit upgrade
 Caribbean Creams profit upgraded to show a 62 percent increase to $56.8 million or 15 cents per share above the 2014 earnings, according the audited financial statements compiled by KPMG, the company’s new auditors.
The comparative 2014 results were $35 million after a small tax expense. The interim report had profit for the year at $49 million on slightly higher sales than the audit report showed. The major area of change was lower administrative cost of $12 million in the audited accounts versus the preliminary figures. Caribbean Cream enjoyed an increase of 305 percent in profit in the final quarter to reach $25.7 million up from $6.4 million in 2014 quarter, according to the data in the audited accounts and third quarter interim results.
IC Insider is forecasting profit of 244 million for the 2016 fiscal year or 65 cents per share from increased sales revenues that will flow mainly from a 15 percent price increase effected just before the Christmas season.
The stock which was listed on the junior market of the Jamaica Stock Exchange in 2013 at an IPO price of $1, traded at $1.10 on Thursday and has moved up from 65 cents just before the release of the interim results.
Purity profit jumps 204%
 A 204 percent increase in profit for Consolidated Bakeries better known as Purity, in the March quarter saw net profit ending at $13.9 million (2014 $4.58 million) from a 15 percent increase in revenues of $226.28 million.
Gross profit margin increased to 34.2 percent from 30.6 percent in 2014 and contributed much to the increased profit. Lower electricity cost would have made a big contribution to the improvement in this area. Administrative and other expenses rose less than revenues at 6.7 percent and selling and distribution expenses rose by 12.1 percent just below the growth in revenues.
The company earned 6 cents per share well up on that for 2014 and compares with the 8.4 cents reported for the twelve months of 2014, IC Insider is forecasting 20 cents for the full year. With the stock price at $1.15 on the junior market, it boasts a PE of 5.7 and has a net asset value of $2.42.
Consolidated Bakeries that produces and markets baked products such as breads, buns, crackers and cookies has equity of $540 million, loans of $64 million and cash funds of $110 million.
JSE Markets up pace slowing
Grace fell $1 after reporting a decline in Q1 profits
Activity on the Jamaica Stock Exchange, resulted in the prices of 15 stocks rising, including 8 new 52 weeks’ high, 7 declining as 35 securities changed hands, ending in 4,079,019 units trading, valued at $46,667,393, in all market segments. The JSE Market Index gained 295.86 points to 99,287.96, the JSE All Jamaican Composite index rose 330.79 points to close at 109,726.84 and the JSE combined index gained/ put on 321.05 points to close at 101,740.07. Stocks closing at new 52 weeks’ highs, in the main market are, Berger Paints, Desnoes and Geddes, Caribbean Cement, Jamaica Broilers and Radio Jamaica.
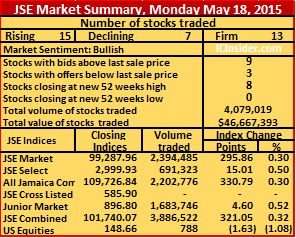 IC bid-offer Indicator| At the end of trading, in the main and junior markets, the Investor’s Choice bid-offer indicator shows 9 stocks with bids higher than their last selling prices and 3 with offers that were lower.
Stocks trading include, Berger Paints ended trading with 81,477 shares changing hands to close 20 cents higher at $2.55, Caribbean Cement closed with 240,866 shares trading, 89 cents higher, at $5.10, Carreras finished trading with 20,385 shares and lost 35 cents to close at $49, Desnoes & Geddes saw trading in 31,000 shares trading 5 cents higher at $7.25. Gleaner closed with 170,739 units trading, with the price unchanged at $1, Grace Kennedy finished trading with 42,032 shares and fell $1 to close at $63.50. Jamaica Stock Exchange concluded trading with 25,000 units trading with the last price unchanged at $3.50, JMMB Group completed trading in 11,506 shares changing hands and jumped $50 cents at $10,the stock closed with an offer at $9.49, Kingston Wharves had dealing in 34,221 units traded at 6 cents up to $6.26.
 Mayberry Investments contributed 93,828 units to trading and close unchanged at $3, National Commercial Bank ended trading with 52,070 shares changing hands to close down by 50 cents at $30 and based on today’s trading which saw the bid that was at $30 for several days, to buy an undisclosed amount being pulled, it looks as if the price could fall back below $30, Radio Jamaica closed with 100,000 shares trading at $2.48 after adding 8 cents, Sagicor Group finished trading with 1,127,037 units but remained unchanged at $12, after it trading during the day at $11. Scotia Group ended trading 72,725 units to close 14 cents higher, at $25.30, Scotia Investments closed with 2,300 shares, 75 cents up at $25.50. Jamaica Money Market Brokers 8.75% preference share finished trading with 153,398 units changing hands to close 2 cents higher at $3.02 and Proven Investments 8% preference shares saw trading in 26,805 units with the price ending unchanged at $5, after gaining 50 cents earlier in the day before falling back.
D&G profit nearly doubles in Q3
 A combination of increased sales’ volume and price adjustment saw Desnoes & Geddes, the producers of the world famous Red Stripe beer, enjoying a 20 percent jump in sales revenues in the March 2015 quarter.
Sales reached $2.96 billion and a near doubling in profit to $367 million for an 88 percent increase from $196 million in 2014. For the nine months to March profit was up a more sedate 29 percent on a 14 percent sales increase to $9.6 billion over 2014.
Local sales rose 20 percent in the March quarter and exports were up only 6 percent, for the year to March exports grew 11 percent and local sales 13 percent.
Earnings per share for the quarter came in at 13 cents and 54 cents for the nine months and should end at 80 cents for the full year and $1.05 for 2016 fiscal year. Gross profit margin increased during the nine months period to 41.4 percent from 39.94 percent and 37.7 percent during the quarter from 36.2 percent.
The March quarter saw a turnaround in the results of the distribution company it’s a joint venture partner with Pepsi in, which contributed $20 million in the quarter compared with a $47 million loss in 2014 and for the nine months, losses increased to $62 million from $46. Marketing cost jumped to a billion for the nine months from $737 million in 2014. Other costs were held fairly tight.
The period ended with net fixed assets increasing by $1.5 billion but the company still ended with cash funds at $1.38 billion and equity of $9.4 billion.
The stock is listed on the Jamaica Stock Exchange and closed last at $7.20, with a PE ratio of 9.
JSE profit surged – 2016 could be big
 Jamaica Stock Exchange reported a huge jump in first quarter earnings showing profit of $87 million or 62 cents, up from a loss of $3 in 2014, after tax. Revenues jumped from $82 million to $253 million, on the back of 10 fold increase in cess, due to primarily to the transfer of ownership of the controlling interest in Scotia Group, from the Canadian parent, to one set up to own the Caribbean entities directly.
Total cess income jumped to $161 million compared to only $15 million. Access Financial managing director switched ownership of his shares to a company, resulted in a transaction over the exchange of $1 billion and Pan Jamaican Investments had a $1.3 billion transaction in March. While the latter two unusual transactions would have increased the cess around $12 million, the cess for Scotia Group is estimated by IC Insider at around $120 million, leaving around $40 million as cess from normal ongoing operational activities. Trading values grew by 27 percent in the first quarter, including the two transactions in March. Fee income which rose by 67 percent would have been partially impacted by the big one off transactions, but increased value traded and a slight increase in listing fees would also have helped.
In the second quarter to mid May trading has increased 333 percent to $2.6 billion, the amount is equal to the total value traded for the entire second in 2014. The increased value of trading will lead to increased fees. In the 2014 second quarter, income from cess was only $10 million and fee income $45.5 million. Not only will the cess rake in more funds from the increased volume of trading now on the way but also from an increase in the rate charged for cess over the 2014 level.
While the increased trading activity so far will lead to increased fees for the second quarter, the potential income will be no more than around $100-120 million and will be sufficient to produce a profit for the quarter and help in lifting profit for the full year beyond $1 per share.
Looking forward, with more unit trust schemes being set up there will be more demand for stocks to satisfy the demand of equity funds. The Stock Exchange is poised to take over repo trading and acting as the registrar for them and result in additional fee income is going in the not too distant future, also of great import is that rising stock values increases the base for listing fees to be levied in 2016.
The exchange has cash and investments of $500 million with a working capital ratio of 2:1 and equity of $650 million. The stock remains IC Insider BUY RATED and is now available at $3.50 which it traded at on Friday, but won’t remain that way forever and investors should be buying this one for big long-term gains.
19 stocks rose only 3 fell on JSE

Hardware & Lumber gained $1.25 to a new high of $12 in response to news that Grace is in negotiation to sell their interest in the company
The rally started last year fuelled by falling money market rates with Treasury bill rate falling from over 9 percent to below 7 percent. The current rally is be fuelled by rising profits from the majority of companies reporting first quarter results.
The JSE Market Index lost 507.33 points to 98,992.10, the JSE All Jamaican Composite index fell 567.23 points to close at 109,396.05 and the JSE combined index declined 237.32 points to close at 101,419.02.
IC bid-offer Indicator| At the end of trading, in the main and junior markets, the Investor’s Choice bid-offer indicator shows 15 stocks with bids higher than their last selling prices and 2 with offers that were lower.
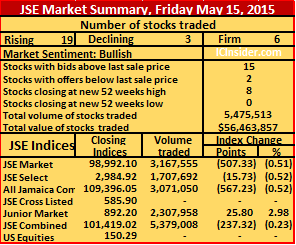 Stocks in the main market trading to close at a 52 weeks’ high, are Berger Paints, Desnoes & Geddes, Hardware & Lumber, Jamaica Stock Exchange, JMMB Group and Mayberry Investments. In trading, Barita Investments ended with 622,050 shares changing hands to close at $2.35, Berger Paints closed with 55,162 shares trading, 27 cents higher at $2.35, Cable & Wireless finished trading with 619,569 shares to gain 1 cent to 47 cents, Caribbean Cement saw trading in 3,351 shares, to close 1 cent higher at $4.21. Carreras closed with 32,376 shares changing hands to close 35 cents up at $49.35, Desnoes & Geddes finished trading with 14,650 shares and gained 10 cents in trading to close at $7.20, Grace Kennedy concluded trading with 307,283 units trading with the last price unchanged at $64.50, Hardware & Lumber completed trading in 9,092 shares changing hands and jumped $1.20 at $12 as investors responded to news that Grace is discussing selling their stake in the company. Jamaica Broilers had dealing in 48,730 units traded at $5.16 to remain unchanged at the end. Jamaica Stock Exchange contributed 244,616 shares, the price jumped 60 cents or 21 percent in response to the company’s huge jump in their first quarter results showing profit of $87 million or 62 cents and ended at $3.50. Trading was halted for an hour after the price exceeded 15 percent. JMMB Group ended with 27,855 shares changing hands to close up by 10 cents at $9.60, Mayberry Investments closed with 12,289 shares trading at $3,after adding 12 cents, National Commercial Bank finished trading with 468,084 units unchanged at $30.50. Pan Jamaican Investment ended trading with 14,769 units 12 cents higher, at $58.25, Sagicor Group closed with 191,168 shares trading 15 cents lower at $12. Scotia Group finished trading with 88,383 shares changing hands to close 84 cents lower at $25.16, Seprod saw trading in 335,400 shares ending 25 cents up at $18.50 and Jamaica Money Market Brokers 7.50% preference share ended with 68,650 units trading with a 5 cents rise to $2.15.
JSE back at August 2008 levels
Scotia rose to $27 during trading to help push market on Monday
Today’s trading resulted in the prices of 13 stocks rising, 9 declining as 32 securities changed hands, ending in 3,376,261 units trading, valued at $34,457,428, in all market segments with the market indices continuing to record gains. The market closed with 6 new 52 weeks high in the junior and main market.
TheJSE Market Index gained 1,291.03 points to 98,710.56, the JSE All Jamaican Composite index rose 1,443.44 points to close at 109,081.28 and the JSE Combined Index closed at 100,708.70 with a gain of 1,293.92 points.
 The JSE All Jamaican Composite index closed at the highest level since it closed on August 28, 2008 at 109,877.58. Based on Monday’s close, the market has now crossed over the resistance trend line, just below today’s close. With Scotia Group pulling back from today‘s high of $27, there is no certainty that it will remain above resistance at the close on Tuesday, even if it does not pull back, the 115,000 mark, just 6,000 points away, is likely to be a real test as most first quarter results would have been released this week.
IC bid-offer Indicator| At the end of trading, in the main and junior markets, the Investor’s Choice bid-offer indicator shows 11 stocks with bids higher than their last selling prices and 4 with offers that were lower.
Stocks trading include, Berger Paints trading 2,705 shares at $1.80 after shedding 15 cents. Cable & Wireless ended with 196,631
 shares to close up 3 cents at 46 cents, Caribbean Cement ended with 15,074 units with the price falling 49 cents to $4.50, Carreras traded just 2,000 shares and declined 85 cents to $48.10, Desnoes & Geddes traded 252,106 shares $6.90 while adding 30 cents, Gleaner finished trading 886,808 units at $1, Jamaica Broilers ended trading with 7,634 shares at a new 52 weeks’ high of $5.25 after posting a gain of 45 cents. Jamaica Stock Exchange ended with 607,587 units and lost 3 cents at $2.90, JMMB Group closed with 35,677 shares at $9.10, for a gain of 39 cents. Mayberry Investments had dealing in only 1,669 shares to close at $2.80, to gain 5 cents, while National Commercial Bank contributed 845,891 shares at $30. Radio Jamaica traded gained 19 cents while 25,185 shares traded at a new 52 weeks’ high of $2.19, Sagicor Group completed trading with 191,940 units at $12, with a 10 cents loss. Scotia Group traded 16,348 shares to close at $25.02 to lose 98 cents compared to Friday’s close but traded at a new intraday high of $27. Scotia Investments had 10,000 units trading at $24.60 to gain 10 cents and Jamaica Money Market Brokers 7.50% preference share traded 50,000 units at $2.11.
Access Q1 profit jumps 72%
 A fifteen percent jump in revenues at Access Financial Services saw profit before tax almost doubling to $157.6 million, up from $79 million in 2014. After providing $20 million for corporation taxes Access ended with $137 million profit or 50 cents per share for an increase of 72 percent. The good fortune did not all come from ongoing income and expenditure as loan losses fell from $39 million in the March 2014 first quarter to only $3 million in the latest quarter. Gains from the purchase of loan portfolios from Appliance Traders and Proven Investments resulted in a one off profit of $11 million. These acquisitions increased loans on the books to $1.5 billion from $1.1 billion at March 2014 and the profit pushed the equity capital to $900 million.
For the full year earnings should touch $2 per share, the stock is priced at $15.10 with a potential PE of 7.5, with its growth potential and limited available shares on the market, this valuation may be considered low.
Proven Investments who bought out the Mayberry Holdings last year December, is laughing all the way to the bank for having picked up the block of shares at a bargain price of $9 each.
Access is a junior market listed company on the Jamaica Stock Exchange and is primarily involved in payroll based lending.