Pan Jam profit stable

Pan Jamaican Investment Trust released results for the half year to June and reported profit attributable to shareholders for the June quarter of $486 million, a slight 4 percent increase on the $468 million in the 2012 quarter. For the six months ended June, Pan Jam made $710 million, compared to $970 million for 2012, a decrease of 27 percent.  The results equated with earnings per share amounted to $2.28 for the quarter and $3.34 for the six months to June.

The year to date results were negatively affected by the decision by both Pan Jam and the Sagicor group, an associate, to swap older debt with a higher book value for new government of Jamaica debt at a lower value (JDX2) which resulted  in a large loss.

pan_jamaican_logo150x150Helping to boost the results was the share of results of associated and joint venture companies which rose from $227 million to $532 million in the June quarter and up from $305 million in 2012. For the six months to June, these investments resulted in $769 million being booked and is largely due to an increased shareholding in Sagicor, which was partly offset by increases in finance costs of $119 million.

In their comments on the results, Management stated that “Investment income of $44 million in the second quarter was lower than last year’s comparable quarter by $36 million, as unrealised losses on securities trading of $26 million eroded foreign exchange gains, interest income and dividends. Year to date investment income of $145 million is 27 percent ahead of last year due principally to significantly higher foreign exchange gains. Property income was flat compared to last year for both the quarter and year to date, as stable occupancy levels and continuing modest growth in rental income were offset by reduced property revaluation loss.

“Group operating profit for the 2nd quarter decreased by $73 million or 32 percent, compared to last year’s 2nd quarter. For the year to date, group operating profit of $388 million is $23 million or 6 percent less than last year’s level. Total revenue was lower for the quarter compared to last year by $32 million, 7 percent, principally attributable to the decline in investment income, but ahead of last year for the 6 months.”

Occupancy | The group enjoyed overall rental occupancy exceeding 95 percent for the 2nd  quarter, a slight decline from last year, while contribution to group operating profit of $158 million for the quarter ($342 million year-to-date) was $42 million ($16 million year-to-date) lower, attributable to reduced property revaluation gains.

Operating expenses | Management said that operating expenses increased by $41 million for the quarter, and $69 million for the 6 months, driven by increased levels of direct property costs, professional fees associated with investment opportunities and general increases in staff costs. Finance costs increased compared to last year by $119 million to $137 million for the quarter, and by $298 million to $331 million for the 6 months, resulting from increased loans booked.

PamJamChukkaCove150x150Associated Companies | The associated companies consist principally of a 32.8 percent investment in Sagicor; minority positions in New Castle Co. Limited, owners of the Walkerswood and Busha Browne lines of sauces and seasonings; Mavis Bank Coffee Factory Limited; Hardware & Lumber Limited; Caribe Hospitality Limited (developers of the planned New Kingston Marriott Courtyard Hotel) and Chukka Caribbean Adventures.

Pan Jam’s share of Sagicor’s comprehensive income for the quarter was a loss of $426 million consisting primarily of unrealized losses on available-for-sale securities, net of exchange gains. For the year-to-date, the share of the net unrealized loss is $275 million, compared to a share of net unrealized gains of $52 million for the comparable period last year.

According to management “New Castle’s results for their fiscal year ended April 30 2013 increased more than threefold on the back of a 44 percent jump in revenue, while Mavis Bank again posted good results. Chukka overcame Hurricane Sandy-related disruptions to cruise ship passenger arrivals and the temporary closure of the cruise ship port in Turks and Caicos to post returns in line with expectations.”

Balance Sheet | Total assets at June amounted to $22 billion, compared to $21.4 billion at the end 2012. Stockholders’ equity increased to $16.6 billion equating to a book value per stock unit of $77.85.

Related posts | Pan Jam’s profit dented too

Is C2W doomed?

After almost two years, C2W Music, which promised that they would be making profits by now is yet to show the income, much less profits.

In its prospectus for the IPO to raise $129 million on the Jamaica Stock Exchange, the company made this statement about profitability, “As a start-up, the Company is expected to post a Pre-Tax Loss for 2012 of approximately US$241,849. The Directors expect earnings to stabilize from 2013 onwards, with a projected profit before tax of US$668,100 in that year, increasing threefold to a projected Profit before Tax of US$2.36 million in 2016.”

The results to June indicates that those projections were just a pipe dream as the company not only reported a loss of US$345,855 for the six months to June 2013, but for the similar period in 2012 when the loss was US$131,284, and there was just US$1,803 income for the six months. While it is not impossible to win contracts for songs that could change the picture, one would need to see a steady, if even small, flow of income but that is not the case with a year and a half now gone.

C2WMusiclogo2Shareholder equity now stands at US$377,257 down from US$1.2 million at June last year. Cash is almost gone entirely with just US$14,335 left of the sum raised in the IPO. C2W has assets in the form of advances to song writers of more than US$300,000 but that is not income and only $24,000 are due within a year.

The company needs a knight in shining armour and FAST if it is to avoid the burial ground. Crunch time is nigh.

First Citizens lousy investor’s relations

It was once said that as a country, Trinidad wanted to be the financial capital of the Caribbean, but recent activity on the country’s capital market indicates that they have a far way to go in achieving such a goal — if that is possible.

First Citizens Bank launched the largest ever Initial Public Offering (IPO) of shares in the history of the T&T Stock Exchange with a market value of approximately TT$1.1 billion on Monday 15th July at an offer price of TT$22 per share for 48,495,665 shares. The bank said the IPO will assist in widening its capital base in order to facilitate future strategic expansion plans. The offer was slated to close on August 9 and was extended to Monday, August 12th 2013 as the 9th was a public holiday.

First Citizens Brokerage & Advisory Services, a subsidiary of First Citizens Investment Services, is the Lead Broker for the Offer for Sale. The handling of the entire issue is a classic demonstration of poor investor relations and that is not a good sign for investors.

First_Citizensbuilding150x150Listing on September 16 | The T&T Stock Exchange has advised that First Citizens has applied to have its shares listed on the TTSE on September 16th 2013 subject to the approval of its application to list by the Board of the TTSE.

This is madness and is reflective of lack of sensitivity in their financial market. First off, the opening time for the issue was unnecessarily long so those who applied early had their funds tied up without any compensation. Even worse is after nearly a month of closing of the issue, investors are yet to know what is their allocation of shares. First Citizens said on their website that investors will find out between August 30 and September 6.

A check with the T&T Stock Exchange as to why it will take such a long time for the shares to be listed indicates that the problem is not with the Exchange, who are ready to list as soon the information is available and is approved by the Stock Exchange Council. A Stock Exchange source suggests that the delays maybe due to the broking community not being fully conversant with how to execute a timely IPO.

Oversubscription | Information obtained suggests that the issue was about two times oversubscribed with institutional investors probably being the main subscribers resulting in the high level of oversubscription.

While the management has made major missteps in dealing with this issue, IC Insider still rates the stock as Buy Rated based on the issue price and potential earnings. We believe there should be a steep appreciation in the stock’s value when it is compared with others within the financial sector.

Related Posts | First Citizens’ $1B IPO opens today | T&T Citizens Bank IPO oversubscribed | Buy Rated stock list grows

General Accident undervalued, but . . .

General Accident Insurance Company continued to perform well in the second quarter as they did in the first of this year with profit increasing 48 percent to $80 million in the second quarter bringing the six month results to $177.7 million, an increase of 57 percent over the same period in 2012. The company said they made more money in both our underwriting and investment operations and as a result were able to improve their overall profitability and capital efficiency.

Underwriting | For the two quarters, gross premiums grew to $3.2 billion, an increase of 21 percent over the first six months last year. Net earned premiums grew by 8 percent to $443 million. “Premium growth was driven by the healthy organic growth of our core commercial property and motor businesses as well as the execution of facultative transactions on behalf of large domestic and multinational clients,” the company said.

“Our combined ratio improved from 92 percent in the first six months of last year to 90 percent in the first six months of 2013. The improvement in our combined ratio, the insurance industry benchmark for underwriting profitability, occurred despite continued softness in insurance rates and a deteriorating loss ratio. As a result, our underwriting profit in the first half of 2013 stood at $42 million compared to $34 million during the same period last year”, management continued to state.

GeneralAccident_logo150x150Claim expenses rose from $247 million for the year to June last year by 25.5 percent to $310 million in 2013. Management expenses rose from $145 million for the year to June 2012 by 14 percent to $165 million in 2013 and in the latest quarter from $75 million to $88 million, an increase of 17 percent.

Investment Performance | For the six months to June investment income amounted to $145 million, an increase of 68 percent compared to $86 million in the first half of 2012. Investment income in the June quarter was only $52 million much less than the amount generated in the first quarter. A slower fall in the value of the Jamaican dollar would have resulted in a lower gains from foreign currency trading or translation.

Summary | A sharp change in commission expense from a loss of $78 million in the June quarter of 2012 to a small surplus of $6.5 million helped in no small manner to boost the bottom-line in the quarter even as net premiums earned declined from $205 million to $187 million and claims jumped from $118 million to $157 million over the same period.

The company paid out $50 million in cash dividends to shareholders in the first quarter.

Assets jump | The company that had assets totaling $3.9 billion at the end of December last year, has seen a major jump to June to $7 billion mainly as amounts due from reinsurers and co-insurers doubled to $2 billion. The amounts due from policy holders climbed $1.3 billion to $41.8 billion and cash and short term investments increased by $500 million.

On the other hand, amount due to reinsurers and co‐insurers moved up by $1.75 billion, insurance reserves up by $1.3 billion and shareholder’s equity by a little over a $100 million to $1.4 billion since December last year.

Return on average equity is 25 percent which is attractive if the company can maintain the current profit levels. If they can, then earnings per share should reach 35 cents for the year, which makes the stock now priced at $1.85 cents a bargain.

The stock traded at $2.81 in 2011 when profits were not as strong as it is now. Additionally, a number of junior market companies are trading around 6-7.5 times 2013 earnings with General Accident at 5.3 times, suggesting there is room for capital gains in the medium term. Of course Jamaica is in the midst of the hurricane season and some investors may not want to be bold ahead of the end of the season, just in case there is major damage and claims. This stock ought to be watched for benefit from what could be a nice price gain before year end.

Insider call | General Accident is an IC Insider Buy Rated stock.

Related posts | Buy Rated stock list grows | General Accident’s profit up 65 percent

TCL stock gains continue

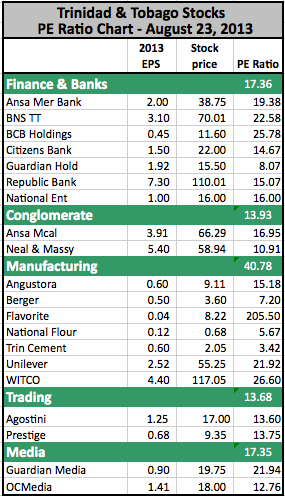
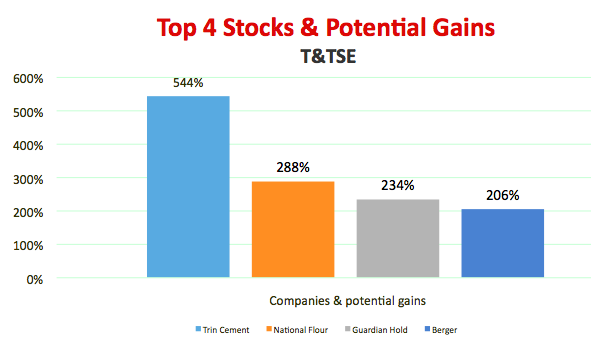
Friday, 23rd August 2013 | Trinidad Cement continues on its merry march upwards on the Trinidad Stock market thus reducing the potential gains left in the stock. It was this week’s greatest mover, moving from a bid of $1.76 at the end of last week to a closing price of $2.05 this week for a gain of nearly 17 cents. With a potential gain of 544 percent left and the bid being firm at $2.05 with a fair volume, expect to see the stock price increase in the week ahead.

National Flour Mills and Guardian Holdings lost value thus increasing the potential gains in these stocks. Elsewhere values remained the same as at the start of the week. Angostura has a bid of $9.11 at the end of trading on Friday , which is above the last selling price, suggesting that it will trade higher in the week. Guardian Holdings looks as if it could decline some more before it starts to rise.

Based on PR ratios, the Top Four stocks with potential on the TTSe are Trinidad Cement, National Flour, Guardian Holdings and Berger TT.

TTSE PE RatioAug23

TTSE PE RatioAug23Chart1

TTSE PE RatioAug23Chart2

Another acquisition for Jamaica Broilers

Jamaica Broilers Group entered into an agreement on August 20, 2013, to acquire Hamilton’s Smoke House Limited, a leading local producer and processor of premium quality smoked meats, poultry and pork products. The acquisition will strengthen the Company`s presence in the further processed meats segment and complement the Company`s existing product lines. Completion of the acquisition, which is subject to certain conditions, is expected to be within forty-five (45) days. Under the terms of the transaction, the purchase price is to remain confidential.

This is the second acquisition the company has entered into in just over a month. In July, Jamaica Broilers advised that it has entered into an agreement on July 17, 2013, to acquire a leading producer and broker of broiler hatching eggs in the United States of America. “This acquisition, if concluded, is expected to result in the doubling of JBG`s fertile egg production output in the United States.

The group should benefit from economies of scale from both of these acquisitions when fully integrated. Jamaica Broilers reported a 17 percent improvement in after-tax results for the year to April 2013 with profits of $1.1 billion from a 12.5 percent increase in revenues to $26.7 billion. The group has equity capital of $9.7 billion and total assets of $18 billion at the end of April this year.

Insider call | Jamaica Broilers Group is an IC Insider Buy Rated Stock

Dividends to come

Jamaica Public Service Company declared quarterly preference share dividends payable on October 1, 2013 to shareholders on record as at September 13, 2013 with the ex-dividend date is September 11, 2013, as follows:

  • 7% Cumulative Preference Shares “B” – $0.035 per share
  • 5% Cumulative Preference Shares “C” – $0.025 per share
  • 5% Cumulative Preference Shares “D” – $0.025 per share
  • 6% Cumulative Preference Shares “E” – $0.03 per share

Dolphin Cove declared an interim dividend of 10 cents per share payable on September 16, 2013 to shareholders on record as at August 29, 2013. The ex-dividend date is August 27, 2013. The company previously paid a dividend of 10 cents per share on June 6, 2013 to shareholders on record as at May 20, 2013 as well as one in March this year.

Guardian Holdings declared a dividend of TT$0.15 payable on September 5, 2013 to shareholders on record as at August 22, 2013. The ex-dividend date is August 20, 2013.

Proven Investments declared a preference share dividend of $0.10 per share payable on September 23, 2013 to shareholders on record as at September 9, 2013. The ex-dividend date is September 5, 2013.

Proven Investments declared a dividend of US$0.0021 per ordinary share payable on September 10, 2013 to shareholders on record as at August 27, 2013. The ex-dividend date is August 23, 2013.

Related posts | Guardian maintains strong rating |  FX gains & securities boost Proven

Radio Jamaica’s sharp turn

Radio Jamaica made a sharp about turn in profitability in the June quarter reversing a loss of $25 million in 2012 to a small profit of $1.6 million. The change came about as revenues increased by 7.3 percent to $440 million. The company says the change in revenue is due to increased advertising income, flowing from the website’s continuous growth in visitors and increased portfolio of local production in television which contributed favourably to higher income and improvement in response to the sales and marketing.

Also helping the changed bottom line was a doubling of other income from $17.7 million to $34.65 million but it is cost cutting that really did the trick. Selling expenses was cut to $70 million from $76.4 million in 2012, administrative expenses was reduced from $103.7 million down to $98.5 million and other operating expenses which came in at $73.4 million was down from $87 million. RJR negotiated a number of contracts but bringing the cable channel under the same roof as the main studios help cut costs as well. Interest cost was one expense that climbed as loans were taken on to help fund the acquisition the FIFA franchise for matches between 2013 and 2022. This amount climbed from $1.2 million to $5.4 million.

RJR_Newslogo150x150RJR would have suffered revenue decline from the closure of Claro mobile network resulting in less completion in the market as well as the general economic downturn, which started in late 2008. Data to date indicate that the economy is still declining at least up to the first six months of this year. Forecast going forward does not reflect any signs of much economic growth.

The turnaround in profits is welcomed news for investors who have seen profits decline from 2010 when it peaked at $222 million ending with a big loss for the year ended March 2013. Even with the return to profits, the company is not fully out of the woods as the economy is still fragile and things could get more difficult before they get better. In such an environment, the strength of the finances take on even more import.

IC Insider forecast is for the 2013/14 year to show profits of $63 million after tax or earnings per share of 18 cents which would be a big improvement over the $36 million loss reported last fiscal year ending March 2013.

Loan funding is now at $193 million and cash funds at $252 million and receivables is $439 million versus payables of $224 million.

Related posts | RJR’s $106M 4th quarter loss

NASDAQ 3 hour shutter

According to reports, NASDAQ, the second largest stock exchange in the USA and World, halted trading today for 3 hours due to a glitch in its computer system. This is bad news for one of the more popular exchanges that newer companies tend to flock as opposed to the older New York Stock Exchange (NYSE).

Previously, NASDAQ was in the headlines when Facebook debuted on the exchange and trading in the stock was suspended for hours before trading could begin, creating confusion and losses for many. The exchange was slapped with a US$10 million fine and suffered additional losses by paying out compensation to investors as a result of the failure.

Many were fearing that Facebook may shift the listing from NASDAQ to the NYSE but so far this has not happened.

One would expect these failures in third world countries and not in a developed one. The problem with failures is that it reverberates around the world as other exchanges rely on the NASDAQ for prices. In this case, over 50 exchanges worldwide were affected which could result in losses for some investors. More importantly, it affects investor and public confidence in a big way.

Read more | Nasdaq suffers reputation hit after trading freeze

Profit up, margins shrink at Seprod

Shrinking margins and lower gross profit could not prevent Seprod from enjoying a bump in profit of $312 million in the June quarter versus $161 million in 2012 and $542 million for the six months period versus $453 million in 2012.

Seprod got a boost of $107 million from the sales of equities in the June quarter. Also in the quarter, they benefitted from a gain of $54 million from holding of assets in foreign currency. Finance and other operating income rose to $112 million in the quarter, up from $80 million in 2012 and for the six months, $206 million versus $167 million. Management has kept selling and administration cost under control with both areas falling in the latest quarter and just rising slightly for the year to date period. Selling expenses which came out at $100 million for the quarter was $6 million less than in 2012 and admin cost came out at $372 million versus $374 million in 2012. For the six months, selling expenses climbed by $4 million to $198 million and admin went to $784 million up from $751 million in 2012. Finance cost moved up to $42 million from $26 million in the June quarter and in the six months period, it rose from $48 million in 2012 to $82 million in the latest period.

Revenues | Revenues were down 2 percent in the first quarter, falling to $3.7 billion and off by $74 million from the year ago period. However, revenues increased by a healthy 17 percent to $3.7 billion in the June quarter and is up 7 percent for the 6 months to June.

The biggest issue the company is currently having is a sharp fall in profit margin. To June 2012, gross profit as a percentage of direct cost was 28.2 percent and has fallen to 24 percent for the 6 months to June this year and to only 21 percent versus 24 percent in the June quarter. The deterioration has occurred in the distribution segment as profit stagnated at $99 million, a slight 3 percent rise in that area while sales rose 11.5 percent. In the manufacturing segment, profit is up by 12.5 percent to $893 million and revenues is up 3.5 percent to $4.7 billion.

Earnings per share for the 6 month period is $1.05 and the full 12 months to December should be around $1.80-$2.

Finances | Seprod has $3.9 billion in cash and investments. Borrowing is at $2.26 billion up a billion dollars from June 2012. Current assets are well in excess of current liabilities by 3 to 1 and equity stands at a strong $9.6 billion.

Longer term | Seprod has never been one of those sexy companies but it has done remarkably well since listing back in the 1990s. It appears that for 2014 and beyond a lot is being predicated on the fortunes of the sugar operations in St Thomas where the target for sugar production is the processing of 300,000 tonnes of canes that should work out to around 25,000 tonnes of sugar. Management indicates that the expanded canes farms are already planted and the production should be coming in the 2014 crop. The group acquired Bowden Estates with 3,000 acres along with another property in the area and lands that were in bananas have now been planted out in canes. Management states that the sugar company is critical to them as a foreign exchange earner that can supply foreign currencies for the group when needed.

Related posts | Seprod’s dividend consideration | What’s really up at Seprod?