Exports push Jamaican Teas’ profit

A strong 70.6% increase in exports for the nine months to June helped in pushing profit at Jamaican Teas up to $75.3 million or 16 percent when compared to $64.8 million for the similar period of the prior year.

Export sales accounted for 52 percent of the total manufacturing sales for the latest quarter. The improvement in exports was driven mainly by increases in sales to the USA and Trinidad. Results for the June quarter were not as strong as the prior two quarters with an increase of 9.5 percent to $24 million as local sales slipped marginally compared to $22 million in the comparative period in 2012. While the growth in profit for the year may not appear impressive, the quality is far better as there was a large $13 million swing in earnings reported from gains on investments in 2012 resulting from a $10 million gain in 2012. While there was a $3 million loss this year, the net amount is partially offset by a $5 million gain from exchange rate movement.

The group recorded improvement in sales for the first nine months of the financial year, increasing by 34.5 percent to $783 million versus $582 million in the prior year. Improved sales was due to healthy increases in both export and supermarket sales, including the newest supermarket in Sav-La-mar, which was acquired by the company in March 2012.

The supermarkets also contributed to the bottom-line improvements which helped the improvement in revenues and profits. The results do not yet reflect sales from the completed real estate development which the group expect to be reflected in the final quarter of the fiscal year in September.

Image from Behance.net

Image from Behance.net

Associated company | The company’s jointly owned supermarket in Montego Bay, continues to show improvement but has not shown profit to date. Sales in the quarter rose 11% above the similar period of 2012. Management stated, “We enjoyed an encouraging improvement in sales since the start of the quarter pushing us closer to a break even position. Our share of the loss is $2 million in the latest quarter which includes an adjustment of $640,000 to deferred tax asset to reflect the reduction in tax rate from 33 1/3 percent.”

Investment | The company has short and long term investments of $142 million which includes $76 million of quoted equities.

Going forward | There are good indications that the final quarter should be better than that for 2012. In the 2012 final quarter, a large an impairment loss on investments of $9.3 million had to be made. In this year, the situation might swing in the other direction with the booking of the sales of the apartments. Beyond the September year end, the purchase of a property in St. Thomas should start to contribute to profits from the housing development for 72 two-bedroom single family homes.

Regarding another property purchase, management reported that, “The company will be moving the manufacturing operations to a new facility by the end of 2013, it has adequate space for our operations now and for the foreseeable future. While there may be no savings from this move, it is not expected to cost more than the current rental for the existing space. Ownership will result in savings going forward as inflation drives up rental rates.”

Financial position |The group continues to maintain a healthy financial position with good cash flows, adequate bank credit facilities and investments. Receivables increased by $41 million, which is due to a significant increase in exports that have longer credit terms. Management further stated that, “All the short and long term loans will be cleared subsequent to the quarter end from longer term loans and proceeds from the sale of the apartments. The company recently announced plans to issue $200 million of Corporate Bonds with attractive features for the investor including the fact that interest will be paid monthly and will be traded on the Jamaica Stock Exchange. The funds will be used to pay off more expensive debt and assist with funding our next real estate development. We have also obtained medium term financing from Bank of Nova Scotia for funding of the Bell Road property acquisition.”

Related posts | Jamaican Teas expands property arm | Jamaican Teas buys property | Profits up 19% at Jamaican Teas | Is the real estate market bullish?

Blue Power profit up 20%

Blue Power reported profits for the quarter ending June 2013 of $30 million compared to $25 million in the same period last year, an increase of 20% and earnings per stock unit moved from 43 cents to 53 cents in the quarter, an improvement of 23%. While the growth is not bad, the operation was not firing on all cylinders as the increase came totally from the Lumber Depot division which contributed $18 million, improving by 34% over the same period in the previous year, while the Blue Power division added $12 million which was an improvement of 5% over the first quarter of 2012.

Combined sales were $246 million compared to $233 million for the same period last year, an increase of $13 million or just 6% much less than the increase in profit. The Lumber Depot division achieved sales of $175 million versus $154 million the previous year, an improvement of 14% while the Blue Power soap division moved down to $70 million from $79 million for a decrease of 11%. It was not only increased revenues which helped to grow profit for the quarter. Administrative cost was down from $33 million in 2012 to $27.9 million due to a write back of doubtful debt that was made in the last fiscal year to April and non-accrual of certain expense that was made in 2012 but not repeated in this latest quarter. Also, other income almost doubled from $2.2 million to $4.26 million.

BluePower150x150The chairman Dhiru Tanna, in a release with the quarterly report stated that “we are pleased that despite the very challenging economic circumstances facing the country we were able to achieve an improvement in the overall performance. During the quarter, the Blue Power soap division faced serious competition in the market place with wholesalers and distributors shaving their prices significantly to reduce inventories. As a result, our ability to adjust prices in keeping with the exchange rate changes was seriously hampered and our sales actually declined. We have taken steps to offer more vendor-friendly packaging as well as significant promotions which we hope will reverse the trend.”

He went on to say, “We continue to take advantage of our cash position to acquire inventory for resale at advantageous prices which is the main reason for the increase experienced in this category on the balance sheet. Our analysis indicates that this approach is essential to remain competitive in a very stagnant market.”

Finances | Since the April year end, cash has increased to $153 million from $145 million but inventories are up to $198 million from $176.85 million. Accounts receivables has remained flat at $69 million. Amounts due to creditors amounted to $88 million the same level as in April. Equity capital amounted to $375 million and there is no longer any loan capital being used.

Insider call | Blue Power is an IC Insider Buy Rated stock.

Related Posts | Blue Power dividend | Blue Powered huge profit increase

JSE Insider trades

Jamaica Producers Group Limited advised that a director purchased a total of 500,000 shares during the period August 14 – 15, 2013.

National Commercial Bank Jamaica advised that a related party sold 379,500 of the company’s shares on August 13, 2013.

Mayberry Investments advised that a related party bought 9,013 of the company’s shares on August 16, 2013, the company also advised that a related party purchased a total of 27,472 of the shares during the period August 7 – 9, 2013.

Jamaica Money Market Brokers advised that a related party sold 300,000 JMMB shares on August 19, 2013 and another related party sold a total of 9,513,500 JMMB shares on August 15, 2013.

Image courtesy of Photokanok/FreeDigitalPhotos.net

Bolt won but he could still lose

There is no doubt about it! Usain Bolt is a great sprinter and based on his feats at the just concluded World Championships in Moscow, there are none close to him. However, his winning form on the track is yet to be transferred to his investment portfolio.

Well, that may be a broad statement but if the performance of his investment in KLE Group is anything to go by, he may lose all or most of his investment in the venture that we estimate is close to quarter of a million US dollars.

How did we get to this number? | When KLE went public last year, the prospectus indicated that 3,243,000 shares (“the Bolt Shares”) were reserved for Sherwood Holdings Limited, a company incorporated in Jamaica and owned by Bolt. Bolt’s company should have purchased the additional shares at a discounted price of $2.77 per share, which would have taken Sherwood’s shareholdings in the KLE Group to 10 million units. However, there is no indication that his company took up the shares nor if Bolt himself bought them. At the end of June, the top 10 shareholdings in KLE showed Sherwood Holdings holding 6,757,000 shares, the same as before the public issue. At $3.70 per share, the IPO price the public was asked to pay, his investment is valued at about US$250,000 dollars.

KLE_bannerPoor performance | When KLE Group came to the market last year, its broker defended what many others considered to be a highly overpriced and extremely risky investment. Once again, the KLE Group has reported lousy results with a worsened loss position in the June quarter and a year-to-date loss of $36 million for the six months in 2013 when compared to a $9 million loss for the same period last year.

In the June quarter, the Group chalked up a loss of $18.5 million compared to just $2.8 million in 2012. Although revenues climbed to $84.7 million in the quarter, up from $72 million in 2012, a $24 million jump in administrative expenses killed any hope of a bottom-line improvement. Year to date, this line item is up $30 million over 2012, while revenues only increased by $15 million for the same period. Further aggravating the loss problem is interest cost, which remains relatively high despite raising fresh capital through the public issue.

It appears that most of the cash raised has been used to support the operating losses and to purchase fixed assets and property. Shareholders’ equity, which was $119 million at the end of December, is down to $83 million in June with interest bearing debt of $48 million. The group has burnt up a lot of cash with only $15 million left at the end of June. This not good news as losses seem set to continue. Also current liabilities are well in excess of current assets by almost 3 to 1 — an absolute no-no in business — even when income is mainly cash.

This one is not looking good at all. The stock price is down to $1.80 and is poised for more decline. Not good at all, for a stock that was issued at $3.70.

About the KLE Group | KLE‘s (Kingston Live Entertainment Group) first venture was the uber-chic Fiction Lounge launched in 2008 and located at the Marketplace in Kingston. In April 2011, Usain Bolt’s Tracks and Records opened its doors adjacent to the Fiction Lounge as a new addition to the Kingston restaurant and entertainment scene. Late in 2012, the company placed 27 million shares on the market, all of which were snapped up with lightening speed by investors. With the needed capital raised through the IPO, the KLE Group is to expand into other related ventures including a theme park and villa community on the north coast.

Related Posts | KLE Group — to buy or not?

Photo credit | www.deependdining.com

TTSE: PE Ratio green lights TCL

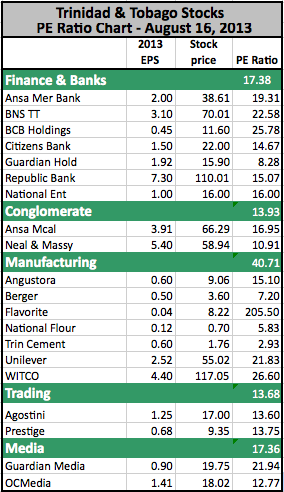
When we highlighted the stocks with the best potential for gains in the Trinidad Stock Market for the week ending June 28th, Trinidad Cement showed a potential to gain 900% with a PE of 3.17. and a stock price of 95 cents.

Since then, the stock has appreciated to $1.76 at August 16th, reducing the potential gain to 650%. Since July 1st, the stock is up 85% from when it traded at 95 cents. No other stock has appreciated close to that of TCL and the potential gains remain the same as was projected last week. TCL looks as if it will continue to increase in price over the coming week as the bid at the close on Friday was a bit higher than the last selling price of the stock.

The PE Chart continues to reflect good buying opportunities for a number of the stocks apart from TCL.

TTSE_PEAug19

Related Posts | Cement could be good for your pocket | TTSE: PE Ratio bargins abound

JMMB big bump in profits

JMMB reported a big jump in profits from ongoing operations for the first quarter to June this year with profit after tax and due to shareholders of J$753 million and earnings per share of 46 cents for the quarter ending June 2013 compared to $470 million in 2012. The investment bank now looks set to rake in profits of around $2 per share for the year to March 2014, which makes the stock cheap at the last selling price of $8.

Last year, JMMB acquired all the shares of Capital & Credit Group. The 2013 figures are a combination of both entities, unlike 2012 when there was only a few days results included of both. Hence, the comparison with each year’s figures may appear distorted. For the current year, net interest income grew to $1.178 billion from $984 million in 2012. Gains on securities trading jumped more than 100 percent to $674 million from $300 million. Overall, net operating income was up strongly to $2.06 billion from $1.39 billion. Operating expenses also moved up from $837 million to $1.13 billion, a 35 percent increase that is mostly related to the CCFG acquired entities. Last year’s results had a one-off gain of $1.57 billion resulting from the CCFG acquisition, which was a surplus of assets acquired over the purchase price.

Regionally, Dominican Republic contributed J$390.9 million to Group profits. The Trinidad & Tobago based IBL Group, an associated company, contributed a loss of J$25.5 million due mainly to additional provisioning for loans. The Group has already stated that they have agreed to acquire the shares held by the other shareholder in the bank.

jmmbGrouplogo150x150Shareholders’ equity stands at $18.7 billion at the end of June and the group has total assets under management of $175.5 billion and increase of $20 billion since last year June, a growth of 14 percent. JMMB has placed focus on lending with loans having increased by 17 percent to $12 billion since March or 69 percent annualised. While loans are a relatively small part of the assets, it could be one of the more profitable areas if lending is done smartly to minimize losses. If growth continues at the current pace, in a few years it could be a major part of the group’s assets and add much to profits. More importantly, when the IBL shares are fully owned the total loans will effective increase sharply over what is being shown now.

For the quarter, banking and related services only contributed revenues of $487 million out of a total revenues of $3.77 billion and profit of only $77 million.

JMMB is a financial conglomerate with the principal activities are securities brokering, securities trading, merchant banking, dealing in money market instruments, operating a foreign exchange cambio and managing funds on behalf of clients.

Insider call | JMMB is an IC Insider Buy Rated stock.

Related Posts | JMMB’s rebranding | JMMB posts improved profit | JMMB to acquire 100% of IBL

JMMB to raise $750M

Jamaica Money Market Brokers is going to the public to raise $750 million in August by way of two sets of preference shares. The investment banking house lodged a prospectus with the Jamaica Stock Exchange (JSE) today with the offer.

The offer which opens on Wednesday, August 21 is for 313 million 7.5% preference shares maturing in August 30, 2018 at an issue price of $2 and a 7.25% preference share priced at $2.50 for 50 million units. The shares will be listed on the JSE. Dividends will be paid monthly on both issues.

JMMB is a listed company on the JSE as well as on the Trinidad & Tobago Stock Exchange. It currently has two preference shares listed on the JSE.

In it’s latest audited accounts to March this year JMMB reported profits of $3.85 billion after tax. The June first quarter results is slated for release this week.

Related posts | JMMB posts improved profit | JMMB’s rebranding | JMMB to acquire 100% of IBL

Profits up at Cargo Handlers

The latest quarterly results for Cargo Handlers may not look impressive when compared with the 2012 figures, but the numbers actually beat last year’s by nearly 16 percent when it hit $22.6 million for the quarter to June. For the nine months to June, profits which are at $63.6 million, are up 29.6 percent over the $49 million generated in 2012. Revenues from the main operations is up to $115 million for the nine months from $95 million in 2012, a gain of 21.6 percent and for the quarter to June, revenues are $40 million from $34.6 million in 2012, a gain of 15.6 percent, slower than the nine months growth.

Earnings per share is 54 cents for the quarter and $1.53 year to date and looks as if earnings for the full year will top $2. For 2012, earnings came in at $1.73 per share. While profits are up, this company seems more like a dividend stock than one for great capital gains. Nevertheless, with the price around $13 for the stock and earnings in the $2 range there is room for price appreciation.

Administrative expenses didn’t move by much, from $6.16 million to $6.4 million year to date but other operating expenses are up 19 percent in the latest quarter and for the nine months, the increase was 29.4 percent.

At end of June, cash stood at $89 million, current assets at $123 million and current liabilities at just $20 million and is well covered. Shareholders’ equity stands at $108 million.

Dividend | Last year the company paid $1 per share in two dividends. So far they have made a dividend payment of $1 earlier in the year. No more should be expected, but you will never know.

Cargo Handlers operates out of Montego Bay and carries out stevedoring services.

Related Posts | Cargo Handlers profits up 38%

Palace triples profit

Palace Amusement Company has reported profits that has more than tripled the results for the June quarter last year. Profit after tax came in at $26.6 million in the latest quarter versus $9 million in June 2012.

The company made $18.5 million for the 12 months to June 2013, up from the $14.7 million made for the year to June 2012, a 26 percent increase. The results completely erased the poor March quarter when revenues fell sharply and took profits with it. Year to date revenues are up to $862 million coming from $842 million in 2012 and in the last quarter revenues were $278 million versus $243 million in the same quarter in 2012 for a 14 percent increase, much better than the 2 percent increase for the entire year.

March quarter | Profit for the March quarter fell sharply compared to the March 2012 quarter to a loss of $22 million from $2.66 million in 2012. IC Insider reported in our analysis of the first quarter, that the fall in revenues was due primarily to a shift in a particular brand of film, which would normally be shown in the March quarter, but was shifted to the June quarter. The latest results are confirmation of this.

In the three months to March, operating cost fell by $16 million or 10 percent, while administrative cost was up 11 percent to $34 million. In the 2012 quarter, Palace generated income of $193.5 million, this was down 21 percent or $41 million to $152.3 million in the 2013 quarter. The fall-off in 2013 comes against the background of the company introducing a new product, the showing of live operas on screen and an encore season of opera’s best in the summer. Without them, revenues would have been lower.

June quarter | Gross margin climbed in the June quarter compared with 2012, but year to date, it just barely moved. Administrative cost was kept under raps for the year, moving from $138 million to $147 million, less than 6 percent but for the latest quarter it is up by a much larger 23 percent.

Palace had cash funds and investments of $124 million million at the end of the financial year, which is up from $80 million last year. Working capital would appear to be tight with current assets at $195 million and current liabilities of $173 million. Loans amount to $40 million with equity of $300 million.

Related posts | Palace’s $22m 3rd Qtr hit

Photo via: www.PalaceAmusement.com

Salada June profits down

Salada Foods, producers of Mountain Peak instant coffee, reports lower profit in the June quarter, a continuation of lower profit in the March quarter versus the same periods last year. Profit came in at $42 million after tax for the latest quarter and $95.4 million year to date versus $52.49 million and $106.6 million respectively to June. Profit for the March quarter was $29.3 million, down from $35 million in 2012.

The lower profits for the March 2013 quarter occurred as sales were lower, emanating from price reductions in the quarter implemented to stimulate sales and market penetration as well as increased cost associated with the new brands being produced by Mountain Peak Ltd. The reduction resulted in sales in monetary terms for the quarter falling 15.6 percent to $141 million, a $26 million decline. Sales for the June quarter were down to $198 million compared to $246 million in 2012, off 21 percent and year to date, $491 million and $532 million in 2012, an 8 percent decline. The level of sales would have been expected to result in worse performance in profits, but better margins helped negate the effects of the fall off.

IC Insider has been reliably advised that the reduced sales is not an indication that demand by consumers have declined but it is more tied to excess inventory being held in the trade that is affecting demand directly from Salada. Translated, sales in the past was inflated to the extent that the trade was building up inventories and the needed adjustment is now taking place.

CoffeeTrade280x150Expenses | Selling and Promotional expenses rose 29 percent to $15.6 million in the quarter and 24 percent to $29.6million. Administrative expenses rose 24 percent to $25.3 million in the quarter and 23 percent to $75.4 million for the six month.

The increase is attributed primarily with the commencement of operations for Mountain Peak Foods Ltd under which the acquired Roberts brands of processed condiments are being processed and marketed. In addition to this brand, the group is marketing under the Mountain Peak brand as well.

Finances | Salada is clearly very conservatively managed, as can be seen from some of the financial ratios. The company has a large current asset ratio of 9 to 1, well above accepted norms, with cash and investments of $207 million. There was no interest bearing debt on the books, and equity was a high $711 million.

The earnings for the year to September should exceed a $1.40 per share. This could mean that the stock may not have much room to climb in the current market environment. Interest ought to be focusing on 2014 when the new products being produced by the Mountain Peak boost sales and hopefully profit.  There are limited supplies of the company’s stocks to trade, so anything is possible with the stock price if demand comes in for them.

Related Post | Salada’s stock price may be stuck