CPJ’s big jump in profits

With net profit for the last quarter of US$1.4 million from revenues of US$19.2 million, Caribbean Producers Jamaica (CPJ)‘s June profit surpassed the previous quarter’s results by 188 percent. As a result, Earnings per Stock increased to US.13 cents compared to US.4 cents the previous year.

Management stated their release that fourth quarter performed ahead of the company’s expectations in terms of projected sales thereby contributing to the significant increase in net profit. Revenue was up 9 percent in the quarter from US$17.7 million in the corresponding period last year. This, management said, “was the result of increased production and efficiency of the manufacturing division, the consumer support of CPJ Market Kingston and Cru Bar. In addition, the hotel sector remained buoyant during the quarter as high occupancies were enjoyed throughout the period notwithstanding the closure of major hotel properties.” The growth in revenues of 9 percent for the quarter is in contrast with of just 2.7 percent for the year.

The company reported achieving a 15 percent increase on Gross Operating Profit of US$5.4 million, a significant improvement when compared to the corresponding period last year of US$4.6 million representing 28 percent and 26.4 percent gross profit margins respectively for the last quarter.

CPJWineBottlesFreeDigi150x150In spite of the big jump in the quarterly profit, net profit for year increased by just 5 percent to US$3.2 million compared to US$3.04 million at June 2012.  Earnings per stock unit moved to USD 0.29 cents. The profit was realised from revenues for the year of US$69.4 million versus US$67.5 million over the corresponding period last year, an increase of US$1.9 million or 2.7 percent. For the year, gross profit increased from US$17.4 million to US$19.9 million as operating cost fell from US$50 million to US$49.5 million. Regardless, it is the results of the June quarter that is of most import as it points the way forward for profits.

CPJ reports its results in US dollars, as such exchange rate changes are not readily visible but some of the increased profits in the quarter would be due to lower cost of some local inputs making the result for the quarter larger than normal. That may well be true but sales in the period actually rose in real terms thus giving a good glimpse of possibly strong growth in the profits for 2014. The number suggests that the 2014 earnings per share should be in US$0.50 range as they ramp up sales form the manufacturing operations.

Selling and administrative expenses increased by 16 percent for the year to US$13.47 million from US$11.6 million and interest cost rose nearly 17 percent to US$1.8 million. The depreciation charge of US$1.5 million increased by US$469 thousand or 42 percent compared to US$1.1 million in the corresponding period in 2012 representing the capital expenditure for the manufacturing and operational assets set up this year.

Too much debt | At the end of June, shareholder’s equity stood at US$13 million but borrowings was at $24.8 billion, which is far too risky. Current assets that stand at US$32 million including US$3 million in cash is well in excess of current liabilities of $15 million, but short term loans amounts to over US$9 million. Cash flow for the past year came in at US$5 million and this should climb in the new year if the last quarter numbers are indicative of the 2o14 fiscal results.

Insider call | The company seems to be benefiting from the expansion that it undertook after the initial public offer (IPO) and the promise of strong profits that investors gleaned at the time of the offer does exist. IC Insider considers this stock as Buy Rated but is concerned about the high debt load, which is well beyond acceptable levels.

Related posts | Caribbean Producers Profit down | Debt swap for Caribbean Producers|  CPJ denies major customs breach

Image courtesy of Simon Howden/FreeDigitalPhotos.net.

TTSE: 3 major changes in PE rankings

There have been three major changes in the Trinidad stock market‘s PE Ratio chart due to price movements this week.

Trinidad Cement (TCL) gained 42 percent in the week and more than 200 percent since May. Questions may be asked as to how much further it can go but the PE ratio chart still has the TCL stock as the one with the greatest potential for growth in the market. It has more room to run before it is fully valued based on this year’s company profit performance so it’s still worth either buying or holding on to.

TTSE_PE+Aug30Neal and Massy has come down relatively sharply in price, as has Guardian Holdings. The declines have made them more attractive buys even though Guardian seem like it has further to fall before it bottoms.

Related posts | TTSE: TCL is hot | TTSE: Neal & Massy drops $2.93 | Guardian ongoing profits up 29%

Image courtesy of Jeroen Van Oostrom/FreeDigitalPhotos.net

Scotia Group moves up in spite of NDX

Profits for the nine months to July this year are up for one for the Jamaica’s largest financial institutions even as the debt exchange that the banking group engaged in during the April quarter knocked millions out of profits.

Scotia Group Jamaica reported net income of $3.06 billion for the third quarter ended July, $127 million above the previous quarter ended April and $468 million above the quarter ended July, 2012. For the nine months end to July, net profit was $8.7 billion compared to $7.95 billion for the same period last year. Earnings per share for the nine months was $2.70 compared to $2.45 for the same period last year.

Revenues | Profit flowed from operating income, comprising net interest income after impairment losses and including other revenue of $25.5 billion, an increase of $2.2 billion or 9.32 percent relative to the prior year. Overall total operating income, which is net of interest expenses and loan impairment losses amounted to $3.14 billion in the quarter, a strong 36.6 percent higher than in the similar period in 2012 and $8.6 billion year to date, 24.6 percent higher than in 2012. The year to date figure is affected by the loss picked up with the debt exchange. The instability of the Jamaican dollar made a good contribution to the group’s fortunes as they generated significant gains from this area for the year-to-date but not as much in the latest quarter.

Net interest income | Net interest income after impairment losses for the period was $16.86 billion, up $470 million or 2.87 percent when compared to the same period last year. The Group continues to report strong growth in loan and deposit volumes over the period. Loan loss expense increased by $215 million when compared with prior year, reflecting growth in the loan portfolio and the impact of continued contraction in the economy, especially on our retail customers.

scotiabanklogo150x150Other revenues | Other revenues for the nine months was $8.6 billion, up $1.7 billion or 24.6 percent when compared with prior year. This was due primarily to increased insurance revenue and fee income, gains on securities trading, as well as higher gains on our foreign currency trading and investments. Insurance premium grew to $1.9 billion in the year to date from $1.6 billion in 2012 and foreign exchange trading gains from $1 billion to $2 billion. Net fee income moved up for the same period from $3.95 billion to $4.32 billion. The gains from Foreign exchange is unlikely to continue at the pace seen to date in the next fiscal year.

Expenses | Operating expenses are up 18 percent in the July quarter over that of the similar 2012 quarter and 14.6 percent for the nine months over 2012, which are much slower than that of net revenues. While property cost was pretty subdued at 3.6 percent increase for the year to date with the quarterly figure increasing around the same level, labour cost jumped by 14.5 percent for the nine months and a big 23.8 percent for the quarter over 2012. Other operating cost, which amounted to $1.62 billion in the quarter, jumped 16.2 percent over 2012 and 19.9 percent for the nine months to July to $4.9 billion.

Loans | loans increased to $131 billion, an $8.5 billion or 7 percent increase and a $4 billion increase over April’s amount.  Non-performing loans (NPLs) at July, 2013 totalled $4.7 billion, reflecting an increase of $470 million from prior year and a decrease of $330 million from the previous quarter ended April, 2013 as recoveries increased in the quarter. The increase year over year is in line with the growth in the loan portfolio. Total NPLs now represent 3.51 percent of total gross loans compared to 3.58 percent last year and 3.88 percent as at April 30, 2013. The Group’s aggregate loan loss provision as at July, 2013 was $4.8 billion, representing 100 percent coverage of the total non-performing loans. For most of these doubtful loans, the Group holds meaningful collateral.

Balance sheet | Total assets increased year over year by $40 billion or 11.56 percent to $389 billion as at July. Cash resources increased by $29 billion to $77.7 billion primarily as a result of the growth in deposits and placing the group in a very liquid position.

Total customer liabilities (deposits, repo liabilities and policyholder’s funds) grew to $299 billion, an increase of $34 billion over last year. This growth was mainly reflected in the deposit portfolio as the group management stated that they “continued to acquire new customers and see increased balances from existing customers”. Total shareholders’ equity grew to $70.9 billion, $4.2 billion above prior year.

Insider call | Scotia is unlikely to be a major trailblazer as far as rapid profit growth is concerned with the Jamaican  economy in the state that it is in now. However, the earnings are such and the stock price is at a low $20, that it is very good buy for dividend income with a yield around 7.5 percent and capital gains ahead. An investment in this stock could double ones money over the next twelve months. Scotia Bank is now a IC Insider Buy Rated stock.

Related posts | Scotia: No change in dividends | Scotiabank wins Service Award | Scotia Group’s profit surprise

Q3 profits up at Scotia Investments

Scotia Investments Jamaica’s profit for the quarter to July this year was $562 million or 51 percent above the $372 million earned in the previous quarter and 18 percent above the $477 million made in the 2012 quarter. For the nine months ended July 31, 2013, net profit was $1.42 billion, down $90 million or 6 percent when compared to the same period last year. Earnings per share for July quarter was $1.33 compared to $1.13 in 2012. For the nine months earnings per share was $3.36 compared to $3.57 for the same period last year.

Revenues | Operating Income comprising net interest revenue and other income for the quarter amounted $1.178 billion, up $228 million or 25 percent from the $949 million recorded for the previous quarter. Operating Income, came out at $3.236 billion for the nine months period, up $142 million or 5 percent above the $3.094 billion for the same period 2012.

The company has recovered from the negative impact of the NDX on net interest income as net interest income for the quarter was $692 million, $66 million or 10 percent above the results of the previous quarter. Net interest income after impairment losses for the nine months period was $2.081 billion, down $33 million or 2 percent when compared to the same period the year before.

scotiabanklogo150x150Non-Interest Income | Non-interest income, inclusive of fees, securities trading gains and net foreign exchange trading income was $1.155 billion for the period, up $175 million or 18 percent compared to the same period last year and $485 million for the quarter, up $162 million or 50 percent over the $324 million recorded last quarter. The major factors contributed to the improvement is net fees and commission as there was a $69 million jump in this category in the quarter and $183 million year to date, net foreign exchange gain dropped sharply in the quarter from the prior quarter to $30 million, which was slightly lower than the $33 million generated in 2012. Year-to-date, the increase is $105 million with $100 million of than being generated in the April quarter.

Gains from securities trading climbed to $197 million in the July quarter compared to $78 million in July 2012 and year to July income amounted to $273 million versus $293 million. The difference reflect the impact of losses sustained when the company engaged in the debt swap with the Government of Jamaica resulting in a loss on investments due to receiving a lower value for bonds held.

Expenses| Surprisingly, they were able to hold expenses below the amount in the prior quarter to $366 million, down from $418 million in the April quarter but up on the $327 million for 2012. For the nine months expenses climbed sharply to $1.2 billion versus $984 million in 2012.

Assets | Total assets of $72.6 billion remained relatively flat year over year. “There was a $1 billion or 1.3 percent reduction relative to the year ended October 31, 2012, which is consistent with our strategic initiative to focus on growing our off-balance sheet portfolios,” the company stated. Meanwhile, Shareholder’s Equity amounted $11 billion.

Off balance sheet | Assets under management, including the Company’s custody book, were $115.3 billion as at the end of the quarter, up $14.2 billion or 14 percent above the same period last year and up $5.8 billion or 5.3 percent over the previous quarter. The growth was driven by increased net asset values in the managed funds.

Related posts | Scotia: No change in dividends | Scotia Investments one time dent

TCL up 209% in two months

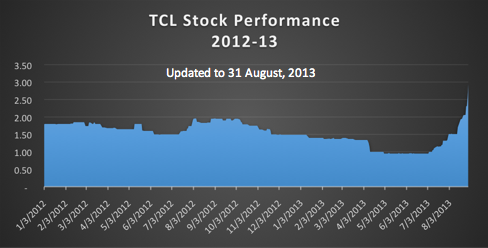
Update to our post of Aug 27th, 2013 | In early July we told our readers “Cement was good for your pocket“. While we don’t know many took our advice seriously, we do know is that there has been quite a bit of buying of this Trinidad based company’s shares driving the price from 94 cents up to $2.94 at the close of trading on Friday. Not bad for a two months investment!

The good news is that our estimates suggest that it not over with prospects for more gains to come as the stock rallies to better align its value with the overall market.

Related posts | TTSE: 3 major changes in PE rankings | Cement could be good for your pocket

UpdatedTCLCementgraph+content

Original post dated 27th August 2013 | We called it! TCL stock gains 115%

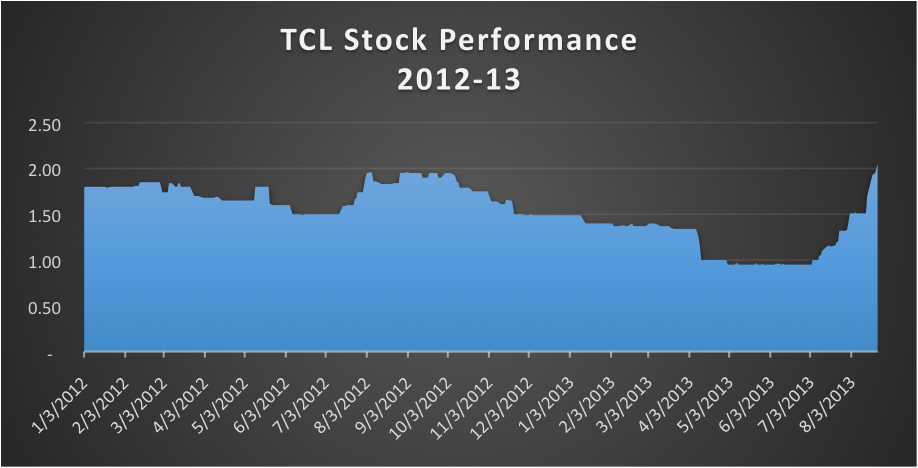
You read right! Trinidad Cement Limited stock price has gained 115% since IC Insider made to call out to buy at the beginning of July when the price was at 95 cents. It has since risen to $2.05 in almost 2 months. Not a bad pay day at all!

It’s not too late for you to make money on this fast moving stock! From all indications the stock still has lots of room to grow with the price on Monday, August 26 at $2.06 and the bid at $2.13 on the Trinidad Stock Exchange.

The main objective of IC Insider is to provide readers with opportunities not only make money, but to earn above average returns and avoid losses. To view our latest Buy Rated stocks, click here.

TCLGrowth

Consolidated Bakeries hiked profit

Consolidated Bakeries is reporting strong growth in profit in the second quarter, a continuation of increased profits experienced in the first quarter of the year. The strong growth is as a result of robust revenue growth in both quarters of the year. Revenue for the six months increased by 30.69 percent to reach $329 million and for the quarter by 40.46 percent over the same periods last year to reach $157 million. “The increases reflect real growth in volumes across our key items and primarily a result of activities in distribution and market programmes,” management stated.

Profit after corporation taxes which increased 172 percent in the first quarter more than tripled in the second quarter moving from $4 million in 2012 to $12 million for the first six months and net profit went up by 191 percent to $24 million. Helping with the improvement was a 55 percent gross profit margin, a big improvement over the 42 percent in the first quarter last year and year to date margin is 56.5 percent versus 52 percent in 2012. Operating expenses climbed sharply by 53 percent in the quarter and 31 percent for the six months period.

Consolidated_Purity150x150The improvement in revenues and profit is impressive. The concern that exists is that the results for the six months to June last year showed impressive numbers but there were losses in the last half, thus reducing what appeared to be acceptable results. The second half of the year tends to be a bit weaker for sales and profits for bakeries. As such, the impressive profits seen in the six months may not match the results in the second half.

Working capital was in a healthy state with current assets of $169 million compared to $46 million in current liabilities. Inventories are low at $16 million and receivables at $57 million seems to be well under control. Shareholders’ equity is $495 million and debt financing of only $23 million.

Depending on how the second half pans out, the stock could show some appreciation in the next two quarters. Earnings per share is only 11 cents to June, so at best, the full year earnings will be around 20 cents. At this rate, it won’t cause investors to run and grab the stocks, even at the current trading price of $1.35.

Related Posts | Consolidated Bakeries’ Q1 Profits Up

Bread Loaf Image courtesy of dplanet/FreeDigitalPhotos.net

Q2 profit up strongly at Sagicor

The Sagicor Jamaica Group made big strides in the second quarter with a 39 percent increase in the net profits of $1.56 billion versus reported profits for 2012 of $1.12 billion. It also represents a major recovery over the ‘NDXed’ first quarter results of only $620 million. Earnings per share came out at 42 cents, annualized $1.68.

“The improved results in second quarter reflect continued good new business and a higher pay-out of insurance benefits. We also recorded a “one-time” charge of $120 million for an adverse Privy Council judgment relating to a Cayman Islands legal claim. In first quarter we had the impact of the National Debt Exchange and Private Debt Exchange (NDX programme) which resulted in “one-time” realized capital losses of $1.2 billion,” management said in a release accompanying the results. Profit of $2.18 billion was realised for the six months to June against $2.60 billion in 2012 attributable to stockholders. Earnings per stock amounts to 58 cents, while in 2012 it amounted to 69 cents for the six months. Total Comprehensive Income including, net profit for the period and movements in reserves held in Equity, was $1.33 billion compared to $3 billion for 2012.

“Unrealized fair value losses on available for-sale securities exceeded unrealized foreign exchange gains. The unrealized fair value losses emerged from lower bond prices as interest rates rose, especially USA corporate bonds. Following the NDX programme we now carry a large portion of GOJ securities with lower market values, lower coupon rates and extended tenors” the report to shareholders stated.

Sagicor150x150Revenues | Revenue of $15.24 billion was above prior year by 1 percent. With the effect of the NDX programme excluded, Revenue would have been up about 9 percent. Net Premium Income, in aggregate, was 4 percent more than that for 2012. The Individual lines of business earned premiums were up by 9 percent while Group Insurance and Annuity premiums were level with prior year. There was good new business across all lines. Investment income, before interest expense and capital gains was higher than in the prior year by 1 percent, reflecting lower coupons from March on some GOJ bonds management indicated to shareholders.

Administrative expenses of $3.73 billion were 10 percent more than in 2012 but the increase in the June quarter is 12.8 percent. The increase would have be only 6 percent if the $120 million legal claim is excluded. The increased expenses reflect mainly higher compensation costs, the $120 million legal claim paid in June 2013 and higher loan loss provisions in the Banking Group.

Stockholders’ Equity as at June 2013 was $33.21 billion, compared to $32.64 billion as at December 2012. Significant unrealized fair value losses were also recorded in June to Investments Reserves in Comprehensive Income, as bond prices fell with rising interest rates, especially USA corporate bonds. Total assets climbed to $185 billion from $175 in December last year as the group continues to grow moderately.

Insider call  | At an annualised earnings of $1.68 per share generated in the latest quarter and with a stock price of just $8.20, the stock is undervalued and is accorded a Buy Rated rating.

Related posts | Sagicor undervalued despite $B NDX hit | Sagicor Investments get big NDX hit

Dolphin continues to grow

Dolphin Cove reported improved profit for the six months to June of $221 million compared to $195 million in 2012, an increase of 13 percent and for the three months to June, $103 million versus $84 million, a 22.6 percent gain. Total revenue for the six months to June was $787 million versus $706 million in June 2012, an 11 percent increase and $393 million for the June quarter compared to the previous year’s $344 million for a 14 percent change.

Gross profit rose 11 percent year to date to $696 million and was up 13 percent in the recent quarter. Administrative cost rose faster than revenues 20.6 percent for the six months but 25 percent in the June quarter. Interest cost declined from $11 million in the six months last year to just $1 million for 2013.

Both revenues and profits would have been negatively affected by the slowdown in visitor arrivals this year and would have slowed growth somewhat.

dolphin-cove280X150The consolidated financial position of the Group is strong, showing a healthy net current assets over current liabilities of $252 million position with cash funds and investments of $205 million, but the position is boosted by increased borrowing for capital spend for fixed assets and new dolphins with $174 million spent on animals in the last twelve months in preparation for expansion. This is in keeping with the company’s plan to open and operate additional parks in other Caribbean countries where they acquired real estate and additional dolphins for the attractions.

Notwithstanding the investment in fixed assets, the company paid dividends (20 cents per share) during the six month period.

The stock is priced at $9 each and carries a PE of more than 10 times this year’s estimated earnings, which should be around 80 cents per share. Based on the value, the stock would be Hold Rated.

Related posts | Growth slows for Dolphin | Dividends to come

Image courtesy of Bill Longshaw/FreeDigitalPhotos.net

Scotia: No change in dividends

The two Scotia companies announced dividend payments today with both payments scheduled for October.

Scotia Group Jamaica approved a third interim dividend of 40 cents per stock unit payable on October 9, 2013, to stockholders on record at September 18, 2013.

Scotia Investments approved an interim dividend of 45 cents per stock unit, payable on October 9, 2013, to stockholders on record as at September 18, 2013. The dividends to be paid represent a continuation of their dividend policy and are the same amounts that they have been paying against this year’s profits since the start of this year. Both companies raised the pay out in January this year from 37 cents for Scotia Group and from 40 cents for Scotia Investments.

scotiabanklogo150x150Dividend announcement from Scotia published 28th August, 2013 | The Board of Directors of Scotia Group Jamaica and Scotia Investments will consider a dividend payment at a meeting to be held on August 29, 2013. It is expected that the two entities will retain the payments they have been making for the year to date of 40 cent per share in the case of Scotia Group and 45 cents in the case of Scotia Investments.

Both companies are expected to release nine months results to the end of July on Thursday, August 29 along with teh announcement of the dividends. Investors will be watching Scotia Group numbers to get an indication as to the timing for investment purposes and possibly the state of the financial market.

For Scotia Investments, the results will determine if investors in Trinidad will continue their strong interest in the stock. A return to reasonable growth in profits could see increased interest as the stocks dividend yield will be very attractive for investors in the Twin Islands.

In the April quarter in spite of a $397 million hit from the debt swap of Government of Jamaica instruments, Scotia Group was able to report 92 cents profit after tax, with the July quarter likely to recover from the negative effect from the debt swap, which resulted in a lower rate on the investment instruments. The baking group could post higher earnings in the latest quarter, but a lot will depend on how much provision have been made for non-performing loans and how much has been made from exchange rate movement of the Jamaican dollar.

Related Posts | Scotia Investments one time dent | Scotia Group’s profit surprise

Producers profits up, is it time to buy?

Directors of Jamaica Producers have purchased quite a bit of their company’s shares in recent months as the fortunes of the company seem to be on the improve. However, we ask the question: Is Producers right for the average investor?

The answer: Not at this time. With the stock price at the $18 level and the net book value placed at $29 per share, the gap is significant and earnings have not reached the level for the wider investing public to accord the stock a higher value, regardless of what the Directors’ buying actions may suggest.

In the just released company results, Producers reported a jump in profits by 42 percent to $158.5 million for the six months to June 2013 relative to the same period last year, and was up 59 percent for the latest quarter to June, over the June 2012 quarter to $73 million. For the six months, revenues increased by 6 percent to $3.7 billion and 5 percent to $1.84 billion for the June quarter over the same periods in 2012.

JP Europe | Revenues increased by 8 percent to $1.34 billion for the European division resulting in a 20 percent increase in pre-tax profits of $56.5 million for the second quarter and $116.4 million for the first half of 2013, more than doubling the result for the comparative six months of 2012. The turnaround in this area resulted from moderate improvement in the economies within the region, exchange rate movements between the Jamaican dollar and the Euro as well as expansion of sales to new areas within the EEC.

jamaica_producers+Tropicallogo150x150JP Tropical | Pre-tax profits of $26.6 million for the second quarter increased by 105 percent from $12.9 million in the 2012 period, a turnaround relative to the first quarter 2013 loss of $54.8 million, which included one-off exceptional restructuring costs of $35.9 million. With very limited banana supply, total revenues for the JP Tropical Division for the second quarter were down by 3 percent relative to the 2012 second quarter and rose by 4 percent on the first quarter.

During the latter weeks of the six month period, production of bananas resumed on the farms in St. Mary, commencing the generating of income to help cover the cost of re-development and maintenance of the resuscitated banana farms, which had negatively affected JP Tropical Division’s previous results. With the return of banana production, the JP Tropical Division improved its pre-tax profits for the second quarter compared to both the first quarter of 2013 and the comparable period last year. The primary snack production facility in Jamaica has now returned to production having been closed since Hurricane Sandy in 2012.

The recent acquisitions and investments in our JP Tropical Division collectively made a positive contribution to the divisional performance and we expect them to be an increasingly important part of the division in the future. The primary focus for the Division going forward will be to grow revenues organically by taking advantage of our installed base of productive capacity.’

“Mavis Bank has had a strong first half with operational efficiency gains allowing the company to meet export targets” management stated. Tortuga had mixed results in the first half with improved performance in Jamaica and Barbados and weaker sales in the US and other Caribbean markets. Tortuga’s overall performance was also affected by the seasonality of the product which typically generates peak sales in the fourth quarter and the Caribbean winter tourist season.

Regarding the Mining Company Limited, a subsidiary in which they hold a 51 percent interest, the company stated, “It had a satisfactory performance in the first half driven by the quality of our output and reliability of our service. We are now taking steps to expand mining operations from our base in St. Mary by opening a facility in Clarendon to allow us to participate in the South Coast market.”

jamaica_producers+bananalogo150x150The group has borrowings of $1.2 billion, which was used in funding investment in some of the associated companies as it reduced the amount in cash funds and investments that the Group held prior to the major investments. Cash and short term now stands at $435 million and $558 million for longer term investment. Investment in associated and joint venture companies amounted to $2.75 billion with the bulk of it being in Kingston Wharves. Shareholders’ equity at the end of June amounts to $5.4 billion.

Related posts | Insider Trades |  Profits up at Jamaica Producers