Q3 profit jumps 40% at Medical Disposables

Profit after tax for the nine months to December last year fell 10.7 percent to $68 million at Medical Disposables, compared with $76 million in 2021. For the quarter, it rose from $37 million to $38. Profit after tax attributable to the company’s shareholders ended 2022 with $58 million, down 10.7 percent from $65 million in the previous year. For the quarter, it climbed 40 percent to $28 million after minority interest compared with $20 million in 2021.
Improved profit margins played a pivotal role in the company’s fortunes in the December quarter, with gross profit margin increasing from 26.8 percent in 2021 to 29 percent in 2022, helping to propel it to the most profitable quarter for the nine months of operations in 2022. Gross Profit margin for the nine months in 2022 increased to 27.26 percent from 25.85 percent in 2021.
Gross profit hit $273 million from sales of $941 million, up from $250 million from sales of $930 million in the second quarter to June. Gross profit for the December quarter improved by 16.6 percent or $39 million compared to the 2021 third quarter.
Sales for the third quarter grew by $66 million or 7.5 percent over the third quarter in 2021, moving from $875 million in the 2021 December quarter, driven by increased demand for pharmaceutical and consumer items, the report stated.
Sales increased by 10.8 percent or $270 million for the nine months to December 2022, to $2.76 billion from $2.49 billion in 2021 and delivered a 16.9 percent improvement in gross profit of $108 million to $753 million from $645 million in 2021.
Selling and administrative cost dipped in the December quarter, compared with the September quarter, to $78 million versus $83 million, while selling and distribution cost rose just $2 million to $114 million. Finance cost spoiled the party, jumping to $31 million from $28.5 million and “was due mainly to an overall upward adjustment in financing, particularly working capital. The increased usage of the working capital lines of credit was deemed necessary to hold greater levels of inventory in an effort to mitigate against any additional supply chain risks that could lead to further out-of-stock instances,” management stated in their report accompanying the Financials.
Medical Disposables traded at a new all-time high of $10.

“Out of stock issues continue to affect the Group’s profitability as suppliers are faced with global supply chain challenges within their operations. The availability of key speciality products such as vaccines and oncology medicines has become infrequent and inconsistent. Our internal estimates have tracked over $100 million in lost sales due to the shortages,” the company stated. That would translate to close to $30 million more in pretax profit.
The operations generated cash inflows of $109 million for the nine months, but working capital needs consumed it all as inventory rose sharply.
At the end of December, inventories increased by $360 million to $1.53 billion, up from $1.17 billion in December 2021. Receivables declined to $603 million at the end of December 2022 from $708 million at the end of 2021. Cash and bank balances rose to $128 from $72 million at the end of 2021. Loans due to lenders amount to $1.14 billion, up from $965 million at the end of 2021 and is just a bit less than shareholders’ equity, that stood at $1.17 billion compared with $1.07 billion at the end of 2021.
The profit for the nine months resulted in earnings per share of 11 cents for the quarter and 22 cents for the nine months.
The company’s focus is on organic growth and expansion from acquisitions where possible, in furtherance of this goal, management is placing a great deal of emphasis on staff retention and recruiting talented personnel to enhance its pool of above average talents. The initial impact will be increased staff costs that will be above the increased revenues, but that will pay good dividends in future years.
ICInsider.com projects earnings of 45 cents for the year and $1 for the fiscal year ending March 2024. At the last traded price of $4.85, the stock trades at 11 times this year’s earnings and five times that of 2024, suggesting much upside potential for the stock price, with the market average PE ratio now around 13 and with several priced above 15 times earnings.
Miraculous turnaround at Palace

After nearly three years in the doldrums and on life support, helped by a number of popular and well patronized movies, Palace Amusement surged back to life in the December 2022 quarter when it made the first quarterly profit since March 2020. The profit back then was $44 million from revenues of $255 million, with the latest results surpassing it and easing much of the pain and nervousness the company and its staff encountered over the past three years.

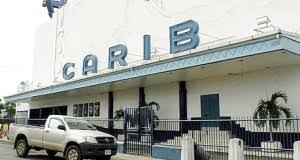
Carib Cinema, the flagship for Palace Amusement.

“The company staged three block-buster pictures in the same Quarter – Woman King, Black Panther 2: Wankanda Forever and Avatar 2: The Way of Water; Our patrons’ response was close to 215,000 visits in the Quarter and this helped to push the overall attendance at the end of the six months to over 80 percent of pre-pandemic numbers,” the company’s management stated in a report accompanying the financials.
Palace aced the December quarter with revenues of $486 million, up 222 percent from just $151 million in 2021 and $736 million for the half year, up 218 percent from a mere $232 million in 2021. Accumulated profit of $304 million at June 2019, melted away by $772 million of losses, to a deficit of $468 million up to September last year as revenues were lower than cost, but profit surged to $79 million in the December quarter from a massive loss of $112 million in 2021 and for the half year a profit of $25 million from a loss of $191 million in 2021.
While revenues surged over 200 percent, direct expenses rose a more modest 98 percent in the December quarter and 97 percent, year to date, helping to swell the profit for both periods, but administrative expenses fell from $75 million to $47 million in the quarter and from $104 million for the half year to $75 million. Finance cost rose from $12 million in the 2021 last quarter to $14 million and from $17 million to $28 million for the half year. Legal and professional fees is one of the major areas of cost reduction in the period, dropping from $44 million to just $2 million for the six months period.
Segment Results show revenues of $266 million for Carib Cinema, up from just $91 million in 2021, with a profit of $11 million versus a $21 million loss in 2021. Cineplex had no revenues in 2021 but suffered a loss of $14 million and bounced back in 2022 with revenues of $99 million and profit of $20 million. Sunshine Palace generated revenues of $203 million versus $54 million in 2021 with profit of $41 million compared with a loss of $35 million in 2021. The 2022 revenues include $43 million classified as other activities for Sunshine Palace. Multiplex delivered revenues of $143 million in 2022, up from just $35 million in 2021 with a profit of $20 million versus a loss of $23 million in 2021.
Cash flow brought in $53 million compared with outflows of $163 million in 2021 and helped in boosting funds on hand at the end of the calendar year.

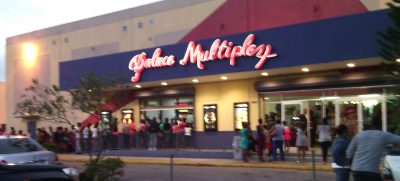
Palace Multiplex in Montego Bay.

From all that can be seen movies are still attracting patronage with what have been described as some good films and by the end of the fiscal year in June, the company seems set to be on its way to justifying their new bankers backing the company with a $700 million loan some of which was used to close out the Scotiabank loan and when the full history of this period unfolds the name Carol Lee, the financial controller will be high on the list for helping to save and restore the company to financial health.
The company now boast equity of $404 million thanks to the above profit and some $772 million in revaluation surplus, with $606 million of it coming in 2020. The company has some more lifting to do to steer them out of the woods while hoping that there will be no major setback in the recovery as they have $756 million in long term debt to be cleared in addition to $60 million of short term loans. There are halfway there with cash funds of $379 million on hand that should grow in the second half of the fiscal year. Palace also has accounts payable amounting to $435 million at the end of 2022 which is up from $386 million at the end of December 2021 and is covered by current assets of $481 million.
At this year’s annual general meeting, shareholders approved a 600 to 1 split as a result the stock trades x-split starting Monday, February 27, with the record date of February 28. The split will take the total number of shares to 862 million from 1.437 million currently.
The company should deliver earnings for the full year ending in June at around $100 per share.

Allen and Bailey buy 30m One on One shares

Soho Investments and Jorden Investments acquired 15 million shares each in One on One on Monday, February 13, to increase their equity holding in the company, the company announced.
The companies, owned by Ricardo Allen and John Bailey, respectively, bring their ownership in the 2022 listed Junior Market company to just under 24 percent and under 9 percent, respectively, in a move that is a vote of confidence in the future growth of the company.
Allen said, “Obviously, as the leader of the organization, I see the tremendous value that the team has been able to create here. We would also have line of sight as it relates to the growth journey we are about to embark on. With that being said, we believe that the current share price is low, and we will take the opportunity to purchase shares on the market as they become available at this price.
“We have some excellent growth initiatives ahead, and we look forward to executing on these and sharing them with our valued stakeholders when the time comes”.

Ricardo Allen CEO of One to One

On a recently hosted Earnings Call discussing the company’s first quarter results, Allen indicated that one of the company’s key strategic focus areas for the remainder of this year would be developing its content agency. To this end, the team has already acquired 4,000 square feet of space where it will look to build out studios to host instruction sessions and otherwise produce content to support its other product offerings, such as its Classroom in a Box as well as its Award-Winning Learning Management System.
In an interview with Allen, he indicated to ICInsider.com the content studio will provide abundant opportunities for creating content in educational services for local and global consumption.
Allen also indicated that staff cost rose in the first quarter of the current year ahead of revenue growth but that the additional revenues will start to flow in the company’s second half year numbers that are expected to flow through existing partnerships with agencies such as the Ministry of Education locally and the Department of Education in the Bahamas, as well as international alliances, such as that with Community Services Foundation.
The first quarter results show revenues almost doubling to $83 million, compared with $45 million in 2021, with profit rising to $12 million before tax from a loss of $1.8 million in 2021, following a sharp jump in Administrative and marketing cost to $54 million from $32 million in 2021.

Palace stock trades ex-split next Monday

Palace Amusement stock will trade x-split starting Monday, February 27, following approval at the January Annual general meeting of a 600 to 1 split with the record date of February 28.
The split will take the total number of shares to 862 million from 1.437 million currently and provide more liquidity in trading the company’s shares as more investors will be attracted to it than previously. The stock that traded on Monday at up to $2,700 will see the price dropping to the $4 plus range after the split takes effect next week.
The split comes at an opportune time for the company with its first profit since the March 2020 quarter and one of the best quarterly results in the company’s history.

.

The stock has enjoyed regular trading since the announcement of the split with the price reaching a record $3,300 and is now trading in the $2,700 range since releasing half year results with profits and revenues surging 222 percent to $486 million, with a profit of $79 million in the December quarter.
The split will result in the stock trading in the $4 to $6 region and will result in almost daily trading thus providing the company with regular publicity that it never had before based on the limited trading opportunities in the past. Such exposure could well result in a 10 to 20 percent jump in attendance as the name and product are beamed regularly on a wider audience than before.

Stock split to drive business for Palace

Palace Amusement stock will trade x-split starting Monday, February, with the record date of February 28 for the 600 to 1 split that will take the total number of shares to 862 million for 1.437 million currently and provide the company with added ongoing publicity.
The stock has enjoyed regular trading since the announcement of the split with the price reaching a record $3,300 and is now trading in the $2,700 range since releasing half year results with profits and revenues surging 222 percent to $486 million, with a profit of $79 million in the December quarter.
The split will result in the stock trading in the $4 to $6 region and will result in almost daily trading thus providing the company with regular publicity that it never had before based on the limited trading opportunities in the past. Such exposure could well result in a 10 to 20 percent jump in attendance as the name and product are beamed regularly on a wider audience than before.

Image Plus surge in profits

Following a big surge in revenues and profit for the year to February 2022, Image Plus Consultants with revenues climbing 27 percent to $777 million and profit surging 298 percent to $94 million after tax, the company is now reporting continuing solid performance for the nine months to November.

Revenues climbed 27 percent in the November quarter to $248 million and 43 percent in the nine months to $803 million while profit rose moderately to $24 million from $22 million in 2021 for the last quarter.  The 2022 quarterly results would be about 50 percent better than the outturn for the 2021 period, being saddled with added costs that were not incurred in 2021, with expected credit loss expense of $6 million with none in 2021 and higher finance cost of $8 million up from $1.8 million. For the nine months, profit nearly tripled that of 2021 to reach $148 million.
It is unclear whether earnings reflect the elevated payment of directors’ fees or not. The change in cost year over year does not suggest that in which case profit for the new period would jump sharply when that cost amounting to some $15 million per quarter falls away. Costs of sales rose 25.5 percent to $82.8 million in the latest quarter, from $66 million in 2021, for the nine months, the increase is 42 percent to $274 million from $192 million, with both the quarterly and nine months cost tracking close to the increased revenues, which is a positive development.
Administrative expenses rose 21.6 percent to $113 million from $93 million for the quarter and 12.7 percent for the nine months to $297 million from $264 million in 2021. Depreciation charges were flat in the quarter at $13 million but up to $32 million from $29 for the nine months.Dr Karlene McDonnough – Chairman of Image Consultants Ltd. The company originally reported incorrect earnings per share for the periods with the use of an incorrect number of shares in the computation but that has since been amended with a new release.  Earnings per share for the quarter is 2.3 cents and 15 cents for the nine months.

Dr Karlene McDonnough – Chairman of Image Consultants Ltd.

“The rate of revenue growth slowed somewhat since the second quarter as a result of the Ocho Rios relocation exercise (all operations at that branch were closed for four days whilst CT and Xray services were down for an additional seven days when the branch reopened as we awaited relocation of the 3 phase power supply required to operate these units). Management is confident that the move and resulting downtime is an investment that will redound significantly to the benefit of all stakeholders in the months ahead” the chairman and the Managing directors advised shareholders in their commentary accompanying the financials and went on to say.
“Despite this downtime, the company’s case count remains very healthy at 40,949 representing year to date, an increase of over 17 percent compared to the comparative period in the prior year. The number of cases at nine months represents 88.3 percent of the full financial year 21/22 case count.  Expenses grew 12.7 percent over the last financial year driven by higher than normal costs in Q3. In the main, these costs were associated with one off marketing expenditure for the re-printing of all billboards, directional and office signs for the Ocho Rios branch. Traditionally too, Q3 costs are expected to be a little higher as we have expenditure associated with referring physician appreciation and end of year performance incentives for our team members.”
Cash flow generated by operations was $138 million, acquisition of fixed assets amounting to $143 million utilized it all, in addition, $30 million was placed in investments and $30 million was used to pay dividends that were partially funded from net loan proceeds that brought in $51 million.
At the end of November, long term borrowings stood at $118 million and short term at just $4 million. Current assets ended the period at $311 million including trade and other receivables of $242 million, up from $106 million in 2021, while cash funds and investments ended at $49 million. Current liabilities ended the period at $124 million. Net current assets amount to $200 million.
November ended with shareholders’ equity of $415 million but is expected to hit the $900 million mark with the proceeds of the recent public share issue.
The stock that fell to a low of $1.77 last week, traded over $2 since this week.

600 to 1 stock split for Palace

Palace Amusement Company advised that the Board of directors will recommend to shareholders at their upcoming Annual General Meeting to be held on January 24, 2023, that the existing shares be split into 600 units for each currently issued and that the authorised share capital of the Company be increased from 1,500,000 shares to an Unlimited number of shares.

Palace Amusement is recommending 600 to one stock split.

If the resolution if approved at the meeting will take effect from the close of business on February 28, 2023, resulting in the total issued share capital of the company being increased from 1,437,028 ordinary shares to 862,216,800 ordinary shares.
The shares were last traded on Friday at $1,179 each on the Main Market of the Jamaica Stock Exchange but jumped nearly 20 percent in Wednesday’s trading session to $1,400, leading to a suspension in trading in the stock. The move will be welcomed by many of the company’s shareholders some of whom have been clamouring for the splitting of the stock for some time and will result in greater liquidity for the stock.

Profit slips at Honey Bun but watch 2023

A four year run of increased profits ended for the Junior Market listed baking company, Honey Bun, for the 2022 fiscal year to September, as cost pressure negated an impressive 38 percent surge in sales. Still, the revenue growth pales in comparison to a 59 percent jump in raw material cost for the year, amongst other items reflecting major cost movements.
Gross profit margin fell from 48 percent over the last three years to 40 percent, but a combination of price adjustments and reduction in raw material cost should result in an improvement in the 2023 fiscal year. Raw materials accounted for 29 percent of sales in 2021 but surged to 37 percent in the latest year. Administrative expenses jumped 32 percent to $531 million from $402 million in 2021. Staff costs rose 33 percent to $662 million, which increased employment accounted for a portion as the number of employed persons climbed 7 percent from 219 to 235. Selling and distribution costs rose just 17 percent to $408 million from $348 million in the prior year. Depreciation jumped 25 percent to $91 million from $73 million, but finance cost was negligible at just over $3 million.
For the year, revenues rose to $2.95 billion from $2.15 billion in 2021 and delivered a profit of $203 million, down from $219 million after taxation of $51 million and $72 million, respectively and generated earnings per share of 43 cents versus 46 cents in 2021. ICInsider.com forecast is for earnings of $1 per share for the 2023 fiscal year and $1.85 for 2024.
Interest income and reversal of impairment credit losses contributed to $20 million to profits versus $14 million in 2021, while other operating income contributed $2.5 million, down from $4.8 million in 2021.
Cash flows from operations amount to $185 million, down from $304 million in 2021. For the latest fiscal year, $166 million was used to acquire fixed assets and $73 million was used to pay dividends, resulting in $57 million of funds brought forward from 2021 being used to fund the 2022 activities.
The company finances remain healthy, with shareholders’ equity at $1.16 billion while borrowings amount to just $72 million. Current assets ended at $699 million, with cash and equivalent at $347 million and current liabilities at $256 million.
The stock traded on the Junior Market of the Jamaica Stock Exchange at $7.78 at a PE of 7.8 based on the projected 2023 earnings and 18 times 2022 earnings compared with the market average of 12 currently.

Palace considering split stock

Palace Amusement Company is set to split the stock that last traded at $620 per share on Monday, with a range of 620 to $1,150 for 2022.
The company informed the Jamaica Stock Exchange that the Directors proposed to meet on Tuesday, December 20, 2022, and will be discussing the possibility of a stock split. A split is almost a certainty, with the company having borrowed over $700 million, the opportunity exists to raise fresh capital by way of an additional public issue of shares to pay down the debt. Splitting the stock to make them more attractive to retail investors would be a logical step.
To achieve an attractive price and create wide-scale public interest would require a split in the order of 100 to 200 to one of the existing issued shares and would raise the issued number of shares to between 250 to 300 million units.
Other companies talking about stock splits that could come in 2023 are Medical Disposables that could come with a stock split and a rights issue of more shares to use to fund expansion.

Palace jumps $800 to a record $2,900.

Stationery and Office Supplies informed shareholders at the recently held Annual General Meeting that the directors have been looking but currently the liquidy of the stock does warrant one just yet.
Others that should give serious consideration to splitting their stocks are Access Financial Services, with the stock trading over $20, Dolphin Cove priced in double digits, Barita Investments, Cargo Handlers, Honey Bun, ISP Finance, Knutsford Express and Main Event.

Kingston Wharves left for dead

Peculiarities of the local stock market can be seen in many areas with the performance of Kingston Wharves since 2019 highlighting the exuberance of many investors. They pushed the stock up to a high of $78 in 2019 with earnings per share of $1.82 from profits of $2.6 billion, up from a profit of $1.97 million in 2018, with earnings per share of $1.36, but the stock was selling at an enormous price earnings ratio in excess of 43 times 2019 earnings.

Kingston Wharves’ profit rose 8% in Q3.

Investors could not care less about a stock that was excessively overvalued, with the valuation well ahead of the market average at the time, around 22 times at the end of 2019. The company reported a profit of $3.25 billion in 2021 versus $2.28 billion in 2020 for earnings per share of $2.24 up from $1.57 in the previous year. Investors who were paying nearly $80 per share in 2019 are now scared to buy the stock around the $32 level even with improved earnings since 2019.
Admittedly, interest rates on Government of Jamaica Treasury bills at 1.6 percent in December 2019 were very attractive but it was at an unsustainable level and is now just over eight percent. This would result in a reduction in share valuation. But it does not explain why a stock that was priced at twice the rest of the market is no longer having a premium over the market.
For the current year to September, Kingston Wharves reported flat earnings of $2.1 billion compared to the previous year, but the third quarter reflects a 7.7 percent improvement in profits to $837 million in 2022 from $778 million in 2021.
Other operating revenues came in at $135.5 million in the September 2022 quarter, up from $53 million in 2021 and for the year to date, $155.8 billion down from $316 billion in 2021.
Cost of sales in the September quarter amounted to $1.267 billion versus $1.06 billion in 2021 and for the nine months $3.6 billion versus $3.1 billion, resulting in a gross profit of $1.18 billion for the September 2022 quarter, a slight improvement over the $1.16 billion in the previous year and for the nine months, $3.39 billion versus $3.1 billion. The gross profit margin slipped from 52 percent in the September 2021 quarter to 48 percent in 2022 with the year to date dipping from 50 percent in 2021 to 48 percent this year.
Administrative expenses amounted to $335 million in the September 2022 quarter, up 16 percent from $290 million in 2021 and for the nine months, rose 23 percent to $1.1 billion from $899 million in the previous year. Finance costs accounted for $25 million in the September 2022 quarter, up from $20.55 million last year and for the nine months, $32 million, down from $90 million in the previous year’s nine months. Taxation accounted for $117 million versus $127 million in the 2021 September quarter and $304 million for the nine months to September 2022, from $342 million in the previous year.
Shareholders’ equity ended the period at $36.66 billion. Total borrowed funds amounted to just $1.7 billion while it holds cash funds and investments of $9.5 billion. Current assets amount to $11 billion and current liabilities of $1.96 billion. Cash flows from operation generated inflows of $3.3 billion, after spending $1.5 billion on the purchase of property and $873 million on paying dividends and loan repayment of $500 million, the company used up all the inflows for the nine months.
Net book value per share amounts to $25.64, with the stock priced at $31.85 for a 24 percent premium. ICInsider.com projects earnings for the current year at $2.25 and $3 for 2023. These earnings suggest a stock price in 2023 in the $40 to $50 region at a PE of around 16 and it could be higher as interest rates should start to moderate by the middle of 2023 if not before. Going forward growth in the local economy is expected to continue for some time, accordingly, the wharf should be enjoying increased through put and result in increased revenues and profits.