Sygnus Credit a stock to watch

Image courtesy of suphakit73/FreeDigitalPhotos.net

Sygnus Credit Investment a relatively new player in the financial market saw a 171 percent jump in interest income from US$1 million in 2018 to US$3 million for the financial year to June 2019.
Established in 2017, Sygnus is a credit investment company that provides credit financing to medium size business in the Caribbean
The impact on profit was not as dramatic as the gains in revenues, with profit rising 44 percent to US$2 million from US$1.4 million in 2018. The major reason for profit lagging revenue is three major items.  Fair value gains on investment fell from $644,000 in 2018 to just $135,000 in 2019 while the Management fee rose 288  percent from US$182,368 in 2018 to US$707,175 and net foreign exchange loss moved from US$50,000 in 2018 to US$219,000. Management fees were lower in the preceding financial year as the investment management waived them manager in the first half of that year.
The near-full deployment of US$20 million of funds on hand at the start of the year, into higher-yielding investments in the form of loans, was the major contributing factor to the growth in interest income.
Other operating and administrative expenses rose 214 percent to US$1.3 million in the year from US$415,000. Accounting expenses increased by 79 percent to US$37,323. The results for the final quarter were affected negatively by major turn about-turn in foreign exchange movements with a gain of $856,000 in the third quarter moving to a loss of $219,000 in the fourth quarter. Additionally, while interest income for the third quarter was $979,000 it slipped to just $728,000 in the final quarter, most likely due to change in the value of the Jamaican dollar. The effect of those changes is that a $1 million profit for the third quarter was not reproduced in the final quarter, even with more funds deployed in higher income-generating assets than the securities they were in before. The profit for the final quarter came out at just $124,000, well off from the fourth-quarter profit.  Going forward, the company will be using borrowed funds to supplement its resources that will help in boosting revenues, profit and allowed for growth in its business.
Sygnus paid US$954,000 in dividends leaving shareholders’ equity at US$37.6 million, $34 million was lent to customers and $3 million was held in liquid assets that were available for lending. Earnings per share came out at 0.59 US cents for the financial year-end compared to 0.85 US cents for the 2018 financial year.
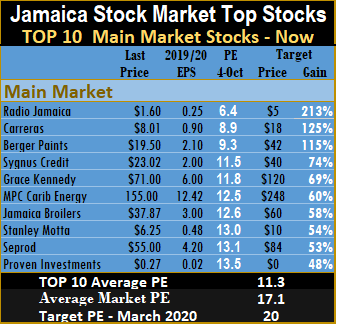
IC Insider.com forecasts earnings of 15 US cents or J$2 per share. The stock traded at $23.70 on the main market of the Jamaica Stock Exchange with a PE ratio of 12 times 2020 earnings making it a good buy.
Bun & Teas in IC TOP 10 BUY RATED

Buy Rated Junior Market stocks have two new entrants this week with Honey Bun and Jamaican Teas returning to the top listing. Both companies’ fiscal year ended September, with earnings for the 2020 fiscal year, used in valuing them.
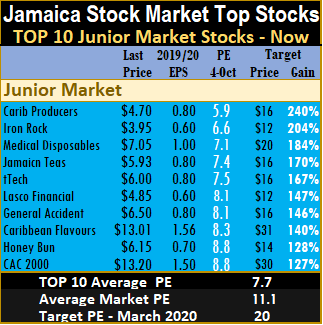
The new listings are expected to benefit from growth in the core business, with Honey Bun continuing to benefit above the norm from the expansion of the factory late last year and new products being manufactured while Jamaican Teas could benefit from investment gains from the portfolio of QWI Investments.
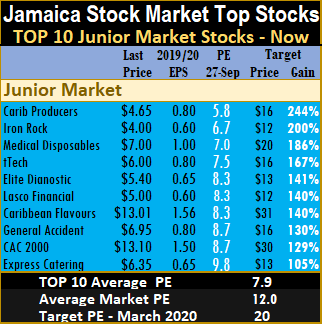
Dropping from the Junior Market TOP 10 are Elite Diagnostic and Express Catering.  There were no changes to the main market TOP 10.
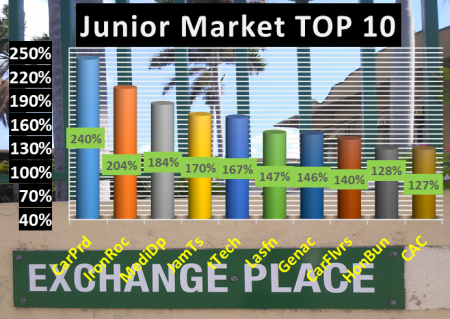
Market activity, left Caribbean Producers with projected gains of 240 percent as the leading Junior Market stock with likely gains, followed by Iron Rock Insurance with potential gains of 204 percent and Medical Disposables with projected gains of 184 percent.
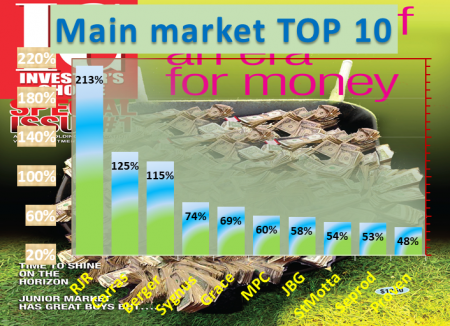
Radio Jamaica (RJR) share price slipped during the week to a low of $1.35 but bounced to close the week at $1.60, pushing projected gains to 213 percent, to remain the leading main market stock. RJR is benefiting from increasing revenues, resulting from a more buoyant economy, the rollout of new services, the signing of an agreement with Flow that will add to revenues without the added cost and lower costs in a number of areas, with more to come. Carreras sits at the number two spot with projected gains of 125 percent with the price slipping a bit during the week and Berger Paints with projected gains of 115 percent in next.
The main market, closed the week with the overall PE of 17.1 down from 17.7 the previous week and the Junior Market is at 11.1 from 11.7 based on current year’s earnings. The PE ratio for Junior Market Top 10 stocks averages 7.7 compared to 7.9 the previous week and the main market PE remains at 10.4.
The TOP 10 stocks now trade at an average discount of 31 percent to the average for the Junior Market Top stocks and main market stocks trade at a discount of 39 percent to the overall market.
TOP 10 stocks are likely to deliver the best returns to March next year. Projected earnings, along with the PE ratio for each company’s current fiscal year are used in determining potential gains with the likely gains ranked in descending order with highest-ranked being the most attractive. Potential values will change as stock prices fluctuate and will result in movements of the selection in and out of the lists for most weeks. Earnings per share are revised on an ongoing basis as new information is received that can result in changes in and out of the list.
This report is compiled by persons who may have an interest in the securities commented on.

General Accident acquisition to boost results

General Accident head quarters

The junior Market listed General Accident acquired a 55 percent stake in Motor One Insurance, a Trinidadian based company, with a large branch network throughout Trinidad.
Motor One, is said to be one of Trinidad and Tobago’s smaller general insurance companies but the acquisition provides General Accident with a ready platform expand in the Trinidad market into motor vehicle and catastrophic insurance business in the Caribbean twin-island state which is said to be over 40 percent larger than the general insurance market in Jamaica. The acquisition will provide a platform for the local company to expand in the wider region and importantly, into Guyana where the economy is already growing strongly with the country set to benefit even more from the near term production of oil but that seems a bit off for now.
The acquisition, “is an important first step in our wider regional growth strategy which we believe will increase economies of scale, spread our risk and significantly enhance shareholder value,” General Accident’s chairman, Paul Scott stated in the release announcing the purchase.
General Accident is having a good two-year run, with rising income and profit, in 2016 revenues from core business hardly changed but investment income rose and helped to push pretax profit up by a third. In 2017, net underwriting revenues grew 28 percent over 2016 and by 22.6 percent in 2018 over 2017but profit declined 42 percent for 2017 and rose 50 percent in 2018 but was still below the pretax profit delivered in 2016. The company’s profit performance in the 2019 June quarter improved 31 percent to $104 million from $80 million in 2018 after tax and for the six months period by 42 percent to $135 million from $95 million in 2018.
Gross premiums written, rose 59 percent for the quarter to $4 billion from $2.4 billion and by 41 percent for the year to date to $7 billion from $5 billion in 2018.
Net premium earned rose 25 percent in the quarter to $503 million from $403 million and climbed 29 percent for the year to date to $989 million from $767 million in 2018. Commission expense increased 15 percent in the quarter to $116 million from $100 million and by 20 percent for the year to date to $260 million from $216 million in 2018 while commission income rose 14 percent in the quarter to $170 million from $149 million in 2018 and for the half-year, it rose 21 percent to $406 million. Investment and other income fell 18 percent in the half-year to $117 million from $143 million and rose 22 percent to hit $111 million.
Management expenses increased 26 percent to $227 million in the quarter and 19 percent in the six-month period to $419 million. Claims grew 28 percent to $339 million in the quarter and 23 percent in the half-year to $633 million. Other operating expenses increased in the quarter to $23 million from $11 million in 2018 and from $21 million to $35 million for the six-month period.
Gross cash flow from operating activities brought in $922 million, but net of amounts due to reinsurers and co-insurers and other working capital movements reduced cash provided by operating activities to $363 million. General Accident paid dividends of $150 million during the year and ended with cash and investments of $3.3 billion, up from $2.7 billion at the end of June 2018. At the end of June, shareholders’ equity stood at $2.2 billion. Total assets ended the period at $7.9 billion inclusive of dues from reinsurers and co-insures of $2 billion, cash and bank balances of $190 million and liabilities of $6 million.
Earnings per share came out at 0.10 cents for the quarter and 0.13 cents for the six months. IC Insider.com is forecasting 80 cents per share for the full year for a PE of 8 times earnings.

IC TOP 10 focus on QWI

Attention by investors seems set to be focused on QWI Investments, which commences trading on Monday, but being the end of the month, investors could be seeing other stocks recording interesting movements.
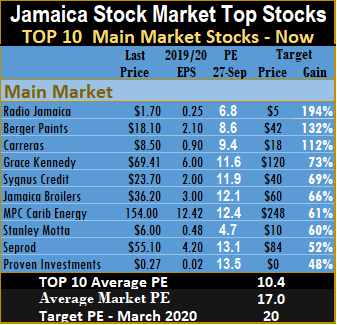
Buy Rated stocks had few changes with Elite Diagnostic and Express Catering climbing back into the Junior Market TOP 10 with the price of Elite dropping to $5.40 from $5.60 at the end of the previous week while Seprod returns to the main market list at the expense of Scotia Group.
Slipping out of the IC TOP 10 listing is Jetcon Corporation that remained at $1.80, Main Event earnings were adjusted down with the decline of profit reported in the July quarter due to increased cost that exceeded revenues and Scotia Group rose to $60 from $57.50 and dropped out of the TOP 10.
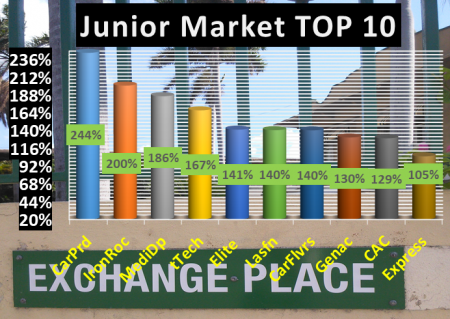
Market activity, resulted in Caribbean Producers with projected gains of 244 percent being the leading Junior Market stock with potential gains, followed by Iron Rock with likely gains of 200 percent and Medical Disposables with projected gains of 186 percent.
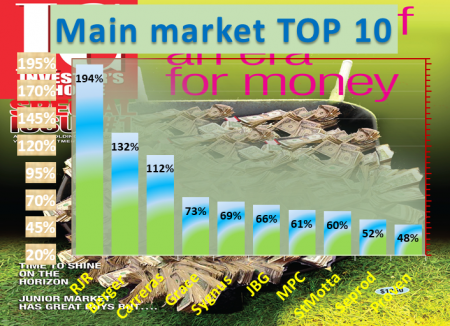
Radio Jamaica closed the week with projected gains of 194 percent as the leading main market stock with the price falling to $1.70 from $1.90 during the week. Berger Paints sits at the number two spot with projected gains of 132 percent as more interest comes in for this stock coupled with reduced selling ahead of the most important quarter coming up when sales exceed all other quarters and Carreras with projected gains of 112 percent.
The main market closed the week with the overall PE of 17.7 up from 16.7 the previous week and the Junior Market is up to 11.7 from 11.3 based on current year’s earnings. The PE ratio for Junior Market Top 10 stocks averages 7.9 compared to 7.8 the previous week and the main market PE remains at 10.4. These levels of PE ratios point to big upside for TOP 10 stocks.
The TOP 10 stocks now trade at an average discount of 32 percent to the average for the Junior Market Top stocks and main market stocks trade at a discount of 41 percent to the overall market.
TOP 10 stocks are likely to deliver the best returns to March next year. Projected earnings, along with the PE ratio for each company’s current fiscal year are used in determining potential gains with the likely gains ranked in descending order with highest-ranked being the most attractive. Potential values will change as stock prices fluctuate and will result in movements of the selection in and out of the lists for most weeks. Earnings per share are revised on an ongoing basis as new information is received that can result in changes in and out of the list.
This report is compiled by persons who may have an interest in the securities commented on.

Increased cost stunts Main Event’s profit

Main Event revenues growing nicely profit stalls.

Sales climbed 29 percent for the quarter to $469 million from $364 million in 2018 but increased cost melted away the revenue gains leaving 40 percent less profit in the July quarter at $15 million, down from $25 million reported in 2018 for Main Event.
The third quarter’s performance is in stark contrast to the second-quarter performance. With $31 million lower revenues, profit in the April 2019 quarter was $62 million, well up on the July quarter’s outcome.
The company, an entertainment production and planning agent, recorded a strong 28 percent growth in revenues for the nine months to July of $1.36 billion, up from $1.07 billion in 2018. Very little of the increased income percolated into more profit for the nine months to July, as profit increased slightly by 2 percent to $108 million from $105 million in 2018.
The strong increase revenue is attributed to the company’s focus on diversifying its income stream that includes M-Style experience that focuses on the wedding market, expansion to the western end of the island and M Academy project, the company directors advised investors.
Gross profit margin in the nine-month period fell to 44 percent from 48 percent in 2018 and was also down in the July quarter by 42 percent, from 45 percent in 2018. Direct expenses climbed 37 percent in the nine months ending July to $761 million from $556 million in 2018, and by 36 percent in the quarter ending July to $271 million from $200 million. Gross profit rose slower than revenues by 21 percent in the quarter to $198 million from $164 million but increased 18 percent for the year to date to $604 million from $510 million in 2018.

Three directors of Main Event, including the mentor who is responsible to ensure compliance with the JSE rules.

Operating and administrative expenses rose a sharp 35 percent to $182 million in the quarter and 25 percent in the nine months to $492 million. Finance cost declined in the quarter to $8 million from $5 million in 2018 and from $14 million to $18 million for the nine-month period. “We have taken note of increased prices in third party inputs and increased inefficiency internally”, the directors indicated.
Gross cash flow from operating activities brought in $213 million, payables of $146 million and dividends of $18 million. At the end of July, shareholders’ equity was $631 million, long term loans of $139 million, net current assets ended the period at $470 billion inclusive of receivables of $375 million, cash and bank balances of $50 million and current liabilities of $240 million.
Earnings per share came out at 4 cents for the quarter and 36 cents for the nine months. IC Insider.com is forecasting 40 cents per share for PE of 14 times earnings, importantly, with the 2019 fiscal year ending in October investors should be looking at the 2020 results to deliver increased profits and stock price appreciation. Continued strong top-line growth and implementation of cost control measures will enhance gains in 2020 and should see earnings hitting 85 cents per share for a PE of 7. The shares are listed on the Junior Market of the Jamaica Stock Exchange and last traded at $5.72.

69M Access shares offered at $32 each

Proven Investments is offering 68.6 million or 25 percent of the shares it currently owns in Access Financial Services for sale, at $32 per share starting today with the issue not expected to be open beyond today.
The prospectus suggests that the offer could be upsized if deemed appropriate but information obtained by IC Insider.com indicates that it will not be. Proven bought the block of shares mainly from Mayberry Investments on December 30, 2014, at $9 each, to become the largest shareholder. On several occasions in the past, the CEO Christopher Williams maintained the view that they had no intention of selling the shares, but that was before they bought 20 percent of JMMB Group from NCB Group in December 2018, costing $9 billion and financed by debt. With JMMB Group going back to the market to issue new shares, Proven will need to have funds to buy enough shares to maintain their 20 percent holdings if they intend to account for profits on an equity basis.
At $32, the stock is an attractive buy for investors looking for a value play investment. It is priced under 10 times current year’s earnings and could double within a year.
Access is one of the most rewarding investment for shareholders over the years, with an outstanding record of increased profits high return on equity and good and consistent dividend payments. Return on equity slipped in the past two years as interest rates and new accounting standards took effect but the company continues to grow. In recent years, growth was boosted by acquisitions of other micro-lending companies. Last year the company acquired Embassy Loans located in the Florida area in the United States.
The company realized Net Operating Income for the quarter ending June 2019 of $539 million of which the new US subsidiary Embassy Loans contributed $151 million. Interest income from loans increased by $8 million or 2 percent to $408 million while net fees and commission for the period was $153m. For the period, Embassy Loans contributed $44 million and $103 million respectively to the group’s Interest and fee income.

Christopher Williams, Proven Investments CEO.

Operating expenses for the quarter, increased by 90 percent or $179 million compared to the corresponding period ended June 2018, resulting from an increase in allowances for credit losses, based on the implementation of the IFRS 9 provisioning methodology and the inclusion of Embassy’s operating expenses for the quarter amounting to $110 million.
Net profit after tax for the quarter ended June 2019 declined 24 percent to $165 million compared to the 2018 period and resulted in earnings per share of 60 cents. Annualised earnings work out at $2.40, at a PE of 15, the value would be $36.
Access will generate cash flow from profits monthly and increase the amount available for lending, as such, earnings per share should be in the $3 region for the current year putting the likely value around $45.
The stock tends to be scarce and the potential for long term growth remains positive if a bit diminished in recent times with pressures on interest margins. Consolidation in the industry locally is to be expected and Access should be able to take over more of the smaller players going forward. It is most likely that Access will move most of the administrative functions to Jamaica with the lower cost than in Florida and therefore cut the cost of the US operations.

IC TOP 10 relatively stable

Jamaica Broilers announced a new acquisition last week

The Jamaica stock market was impacted last week by fresh share insurances and acquisitions by two IC TOP 10 listed companies.
Investors’ attention was on pumping funds into Barita Investments’ rights issue and QWI Investments’ initial public offering in the past week and led to more muted market activity, with the latter attracting more than 4,000 investors and in excess of $1.5 billion.
Other major developments in the past week were the announcement that TOP 10 BUY RATED General Accident picked up 55 percent of the Trinidad based Motor One Insurance company but investors hardly seem to notice. Another Top 10 listing, Jamaica Broilers announced yet another takeover of a poultry processing plant in the USA. Market activity in the coming week will be further affected with Proven Investments selling half of their holdings in Access Financial stock by way of a public offer, at an attractive price of $32 each. Market conditions resulted in just two changes to IC TOP 10 BUY RATED list as CAC 2000 returned to the top 10 Junior Market list, replacing Caribbean Cream and Scotia Group moved back into the main market listing at the expense of Seprod.
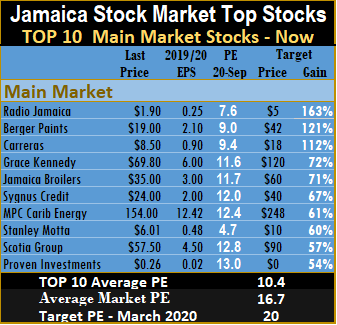
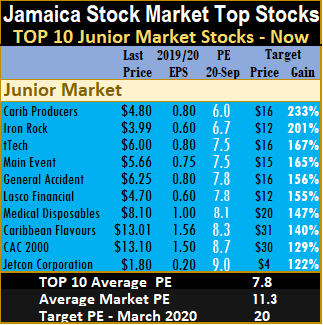
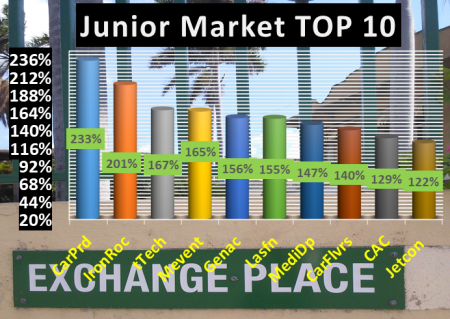
Changes in prices left Caribbean Producers with projected gains of 233 percent, followed Iron Rock by with likely gains of 201 percent and tTech with projected gains of 167 percent as the three most attractive Junior Market stocks.
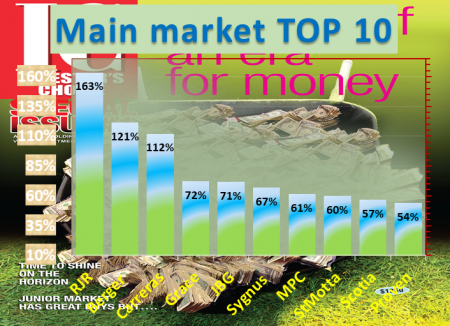
Radio Jamaica closed the week with projected gains of 163 percent as the leading main market stock with the price falling to $1.90 by the end of the week. Berger Paints sits at the number two spot with projected gains of 121 percent as more interest comes in for this stock coupled with reduced selling ahead of the most important quarter coming up when sales exceed all other quarters and Carreras with projected gains of 112 percent.
The main market, closed the week with the overall PE of 16.7 down from 17.7 the previous week and the Junior Market is down to 11.3 from 11.6 based on current year’s earnings. The PE ratio for Junior Market Top 10 stocks averages 7.8 compared to 7.7 the previous week and the main market PE slips to 10.4. These levels of PE ratios point to big upside for TOP 10 stocks.
The TOP 10 stocks now trade at an average discount of 31 percent to the average for the Junior Market Top stocks and main market stocks trade at a discount of 38 percent to the overall market.
TOP 10 stocks are likely to deliver the best returns to March next year. Projected earnings, along with the PE ratio for each company’s current fiscal year are used in determining potential gains. The likely gains are ranked in descending order, with the highest-ranked being the most attractive and moving down the least attractive. Potential values will change as stock prices fluctuate and will result in movements of the selection in and out of the lists for most weeks. Earnings per share are revised on an ongoing basis as new information is received that can result in changes in and out of the list.
This report is compiled by persons who may have an interest in the securities commented on.

IC TOP 10 MPC hits new record high

Prices pulled back during the past week but the new IC TOP 10 BUY RATED main market stocks MPC Caribbean Energy surged to an all-time high of $153.06 and is still in the TOP 10 and seems poised to move higher with no sellers in sight.
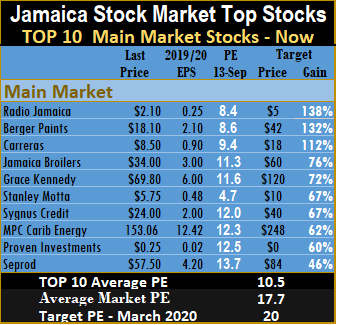
Seprod returns and Scotia Group moved out to be the only changes to the main market list. Jetcon Corporation, Caribbean Cream and Caribbean Flavours return to the Junior Market TOP 10 replacing CAC 2000, Dolphin Cove and Jamaican Teas.
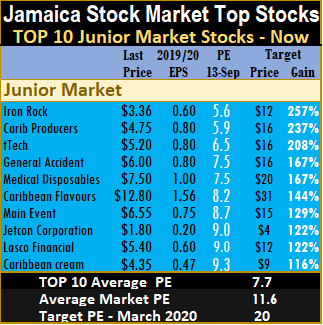
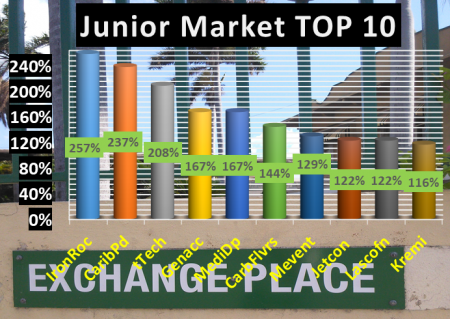
The three most attractive Junior Market stocks are Iron Rock with projected gains of 257 percent, followed by Caribbean Producers with likely gains of 237 percent and tTech with projected gains of 208 percent.
Radio Jamaica closed the week with projected gains of 138 percent as the leading main market stock followed by Berger Paints with projected gains of 132 and Carreras with projected gains of 112 percent.
The main market, closed the week with the overall PE of 17.7 down from 18.3 the previous week and the Junior Market is down to 11.6 from 12.1 based on current year’s earnings. The PE ratio for Junior Market Top 10 stocks averages 7.7 compared to 8.4 the previous week and the main market PE is now 10.5. These levels of PE ratios point to big upside for TOP 10 stocks.
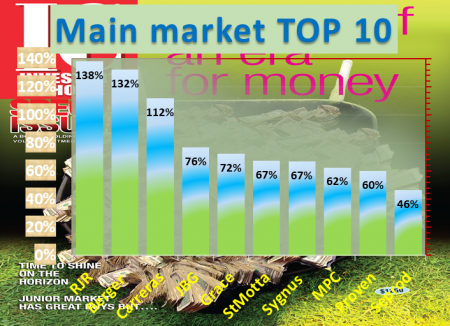
The TOP 10 stocks now trade at an average discount of 33 percent to the average for the Junior Market Top stocks and main market stocks trade at a discount of 41 percent to the overall market.
TOP 10 stocks are likely to deliver the best returns to March next year. Projected earnings, for each company’s current fiscal year, are used in determining, the selected stocks. The PE for and projected earnings for each stock are computed to show potential gains for the year, which are ranked in descending order. Potential values will change as stock prices fluctuate and will result in movements of the selection in and out of the lists for most weeks. Earnings per share are revised on an ongoing basis as new information is received that can result in changes in and out of the list.
This report is compiled by persons who may have an interest in the securities commented on.

Big surprise entry to IC TOP 10

IC TOP 10 BUY RATED main market stocks got a surprise entry as MPC Caribbean Energy surged into the top list for the first time to sit at fourth position at the expense of Seprod.
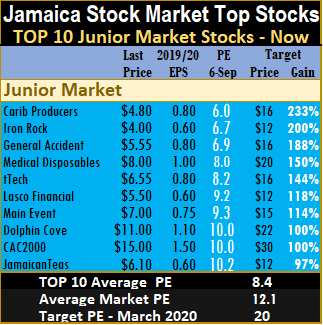
There was no other change in the main market list but the Junior Market IC Insider.com TOP 10 had two new entrants with CAC 2000 returning after a week’s absence, along with Dolphin Cove. They replaced Access Financial and Express Catering with the prices of both moving higher by the end of the week.
MPC is making the top list after the company reported profit of US$126,746 or the June quarter before the company’s investment in the solar plant in Westmoreland, Jamaica, starts contributing full quarterly revenues and profit.
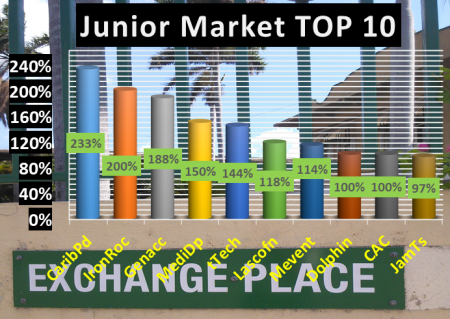
The three most attractive Junior Market stocks are Caribbean Producers with projected gains of 233 percent, followed by Iron Rock with likely gains of 200 percent and General Accident with projected gains of 188 percent.
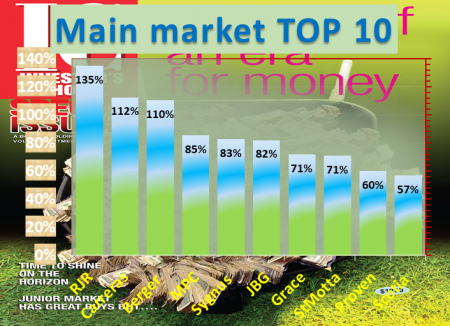
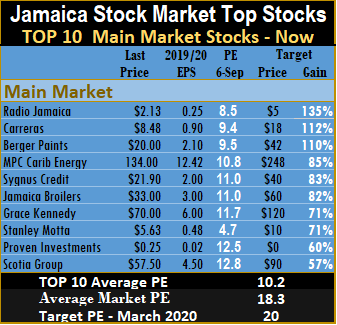
Radio Jamaica inched to $2.13 at the close of the week leaving it with projected gains of 135 percent and the leading main market stock with the highest likely gains followed by Carreras with projected gains of 112 and Berger Paints with projected gains of 110 percent after the stock closed the week at $20.
The main market closed the week with the overall PE of 18.3 and the Junior Market remains at 12.1 current year’s earnings. The PE ratio for Junior Market Top 10 stocks averages 8.4 and the main market PE is now 10.2. These levels, point to big upside for TOP 10 stocks to the end of March next year and Junior Market stocks in particular as they lag, the values of the main market by a third.
The TOP 10 stocks now trade at an average discount of 34 percent to the average for the Junior Market Top stocks and main market stocks trade at a discount of 44 percent to the overall market.
TOP 10 stocks are likely to deliver the best returns to March next year. Projected earnings, for each company’s current fiscal year, are used in determining, the selected stocks. The PE for and projected earnings for each stock are computed to show potential gains for the year, which are ranked in descending order. Potential values will change as stock prices fluctuate and will result in movements of the selection in and out of the lists for most weeks. Earnings per share are revised on an ongoing basis as new information is received that can result in changes in and out of the list.
This report is compiled by persons who may have an interest in the securities commented on.

Fontana Q4 sales jump 15%

the stock remains the main attraction in trading.

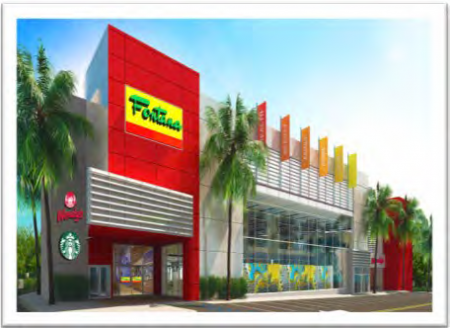
Fontana upcoming Waterloo Road branch set to open in September.

Sales at Junior Market listed Fontana grew 6.8 percent in the March 2019 quarter over 2018 and 7 percent for the nine months to March as well as for the full year to June but surged by a strong 15 percent in the final quarter to June.
Audited financial report show sales for the full year at $3.7 billion, up on the $3.42 billion recorded in 2018, representing growth of $594 million in the June 2019 quarter over the $3.108 billion generated up to March this year. Revenues for the June 2018, added $516 million to the nine months’ sales of $2.9 billion recorded to March last year. The June quarter revenues are much lower than in the March quarter with sales of $951 million that is up from $890 million in 2018. The acceleration in growth in the June quarter is significant and is worth watching to see if it continues.
The audited accounts when compared with the March quarter show profit margins that were better in the final quarter than in the March quarter with gross profit coming in at $281 million versus $297 million but with the June quarter sales being just 63 percent of the March sales. The company reversed $56 million in provision for inventory obsolescence during the year and this could be the reason for the sharp improvement in the fourth quarter margin.
Administrative and other expenses that rose 10.5 percent to March to $721 million finished the year off with an 8.3 percent increase to $1 billion. Some of the cost increase would be as a result of staffing and other cost associated with the new store at Waterloo Road in Kingston that is slated to open in mid-September.
Fontana ended with profit before taxation of $270 million, down from $303 million in 2018 but closed with profit after tax at $307 million versus $247 million in 2018. The operations generated gross cash flows of $305 million for the year and expended $441 on the acquisition and property development and inflows of $223 million from the issue of shares to the public. Cash and equivalent rose to $383 million at year-end with receivables at just $67 million while payables stood at $460 million and loans at $157 million.
Inventories excluding provision for obsolescence is down from $712 million to $639 million at the end of the fiscal year. Fixed assets grew to $701 million after the sale of $302 million of buildings and spending of $464 million on the Waterloo Road store. Shareholders’ equity climbed to $1.27 billion from $1.06 billion in 2018.
The stock traded at $8.20 on Friday at a PE ratio of 11 based on IC Insider.com forecasted earnings of 75 cents per shares.