In Monday’s trading on the Jamaica Stock Exchange the prices of 6 stocks rose and 3 declined as 21 securities traded resulting in 5,426,535 shares changing hands valued at $14,802,328. The IC market sentiment indicator is pointing to continued fluidity in prices with almost an even number of stocks with bids and offers above or below their last traded prices.
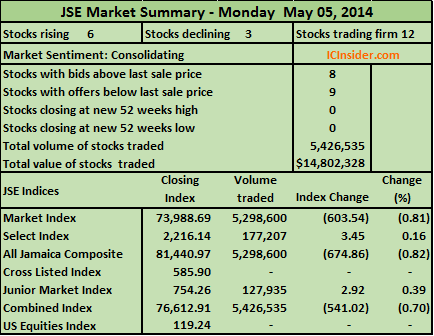 Main Market| 5 companies in the main market advanced, only 3 declined as the indices moved down with the JSE Market Index falling by 603.54 points to 73,988.69 and the JSE All Jamaican Composite index declining by 674.86 points to close at 81,440.97.
Gains| Stocks recording gains at the end of trading in the main market are Cable & Wireless trading 16,832 shares to close with a gain of one cent at 41 cents, Desnoes & Geddes gained 20 cents to close at $4.50 with 450 units changing hands, National Commercial Bank 1,690 shares to close at $18.30 with a gain of 20 cents, Pan Jamaican Investment with 101,574 shares to close at $49.28, up 23 cents. Radio Jamaica had 4,900,000 units changing hands to close with a 4 cents gain at $1.32.
Firm| There were only 6 stocks in the main market to close without a change in price as Gleaner with 22,980 shares closed at $1.10, Grace Kennedy 810 units helped the price to close at $56.51, Jamaica Broilers traded 113,552 shares to close at $4.85, Mayberry Investments with 1,020 shares closed at $1.70, Sagicor Real Estate Fund traded 11,930 units to close at $6.50 and Scotia Group with 18,575 units closed at $20.50.
Declines| The number of stocks that declined in the main market are Jamaica Money Market Brokers with 1,298 shares in losing 2 cents to end at $7.22, Sagicor Group 106,867 shares to close down by 30 cents at $9.50 and Seprod with 1,022 at $10.80 for a 4 cents fall.
Junior Market| The JSE Junior Market Index advanced by 2.92 points to close at 754.26 as only 6 stocks traded in that market.
Gains| Lasco Manufacturing was the only stock recording a gain at the end of trading in the junior market as 44,697 shares changed hands to close up by 9 cents at $1.19.
Firm Trades| Stocks in the junior market that traded to close at the same price as the day before are AMG Packaging with 500 units at $3.50, Blue Power with 19,438 units at $9.01, Derrimon Trading 12,000 units at $2.28, Lasco Distributors 37,300 shares at $1.40 and Lasco Financial Services 14,000 units at $1.20. Access Financial 9% Unsecured Short Term Notes traded 9,000 units at $99.50.
Declines| No stock declined in the junior market at the end of trading on Monday.
IC bid-offer Indicator| At the end of trading the Investor’s Choice bid-offer indicator had 8 stocks with the bid higher than the last selling price and 9 stocks with offers that were lower.
Advancing stocks top declines
D&G, Carreras & C&WJ now Buy Rated
IC Insider has added Desnoes & Geddes, Carreras and Cable & Wireless Jamaica to the Buy Rated list.
Desnoes & Geddes reported gains of 21 percent for the six months to December, earnings excluding one-off items and is poised to earn 80 cents for the full year ending in 2014. Forecasted earnings for the 2015 year is $1.10.
For Carreras the worse seems to be over with the last set of interim figures showing sales starting to recover from the impact caused by the price increase and the stock piling of cigarettes in the 2012 December and March 2013 quarters. IC Insider’s forecast is for earnings of around $5 per share for the year to March 2014.
Cable & Wireless’ sharp increase in cellular revenues and cost cutting will change the bottom-line markedly going forward.
Berger Paints Jamaica has been added to the market watch list flowing from a revival in earnings for the March 2014 year.
Related posts | D&G elevated to Buy Rated! | Carreras is back | CWJ loss down with much progress | Berger keeps profit gains

Image courtesy of suphakit73/FreeDigitalPhotos.net
D&G elevated to Buy Rated!
Desnoes & Geddes brewers of the world renown Red Stripe beer reported profit before taxation of $2.45 billion, a 102 percent increase over the $1.2 billion generated in 2012 and net profit of $1.95 billion. The huge jump in the bottom line came from booking capital gains from the sale of its interest in two eastern Caribbean Breweries in the December quarter, which contributed $970 million to the profit. Excluding this one-off capital gain would result in the 2013 numbers coming in at $1.479 billion for pretax profit or an increase of 21 percent, and $976 million after tax versus $808 in 2012. This translates to 35 cents per share for the six months period.
Profit in the local market before administrative and selling expenses rose 22 percent to reach $1.56 billion but export profits fell slightly to $402 from $468 million in 2012. Based on the latest results, IC Insider is forecasting 80 cents per share earnings for the year to June 2014 and $1.10 for 2015. Based on the company’s expected performance, IC Insider has elevated Desnoes & Geddes to Buy Rated status.
 Sales | Revenues grew 12 percent to $7.30 billion, compared with $6.5 billion in 2012 for the six months and grew by a more robust 18.5 percent in the latest quarter to $4 billion.
“The domestic portfolio continues to grow, increasing by 23 percent on growth in the brewed portfolio as well as improved pricing. Export sales declined 28 percent as the shift in production from Jamaica to the USA during the last financial year,” management stated in their release with the financials.
Gross Profit margin ended at 72 percent for the December quarter and 70.8 percent for the six months but the 2012 six months numbers were at a high of 75.8 percent.
Expenses | D&G was able to cut cost even as revenues rose. Marketing cost declined by 9 percent to $497 million, which the company attributes savings as a result of funds expended in 2012 on Jamaica’s 50th independence celebration. Cost containment and the outsourcing of the distribution of its products led to the reduction in general, selling and administrative cost with a fall of 9 percent to $542 million for the six months to December.
Finances | Cash resources climbed to $1.7 billion at the end of 2013 from $1.2 billion in 2012 but receivables jumped to $2.95 billion from just over a $1 billion in 2012 and $1.1 billion in June 2013. The company attributes the rise due mainly to full credit being given to its associated distribution company.
Related posts | D&G, Carreras & C&WJ now Buy Rated | D&G $1billion pay day | Profit inches up at D&G
D&G $1billion pay day
Desnoes and Geddes (“D&G”) advised the Jamaican Stock Exchange that they have sold their 5% shareholding in Brasserie Nationale d‟Haiti (“BNH”) and their 10% shareholding in Windward & Leeward, St Lucia (“W&L”) to Heineken (“HKN”) on 19th December, 2013 for a total value of J$982,486,000 (US$9.26 million).
“This is the right time to dispose of these minority shareholdings as we have ambitious plans for Red Stripe with several major initiatives being undertaken. These include the installation of our co-generation plant, plant optimization and Project Grow, which is the conversion to locally sourced raw materials. We are focusing on growing the Red Stripe business locally and internationally,” commented Cedric Blair, Managing Director of Red Stripe.
 “The breweries in Haiti and St. Lucia will continue to brew Guinness under license for Diageo, in addition to the other licensed breweries in Guyana, Trinidad, the Bahamas, St. Vincent, Belize, Grenada, St. Kitts, Barbados, Panama, Dominica and Antigua.” added Blair.
The sale is not a surprise as the company had reflected the values as investment available for sale in the last audited financial statements at a value of $960 million. The value was determined by professional business valuators based on an a recent bid made for the shares by a third party, suggesting the company’s intension to sell.
Related posts | Profit inches up at D&G | D&G poor 4th quarter
Profit inches up at D&G
Desnoes & Geddes, the brewers of Red Stripe beer is reporting moderate growth in after tax profits, moving by 8 percent to $368 million from $340 million in 2012. Sales barely grew from $3.1 billion to $3.28 billion in a quarter when local sales were up 14 percent to $2.8 billion and exports were down from $643 million to $465 million with the shift of the production of beer to USA.
The company spent less on marketing, $266 million versus $313 million in the 2012 quarter while general selling and administrative expenses declined to $288 million from $310 million due most likely to the transfer of this side of the operations to Celebrated Brands, their joint venture distribution arm. The transfer may also have impacted the dollar value of sales. Other income turned a loss of $8 million compared to a surplus of $59 million in 2012. On the other hand D&G’s share in the joint venture distribution was a positive $19 million.
Segment results | In spite of the climb in local sales and a decrease in marketing spend, segments results show profit for the local operation was flat at $553 million while exports rose from $210 million to $283 million.
 Financial Position | At the end of the quarter, the company has cash of $1.38 billion but receivables jumped to $1.9 billion from $739 million in 2012; things in this area would look a lot better. The company’s reduced funds tied up in inventories from $1.36 billion to just over a billion at the end of September. D&G has no interest bearing debt with equity capital of $8 billion.
D&G dominates the beer market in Jamaica and a lot of sales have been lost over the last several years as governments placed increased taxation on the products it sells. This along with a sluggish economy has held back its growth in profits and by extension the stock price. In the short turn, the company has had to resort to various cost reduction measures to help improve the bottom line. The September quarterly figures suggest that the company needs a Jamaican economy recovery in order to start delivering decent growth in profits. Nevertheless, the rate of return on equity is around 20 percent, which is not that shabby.
Related posts | D&G poor 4th quarter | Major management changes at D&G | Profits on the improve for D&G
D&G to pay more
Desnoes & Geddes (DG) declared a first interim dividend for the year 2013-2014 in the amount of $0.20 per share and a special dividend of $0.05 per share payable on December 20, 2013 to shareholders on record as at November 22, 2013. The ex-dividend date is November 20, 2013.
The company reported profit that are up 8 percent for the first quarter to September.
The company paid a dividend relating to the 2013 fiscal year of 10 cents per share on June 25, 2013. In December last year there was an interim payment 20 cents per share.
Related posts | Profit inches up at D&G | D&G will pay 10¢ dividend
D&G poor 4th quarter
Desnoes & Geddes, brewers of the world renown Red Stripe Beer, reported flat profits of $1.2 billion for the twelve months to June this year. Redundancy payments of $311 million, of which $160 million was in the last quarter, and an adjustment of $88 million relating to taxation booked in 2012, bit into net profits.
June quarter results came in at $161 million compared to $472 million in the same quarter last year. The poor last quarter results is not indicative of future earnings. D&G had telegraphed the lackluster numbers when it declared a dividend in June of only 10 cents per share, which brought the total payment to 30 cents for the year.
Sales for the fourth quarter was $2.682 billion, 5 percent lower than the similar period in 2012 and for the full year, $10.369 billion or 6 percent below last year’s figure. A change from exporting brewed product to the USA market in the latter part of the 2012 financial year to licensing a USA based brewery to produce and market the product, resulted in a reduction in export sales from $3.4 billion to $1.93 billion. Domestic sales on the other hand grew by 13 percent in the quarter and 11 percent for the full year.
 The company claimed that improved domestic performance was buoyed by new innovations in both the brewed portfolio and a stronger performing spirits portfolio. Cost of sales for the fourth quarter at $1.666 billion and full year of $6.118 billion decreased by 6 percent and 12 percent, respectively, versus the previous year. This would be partly due to the shift of production for the export US market. The shift in export strategy resulted in a big boost to profit in the export segment, which doubled from $405 million to $834 million but the domestic segment profit was flat at $2.49 billion. The domestic segment picked up more overhead cost than before when they were shared with the larger production level. D&G managed to improve the gross profit margin from 37 percent in 2012 to 40 percent in 2013 and gross profit after marketing cost to 32 percent from 26 percent excluding special consumption tax.
Profit before tax increased by 28.6 percent to reach $1.87 billion when compared to last year due to growth in domestic volumes and improved margin, dividend income which jumped by from $60 million to $184 million and royalties that moved from $342 million to $556 million.
Despite the higher pre-tax profit, result after tax was negatively impacted by a higher overall tax rate compared to 2012 when 25 percent was used compared with 30 percent in this year’s results.
 Regarding marketing, selling and administrative expenses, the company stated, “Marketing expenses of $190 million for the fourth quarter decreased by $42 million or 18 percent compared to last year mainly as a result of our new export model where expenditure to promote our US exports is provided by the licensee in America. General, selling and administrative expenses for the quarter were $29m (8 percent) above last year. The company’s joint venture with partner Pepsi Cola Jamaica, Celebrations Brands Ltd, began successful operations in most distribution hubs previously operated by Red Stripe and contributed a small profit to D&G’s results.”
The results helped boost cash from $973 million to $1.7 billion after dividend payment of $843 million and $880 million, investment in fixed assets and the joint venture company and growth of $500 million in receivables offset by current liabilities that rose by $500 million as well. D&G ended the period with equity capital of more than $8 billion inclusive of deferred taxation.
Insider call | Keep an eye on this one for future developments.
Related posts | Major management changes at D&G | D&G will pay 10¢ dividend | Profits on the improve for D&G | D&G or C&WJ: to buy or not?
Profits on the improve for D&G
Desnoes & Geddes is reporting improved results for the nine months to the end of March this year with profits after tax up 30% to $1,050 billion, however in the latest quarter, profits was down 18% to $243 million after tax. The company took a $152 million charge, in the third quarter for making workers redundant, flowing from the decision to transfer the sales and distribution of its products to Celebration Brands, a joint venture company with Pepsi. The company’s management indicates that the amount written off in the quarter is 50 percent of the total separation cost. Based on these numbers Investor’s Choice, a sister publication to ICInsider.com, is projecting 66 cents per share earnings for the year after the one off staff separation cost, but expect earnings to close in on $1 per share in the 2013/14 year as growth in sales and cost cutting improve profits.
Overseas production | The results reflect the decision last year to switch the production and sales of Red Stripe to the USA. Export sales are down as a result, but so is cost relating to exports. The difference is a plus for the bottom line for D&G. Marketing cost is one area of major savings as the company no longer picks up that cost in the USA market. Gross margin for local and exports climbed during the nine months period. Local sales grew to $2.67 billion up from $2.56 billion in 2012 and for exports it was $564 million in the current fiscal year versus $450 million, but exports earnings jumped to $530 million after marketing cost, a large improvement over $127 million reported in 2012. General selling and administration cost rose from $906 million to just $938 million for the 2013 period.
 Local sales climbed 12 percent over the same period in 2012 and was driven by the launch of the new beer, Talawah, a stronger performing spirits portfolio and price increase, the company reported. Local marketing cost increased by $21 million primarily due increased spend to promote and televise Red Stripe Premier League football.
Financial position | The group is in a healthy financial position as the improved results have contributed to cash moving from $230 million in March 2012 to $1.964 billion, after paying $560 million in dividends in December last year. Current assets exceed current liabilities comfortably by almost two to one, borrowed funds were only $157 million.
D&G has in the past stuck to paying out around 80 percent of profits as dividends and if this policy is maintained then the upcoming dividend to be considered this week should be around 30-35 cents per share. With the present price being $4.15 the annual yield will be around 12 percent making the stock very attractive.
Stock outlook | Investor’s Choice’s analysis points to the prospect of potential good growth levels for this company, as the local economy as well those overseas, show improvements in the years ahead. The major risk to this company is any weakness in the economy and potential for government to impose addition taxes on the products. On the positive side, the company is dominant in the local market and is enjoying increased acceptance of the flagship product Red Stripe overseas.
D&G or C&WJ: to buy or not?
Hi John: Should I buy more Lime stock or D&G? I already own some Lime shares. What was the last dividend paid by D&G? Thanks for your advice.
Response | That is a tough question. By the way there is no such company as Lime. Unfortunately the stock exchange has, in their wisdom, bastardized the system by trying to suggest that Cable & Wireless has had a name change but that is not so. There is no legal limited liability company such as Lime listed on the exchange. Lime is purely a brand name and not the real company name. It seems to me that the exchange is totally confused. They have the name Lime for the company with the ordinary shares but they did not change the name of the preference shares which are still listed as Cable & Wireless. Drawing a line from what they have done, anyone not knowing the true situation would assume that there are two separate telecom companies listed, one called Lime and one called Cable & Wireless. Why JSE persists with this aberration is yet to be determined as there is no rationale for it, but then the stock exchange is doing many strange things these days. It makes one wonder if they are really serious about running a stock exchange at all.
D&G | Now to the question you asked. My investment company owns shares in both Cable & Wireless and D&G. First, the last dividend paid by D&G was 20 cents in December last year and another should be paid in June or July this year. They normally pay out 80% of profits each year so the next dividend could be around 40 cents since we project about 80-85 cents earnings per share for the current year to June.
D&G’s quarterly results are expected next week and they should have enough momentum to surprise the market and push the stock price up. I really like it as they have cut a lot of costs out of the operation with the switch of production of Red Stripe to the USA. The local market seems to be holding up well based on the last set of results released. We see further demand in the next fiscal year that should continue to move the stock price higher.
C&WJ | We still like and have great hopes for Cable & Wireless. If fact, we love turnaround companies because if we get it right and time the entry into the stock, we will make above average returns. They have been cutting costs and revenues should start rising from the new pricing strategy adopted for cell calls last year. These moves allowed them to pull in more than 250,000 new users. The revenue from those phones should be earned for the full 12 months this fiscal year instead of only part year as was the case for the 2013 fiscal. The calculations we’ve made indicate strong profits this year from increased revenues and reduced costs, the latter based on cost cutting as well as improved margins resulting from re-pricing when the interconnection rate were lowered last year.
 Our main concern in the short term is the redundancy charge that we estimate to be around $3 billion that could cause the market to react negatively when the final 2013 numbers are released in a few weeks’ time. That doesn’t really bother us, as that reaction in our estimation, will be short-lived as investors start to see major improvement in the operating results starting in the June quarter. One may want to hedge one’s bet, by buying more now but leave room to pick up some at lower prices should the market react negatively to the impact of the redundancy cost that will depress the results but won’t repeat in the new year. Not only will it not repeat, there should be cost savings from the move that will help boost profits. Either way, it’s a bit of a gamble but the price is so low now and the upside potential so great in our estimation, that there is less risk in buying now than to await the results.