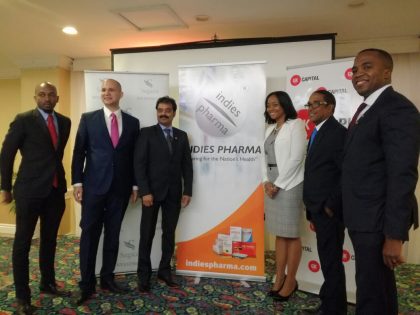
 Indies Pharma went to the capital market last week Thursday to raise $248.4 million from 174 million shares for its own use while existing shareholders offered 92.5 million units to raise nearly $139 million.
Information reaching IC Insider.com indicates that the offer that closed on Friday attracted some 2,800 applications, covering over than $1 billion and was about 2.5 times oversubscribed. GK Capital the lead broker pulled in about 50 percent of the inflows, our source indicates. The number of applicants sits just below the amount attracted by Victoria Mutual Investments which was in excess of 3,000.
The shares were mostly priced at $1.50 each with lower prices for shares reserved for selected groups. Only 60 million shares were set aside for the general public. The proceed for the shares sold by the company is expected to be used to pay off loans to its parent company and banks, working capital and funds the cost of the issue. The total issued shares currently amount to 1,158,553,500 units and the issue of 173,983,149 shares, raises the total shares to 1,332,536,649 units.
Indies Pharma is a pharmaceutical distribution company out of Montego Bay, which sold its first pharmaceutical 2005, and today distributes over 150 prescription and over the counter pharmaceutical formulations for Bioprist Holdings under the ‘Bioprist’ brand and operates the Trident Pharmacy located nearby in Sam Sharpe Square, Montego Bay.
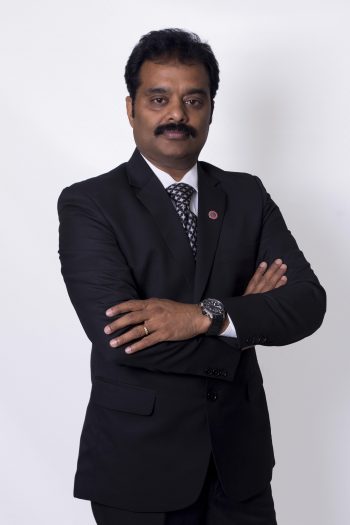
The chairman and founder of Indies Pharma
The Company currently services customers across the island, including over 400 pharmacies, private and public hospitals and government agencies including the National Health Fund as well as medical practitioners and directly to individuals.
Investors demand has pushed prices in the post IPO period to peak around 15 times current year’s earnings. On this basis, it seems likely that Indies Pharma will peak around $2.5 based on IC Insider.com’s projected earnings in 2018, of 17 cents per share, it could go higher with the high level of applicants for the shares.
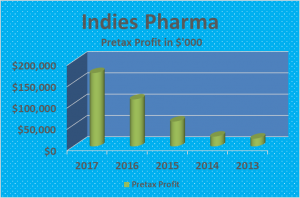
For the half year to April, revenues rose 10 percent to $301 million over the similar period in 2017 but profit is only up 6 percent to $73 million from $69 million before tax. IC Insider.com’s forecast is for a 16 percent increase in pretax profit to $200 million for the current year. The company could pick up additional sales and profit as a result of the publicity that emanates from the IPO and subsequent listing.
 The Company currently services customers across all 14 parishes of the island, including over 400 pharmacies, private and public hospitals and government agencies including the National Health Fund as well as medical practitioners, and directly to individual end users.
 Indies is not the cleanest entity to come public in recent years. The prospectus shows that there are clear areas of management weakness that need sorting out, but they are not alone, Elite Diagnostics exhibited some similar traits in spite of having men with business experience as board members. The promoters and directors should never have allowed the prospectus to be put out with scanned copy of the audited accounts from the book issued by the auditors. It does not telegraph a good message about management.
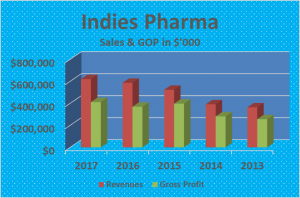
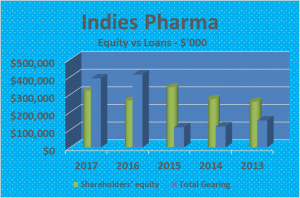 For one Gross profit which has been running between 75 percent to 62 percent between over the past five years with the half year to March coming out at very strong 62 percent, revenues grew an average of 15 percent for the past 4 years but only 6 percent in 2017 but is up by 10 percent for the half year to April. The company has been able to keep cost well under control and this has enable a richness in profitability with pretax profit rising 56 percent in 2017 89 percent in 2016 and 154 percent in 2015 after a 25 percent increase in 2014. The profit for 2016 would have been even better if there was not a loss on sale of fixed asset in the 2017 period amounting to $32 million but the rise in 2017 would likewise be less.
 Investors should recognize that not all IPOs are equal. They should also realize that there is a clear pattern that prices then to move up for strongly demanded issues and the undergo some correction. The data shows that the best time to buy after the IPO closes is on the first day or two or a few weeks after when demand falls off and supply increases as short term investors try to offload.
 The investment objective of the Company is to generate attractive risk adjusted returns with an emphasis on principal protection by generating current income, and to a lesser extent capital appreciation, through investments primarily in Portfolio Companies using private credit instruments.

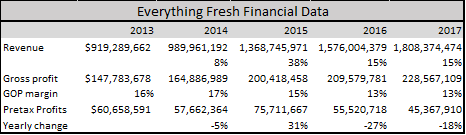 Operations started in 2008, data provided indicates that revenues hit $919 million in 2013 and generated pretax profit of $61 million. Revenues grew each year reaching $1.8 billion in 2017 with profit of $45 million before taxation of $8 million. The fall in profit for 2017 is due mainly to increase in payment for management team that was previously nominally paid, bringing it more in line with what more normal levels and foreign exchange losses of $4 million. Revenues and profit growth slowed but in 2015 revenues started to rise but lower profit margins resulted in a reduction in profits.
 The company intends to pay out up to 85 percent of its net income as dividends to shareholders, payable on a quarterly basis. The target dividend yield is over 7 percent on the IPO price.