Profit at Lasco Distributors is 26 percent higher for the year to March 2021 at $909 million, but profit before taxation climbed a much stronger 36 percent to $1.1 billion from $818 million in 2020 as cost reduction and moderate revenue growth of four percent helped with the increase in the bottom-line. Pretax profit in the fourth quarter rose 23 percent to $246 million over $201 million in the 2020 period.
 The company enjoyed a ten-year tax profit break and is now subject to full taxation as of October 12, last year.
Gross profit margin came in at 18 percent for the year, down from 19.4 percent in the 2020 fiscal year and the prior two years. Revenues climbed for the fiscal year to $20.3 billion from $19.5 billion in 2020 but fell three percent in the final quarter to $5.06 billion, from $5.195 billion in 2020.
Administrative and other costs fell 10 percent for the year to March to $2.13 billion from $2.37 billion in 2020. Staff cost fell from $1.72 billion to $1.56 billion as the number of workers fell from 532 to 509. Selling and promotion expenses fell from $703 million to $549 million.
Finance cost dipped from $15 million to $5 million as the company continues to pay down loans that stood at $1.05 billion at the end of March 2020 to $820 million at March 2021, with $454 million earmarked to be repaid in 2022 fiscal year. Taxation charged for the year amounts to $207 million, up from $93 million in 2020.
 The principal activity of the company is the distribution of the manufactured products of Lasco Manufacturing that includes soy-based products, juice drinks, water and packaging of milk-based products and Pharmaceutical and other products manufactured by third parties.
Shareholder’s equity stood at $6.5 billion at the end of March 2021. Cash funds and investments amount to $2.69 billion after the company generated cash funds of $1.27 billion before working capital and capital financing needs and paying a dividend of $179 million.
Lasco generated earnings per share for the year of 26 cents, up from 21.3 cents in 2020. ICInsider.com projects earnings of 40 cents for the fiscal year to March 2022 and 45 cents for 2023.
The stock last traded at $4, with a PE ratio of 10 based on the reported earnings and 9 based on the 2023 projected earnings. The price target to March 2022 for the stock is $6.
 Pretax profit jumped a strong 83 percent for the quarter, to $457 million from $249 million in the 2020 March quarter and 46 percent for the 12 months to March, with $1.75 billion up from $1.2 billion in 2020. The profit is subject to full taxation as of October 12, last year.
 Profit attributable to shareholders was $278 million in the quarter, up from a loss of $971 million in the 2020 quarter. Earnings per share amount to 23 cents for the quarter.
 For the six months to March, profit after tax grew 20.7 percent to $112 million from $92 million in 2020, with revenues coming in 13 percent ahead of the 2020 income of $876 million to close out the March 2020 half year at $989 million.

 The company reported their full year results to March this year, with profit before tax of $141 million, up slightly from $137 million earned in 2020, but below the forecast in the prospectus.

 Net profit attributable to shareholders grew US$1.02 million or 79.6 percent to a record US$2.29 million for the 2021 nine months period, from US$$1.28 million for the nine months to March 2020. For March 2021 quarter, net profit climbed to US$1.03 million from a loss of US$355,800 in 2020.
 Gross profit rose at a slower pace to that of sales growth, with an increase of just 3 percent to $416 million, from $404 million in 2020, which management attributes to a shift in sales mix during the period. “Revenue on some of our higher margin products declined slightly, we saw increases in lower margin product sales which drove the top line,” the directors reported in their commentary on the results.
 Cash flows from operating activities generated $541 million for the nine months, up from $387 million in 2020, but after paying dividends of $100 million, repaying loans and lease commitments of $92 million and providing working capital of $210 million was retained and added to the balance of cash funds of $599 million previously pushed cash on hand to $809 million, an increase of 52 percent.
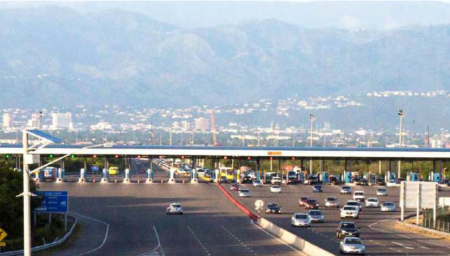 The performance is commendable, viewed against the modest rise the company enjoyed for the 2020 period with two and a half full months of uninterrupted service. The company reports that revenues for March 2021 increased by 5.63 percent over March 2020.

