 National Commercial Bank Jamaica, (NCB) approved the payment of an interim dividend of 45 cent per ordinary stock unit to be effected on February 20, 2015, for stockholders on record at February 6. The ex-dividend date is February 4.
The amount to be paid represents 51.7 percent of the reported profit of 87 cents per share for the quarter to December and just under 40 percent of the profit of $1.13 per share adjusted for the up front charge of the bank asset tax, the amount cannot be spread out over the full year on a month by month basis as was done in the past based on new accounting standard. The latest payment, if maintained for the balance of the year, would translate to $1.80 per share, a bit less than the total paid last year. In 2014, NCB hiked the final dividend to 96 cents per share to stockholders in December, from only 16 cents, in the prior year, December. The final payment for 2014 brings the total dividends for that year to $1.98. They made dividend payments of 35 cents per share in August, 35 cents in May and 32 cents per share on February last year.
IC Insider has been reliable advised, that the banking group decided to up their dividend payments to be ahead of Scotia Group and payment should continue at the heightened levels going forward, effectively moving away from a policy that was chopped and changed for several years to the disgust of many shareholders.
NCB modifies dividend payments
JSE stock moved to Buy Rated list
 The Jamaica Stock Exchange shares which were issued at $2.85 in the IPO in 2013, dropped last year to a low of $1.50 and the stock languished below $2 for months begging to be bought but with a few takers. This past week it hit $2.
At the close of last week, there was a bid in to buy 282,565 units at $2, but selling has dried up substantially. The prospects for the company is bright. Investors may be looking at 2014 performance to guide them, but it is 2015 onwards where the exciting times will be, this why IC Insider moved the stock from Market Watch to Buy Rated.
For the nine months to September last year, the JSE reported profit for the quarter of $11 million up from a small loss in the June quarter and for the first six months of the year. The big change in the September quarter resulted from a large block of shares traded that provided increased one-off income but also the recovery of $6 million in bad debts. For the year to September the JSE reported only $8 million in profit or a mere 6 cents per share, but bad debt recovered amounted to $10 million before tax. Revenues climbed to $89 million in the September quarter, an increase over the $73 million garnered in 2013. For the year to date revenues jumped $41 million to hit $242 million. Quarterly expenses climbed from $85 in 2013 to $91 million in 2014, and for the nine months, from $247 million to $273 million or just over 10 percent, a slower pace than the income growth of 20 percent.
 Based on these results alone, the stock would at best be a hold and more likely a sell. Investment is about the future more than the past, and the latter is where the attraction is. The local stock market is exhibiting all the signs of a bull market in 2014. The early trading for the year to date is mostly positive. Increased market activity will mean more income from trading transactions. Increased prices will result in much more income from annual listing fees in 2015. More securities were listed in 2014 and more are expected in 2015 which will result in increased listing fees and the possibility of increased trading opportunities going forward.
Some of the factors supporting the above can be found in strong technical indicators pointing to a strong market ahead, sharp decline in interest rates and projected low inflation. Additionally, the fall in the price of oil and other commodities on the world market will provide consumer with added disposal income to spend and this is likely to improve the profits of many listed companies and should result in increased gains in stock values and trading volumes. Political winds may be blowing over the market, with elections due by 2016, but that should not stop investors from picking the stock up cheaply, if they can, and await what will be a huge pay off in two to three years’ time as the market gets back to full life, in a low inflation, low interest rate environment. The JSE had cash and investments at the end of the period of $375 million equity of $571 million with no borrowed funds.
Caribbean Producers have been restored to the Buy Rated list based on strong revenue growth in the September quarter that suggest higher profits in the current year compared with the 2014 results.
A Lime money wallet in your pocket
 Cable & Wireless Jamaica plans to launch its own mobile wallet as early as this year. It would provide money payment services for those without banking accounts, the company chief executive says.
“We are going to hopefully launch this year the M-wallet. We are going to create the ability of the average Jamaican with a cell phone to engage in sophisticated banking services as never before for those people who are unbanked,” Cable & Wireless president Garfield Sinclair said at the JSE 10th Regional Conference held at the Jamaica Pegasus Hotel on Tuesday.
Local smartphone users already can pay for goods and services using apps including Paypal and Payoneer. However Cable & Wireless could offer the services similar to m-pesa money transfer system on phones in Kenya. It allows phones to transfer cash using SMS text without internet connectivity.
The jump towards mobile wallets however requires a strong uptake to cover start-up costs. Just this week US based Amazon, the largest online retail store announced plans to fold its mobile wallet after just six months amid a slow take up. It reportedly offered loyalty points but failed to integrate with debit and credit cards.
Jamaican Teas’ profits up 28%
Jamaican Teas stock gained the most in the junior market on Wednesday
Sales were helped by 91 percent jump in exports, moving from $55 million to $103 million, Sales in the prior year included Real Estate sales of $21.75 million, excluding these sales, revenues would be up by 26 percent for the quarter. The increase in exports, relate mainly to supplies to the US market and is partially due to the appointment of a new Distributor for the North East USA and expect that this will result in further improvement in sales. Sales also benefited from the launch of four new products during the period. Sales for Supermarkets are up 9 percent compared to the comparative quarter, in 2013, however, profits are flat. The jointly owned Supermarket in Montego Bay showed a reduction in losses which was helped by certain actions taken to reduce cost in 2014.
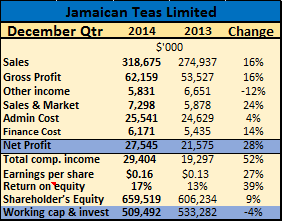 Gross profit margin increased to 24.3 percent from 24 percent in 2013, while gross profit increased 16 percent to $62 million but cost rose in other areas, with marketing climbing 24 percent to $7.3 million, administration by only 4 percent to $25.5 million and finance used to generate revenues in the period is up 14 to $6.2 Million.

The Orchid property being developed that should add to Jamaican Teas’ profits in 2015 & 2016.
Barring any unforeseen developments, 2015 could produce the best financial performance far. The stock which is now at $2.55 seems to have much room for growth.
Paramount’s profit leaps 163% in Q2

One of the branded product distributed by Paramount Trading
The improved results for the latest quarter, came from a 39 percent climb in revenues over the similar period in 2013, with revenues of $231 million versus $166 million in 2013. The latest quarter’s revenues are the highest the company has had, since listing in 2013. Gross profit margin jumped from 46 percent in the August quarter to 58 percent in November and from 49 percent in the same quarter in the 2013. For the six months to November 2014 the profit margin increased to 53 percent from 49 percent in 2013.
The company launched a new line of lubricants during the August quarter but sales are in their infancy at the time. According to a company executive in commenting on the August results, the increased sales was mostly from new customers added as well as increased sales of a product to an existing customer, who was not supplied with that product last year.
Administrative, selling and distribution cost, which fell in the August quarter came out at $33 million from last year’s $31 million. For the six months period these expenses amounted to $64 million versus $66 million in 2013. With the release of the August figures IC Insider.com had projected profit to come in around $152 million in the current fiscal year or around $1.15 per share, the latest figures suggest that earnings per share will probably be closer to $1.40. At the current price of $2.80 the stock would be priced at a PE of only 2.2 making it a very good buy, bearing in mind that that many junior listings have been valued around 8 times earnings in the recent past, and around 6 times now, with the latter PE, the price should potentially get to $8.40 at the low end and $11 at a PE of 8. The company seems poised to raise its next fiscal year earnings to a much higher level than the above forecast (IC Insider.com forecast $2 per share for 2016) so there seems to be much room for the stock to deliver high returns to investors. These figures do not reflect income or profit that should flow from the company’s acquisition of the Tradewell chemical line which they purchased from the Lasccelles group or any other acquisition that they may undertake in the near term. It also assumes that revenues which include some new customers will repeat going forward.
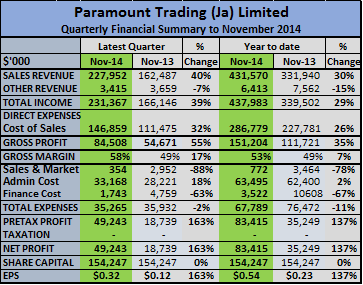 Financials| The profit to-date provided a strong 44 percent annualized return on average equity. Borrowed funds amounted to only $38 million, compared to the level of equity. Cash is up from $65 million but dividends of $23 million was paid out in December. Receivables which was at $178 million in August from $172 million at May, is down slightly to $172 in November, and represents an improvement considering the strong sales increase. Inventories at $203 million at the end of August and May, this year, jumped to $275 million in November but payables moved up moderately to $136 million from $128 million at the end of May.
The performance of the company during the quarter and for the 2014 justifies IC Insider.com elevating the stock to BUY RATED status in mid-October last year.
AMG flat sales push profit down 15%
 Revenues rose a strong 36.56 percent for the year to August 2014 for junior market listed, AMG Packaging, hitting $607 million but it increased by a much slower pace of 28 percent in the final quarter of the financial year, to $165 million.
Those strong gains may have cannibalized sales in the November quarter with flat sales compared with 2013 quarter, with revenues of $151 million. But the performance comes against the back ground of volumes sold, climbing a very strong 19 percent for the year. The fall in volume started from the August quarter as units sold increased by 23.4 percent, management stated in a release accompanying the May results.
While sales increased impressively in 2014 fiscal year margins came under pressure with only 23.7 percent for the year to August down from 33 percent in 2013. For the latest quarter gross profit margin comes out at 25.9 percent but could end up at 31.5 percent for the current year if sales volumes increase by 10 percent for the rest of the fiscal year. Gross profit for the quarter amounted to $34.4 million up from $33.3 million in 2013 but increase mainly administrative cost that rose 28.4 percent eroded profit slightly by 15 percent to $15.4 million from $18 million in 2013. The company got a double whammy, with the Jamaican dollar losing value, resulting in a 28 percent more Jamaican dollars having to be found to purchase a US dollar since September 2012, and the price of paper on the world market moving 22 percent from US$720 per tonnes at September 2012 to US$830 in August 2013 and now US$875, which it has been since June last year.
Receivables are down by $12.7 million from the amount at the end of August last year and so too is amounts in payables by $26 million. Cash funds grew to $33 million from $22 million while inventories is down from to $118 million at August to $113 million, which is nearly 4 months supplies based on sales in the quarter and is up from just two and a half months back in 2013 and seems to be a hedge against devaluation of the Jamaican dollar. But that is only a part of the story. A check on world prices for pulp shows a pretty sharp increase since 2012.
AMG has to continue to grow its business by continued strong volume growth to become a more cost competitive producer with lower unit cost. The company needs to put strategies in place to return volume sales to growth and needs to continue cost containment measures to ensure profit improvement going forward. With increase through put, unit cost of production will fall allowing more growth in gross to flow into overall profits. A bright spot for the company is the fall in the cost of fuel and electricity will help in keeping cost down for the rest of the fiscal year.
IC Insider’s forecast for 2015 is 90 cents per share and $1.50 for 2016 on the assumption that volume sales return reasonable growth.
Caribbean Cream’s Q3 profit up 19%
Kremi ice cream container
Based on the first quarter IC insider forecasted earnings to climb to 40 cents for the fiscal year and to rise to 70 cents in 2016. For the year to February in 2014, earnings came out at only 11 cents per shares, which was up from 5 cents the year before. IC Insider has revised the 2015 fiscal year results, to 22 cents and the 2016 to 60 cents. The reduction is partially due to a 64 percent jump in marketing and administrative cost in the August quarter compared with a 20 percent increase in sales revenues and a 28.5 percent increase in gross profit. For the period to November marketing, administrative and finance cost jumped by 56 percent to $173 million. The sharp increased marketing and administrative cost, looks like settling off, after the company revved up expenditure in these areas to better align management and operations with increasing business activity.
Last year, Management indicated that cost associated with the JMA Expo and development cost for the new Kremi advertising campaign, launched at the end of June, helped push cost in marketing and advertising. The new packaging for the retail products was launched in May, the company reported.
Sales revenues climbed 26 percent in November and is up from 20 percent in the prior periods and is up 22 percent for the nine months to hit $741 million. Growth in sales has slowed and is well down on the growth rate for the February and April quarters, at 48 percent each and 27 percent for the July quarter of 2013. Improvement in the plant and new packaging, should help in moving sales to a higher level, than the slower pace over the last three quarters.
Gross profit margin jumped to 47 percent in the latest quarter from 37 percent in the 2013 period but for the year to November the margin is at 38 percent up from 0 percent for the nine months period in 2013. Going forward margin should improve even more with the blast freezer installed in November which management says will cut utility cost with less usage and create capacity for greater production to enhance sales volumes. With the installation, Manager indicates they will be able to meet the increased demand for the 2014 Christmas period. The management report was released in January, accordingly, the information on demand would most likely be based on actual sales. The company increased prices ahead of the Christmas period but the increase may well have slowed down sales volume growth.
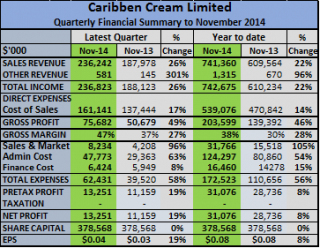 Kremi paid over $63 million in electricity cost in 2014 fiscal year with the last quarter at $18 million. The company will benefit from less usages with the more efficient freezer going forward as well as from the reduction in electricity cost with the fall in the price of oil and the pass through effect on JPS bills, to their customers.
During the year to November, capital expenditure amounted to $56 million spent on the blast freezer and was geared to improving efficiency in the factory. Equity capital stands at $261 million and borrowed funds at $155 million of which $12 million is due to be repaid in a year’s times.
The stock last traded at 80 cents each but with our forecast for the 2015 fiscal year that ends in February the PE works out at 3.6. The company is in the business of production and sale of ice cream and is listed on the junior stock exchange market.
Jamaican Teas 2014 profit drops
 Jamaican Teas reported sharply lower profit, last year to September, of $52.7 million versus $93 million in 2013, with earnings per share of 31 cents. The figures were reported in the group’s audited financial statements release last week.
The results emanated from sale revenues of $1.14 billion down from $1.23 billion in 2013. There was approximately $50 million coffee sales included in the 2013 results with none in 2014. In 2013 the real estate segment contributed $185 million in revenues compared to only $26 million in 2014 with most coming in the September 2013 quarter.
Gross profit margin shrank slightly from 21.89 percent to 21 percent for the year, helping to cut gross profit by $17 million. Other operating income climbed to $24.7 million from $12.9 million in 2013, partially due to losses on sale of, and impairment of investments incurred in 2013, amounting to $13.5 million, but did not occur in 2014.
The Orchid property being developed that should add to Jamaican Teas’ profits in 2015 & 2016.
Changes in our distributorship in the Florida at the start of the fiscal year resulted in some short-term fall out in sales and increased marketing cost. A new distributor was appointed in the US market that will provide wider distribution in some key cities within that country. Revenues are expected to benefit from this development starting with the December quarter. The 2015 revenues, should also benefit from the completion of sales of 16 units in the first phase of the real estate development in St Thomas. The supermarket in Savanna-la-Mar was close to a break even by year-end and while the one in Kingston remained profitable. The Montego Bay supermarket reported losses in line with what was incurred in the prior year.
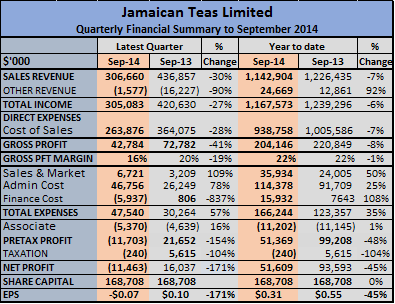 There was approximately $50 million increased borrowed funds at the end of the year, putting borrowings at $304 million. The profile of the debt changed markedly, with long-term loans accounting for two thirds of the debt at the end of the fiscal year compared with just 2 percent in 2013. The portfolio of investments including equities, stood at $123 million at the year-end and shareholders’ equity of $635 million.
The company imports of black and green tea in bulk for packaging and the distribution local and overseas. it also packages and distributes herbal teas and distributes other bottled water, coconut milk and other pre-packaged food items. the group operates supermarkets and is involved in the rental of residential properties and the development of real estate for resale.The stock is listed on the Jamaica Stock Exchange and last traded at $2.50.
Cargo Handlers’ Q4 profit doubles
 Profit for the September quarter at Cargo Handlers is up 117 percent over the 2013 results to $49.7 million from revenues that climbed a very strong 77 percent. Profit rose by a smaller 55 percent, for the nine months ending September this year, to $131.7 million or $3.52 per share from revenues for the nine months of $220 million.
Other income, mainly foreign exchange gains, fell 13 percent in the quarter and was flat for the year, at $16 million. During the year the company earned $13.6 million from leasing and $8.9 million from management fees charged to a related party – Bulk Liquid Carrier and Petroleum Transport Ltd.
Administrative expenses dropped 31 percent in the quarter and 9 percent for the year but operat9ing expenses climbed 37 percent for the quarter and 22 percent for the year well below the increase in revenues. The company paid a dividend of $1.80 per share during the year for a yield in excess of 13 percent based on the stock price of $13.50 at the start of 2014.
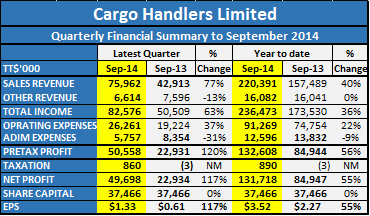 Looking forward the foreign exchange gains earned in the last two years is unlikely to repeat in 2015 as the Jamaican dollar is unlikely to slip to the same degree it did in the recent past, so earnings will need to exclude most of these gains which amounts to just over 40 cents per share. Investors could be looking at earnings per share around $4.80 in 2015. At a price of $16 the stock is undervalued but they are difficult to come by.
Equity capital stood at $200 million and net book value at $5.33 per share. There is virtually no borrowings and cash of $93 million.
The company is involved in primarily in stevedoring services and is in the process of acquiring a petroleum haulage company which it now manages pending completion of the sale. The stock is listed on the Jamaican Stock Exchange.
Access dominates with 1.2b shares
 There was trading in 135,339,271 units of Access Financial shares which were primarily sold by Mayberry from their holdings and purchased by Proven Investments, in 33 trades. The acquisition places Proven at just under 50 percent ownership of the company. The trade was by far the largest on the exchange for the day and leaves less than 10 percent of the ownership in the wider public’s hands.
Trading on the Junior Market closed with only 6 securities traded and ended with 135,592,084 units valued at $1,218,415,832 changing hands. The JSE Junior Market Index fell 4.72 points to close at 684.63, with the price of only 1 stock advancing and 3 declining.
Even as the index slipped, the junior market continues to reflect renewed interest with 4 securities closing with no bids to buy and there were 9 securities that had no stocks being offered for sale. At the close of the market, the indicators point to rising prices ahead as there were 6 stocks with bids higher than their last selling prices and only 1 stock with the offer that is lower.
Stocks trading are, Lasco Financial ended trading with 3,000 shares as the price rose 2 cents to 98 cents, General Accident ended with 3,000 shares changing hands at $1.75, Lasco Manufacturing had 8,813 shares changing hands to close at $1.12. Access Financial closed with 135,339,271 units trading as the price slipped 5 cents to $9, Caribbean Producers finished with 1,000 shares trading lower by 2 cents to $2.03 and Lasco Distributors ended with 237,000 shares trading 4 cents lower at $1.41.