Scotia Group steadies ship

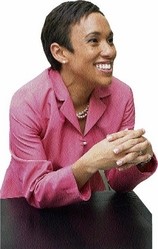
Jackie Sharp - CEO Scotia Group

Jackie Sharp – CEO Scotia Group

Scotia Group reports profit $6.16 billion for the nine months ended July 2015 compared with $7.97 billion for the period to July, 2014. The reduction was impacted by Asset Tax expense of $1.29 billion fully booked from the first quarter as well as an increase in the Asset Tax rate imposed in May 2014.
Profit for the July 2015 quarter, was $2.31 billion, a shade off from the results for the April 2015 quarter of $2.36 billion, but well down on the July 2014 quarter of $2.9 billion. The decline in the quarter is due mainly to a fall-off in net gains on investment assets of $240 million, net interest income of $140 million, foreign exchange trading gains of $220 million and insurance revenues of $230 million.
Earnings per share for the nine months amounts to $1.93 and for the last quarter 72 cents and should end the year around $2.75.
The Group reported lower insurance revenue, lower net gains on foreign currency activities and financial assets in the Investment Management segment of the Group with total revenue for the nine months of $26.3 billion, a decrease of $319 million from the prior year. For the July 2015 quarter, total revenue of $8.62 billion was down $103 million from the April quarter. Net interest income after impairment losses for the period was $16.9 billion, an increase of $76 million versus the same period in 2014.
Scotia hq 25 9-14Expenses have been held quite tightly, resulting in an increase of $533 million or 3.7 percent when the Asset Tax is excluded for the nine months, while expenses were just $100 million more in a the third quarter, over the similar period in 2014.
Total assets increased year over year by $23.4 billion or 5.8 percent to $424 billion as at July 2015. The growth was primarily attributable to increases of $4 billion or 2.9 percent in Loans, net of allowance for impairment losses to $148.7 billion, $8 billion or 5.4 percent in investment and pledged assets and $8.8 billion in other assets resulting from higher retirement benefit asset. Loans as a percentage of total assets have declined from 36 percent to 35 percent as of July this year. The ratio needs to be moving in the other direction if profit is to commence growing at an attractive pace. At a quarterly rise around $1 billion the growth in loans is not strong to delivery good bottom line growth and help the stock to be above the average of the market.
An interim dividend of 40 cents per stock unit payable on October 15, 2015, to stockholders on record at September 23, 2015 was approved.

Lower income mauls Scotia Invest profit

SINV signTwo areas of major fall out for income in 2015 pushed profits sharply down for Scotia Investments (SIJL) for the year to July 2015. Gains from financial assets fell in a big way from $266 million in 2014 to only $24 million in the July 2015 quarter and from $576 million in the nine months period last year, to just $173 million.
Net interest income declined by $300 million in the July 2014 quarter and fell $750 million for the year to July, contributing to a disappointing year.
SIJL reported net income of $736 million for the period ended July, 2015, a huge decrease of $629 million, when compared with the net income of $1.36 billion for the period to July 2014. Net income for the quarter was $283 million, down $34 million or 11 percent below the $317 million earned in the April quarter but is down 48 percent on July 2014 profit of $541 million. Earnings per share of $1.74 and for the July quarter, earnings per share of 67 cents.
Total revenues, comprising net interest and other income for the period was $2.43 billion, a reduction of $757 million or 24 percent below the corresponding period last year and $761 million for the quarter, down $95 million or 11 percent compared to the previous quarter.
Total operating expenses for the period amount to $1.34 billion, up $102 million or 8 percent over the corresponding period last year, due partly to the increase in the asset tax rate from for regulated financial institutions and higher salaries and staff related costs. The operating expenses for the quarter were $366 million, down $45 million or 11 percent lower compared to the last quarter.
SIJL will clearly end the financial year below $3 per share to October this year with profits well below the $1.79 billion or earnings per share of $4.23 generated for the 2014 fiscal year.
An interim dividend of 45 cents per stock unit payable on October 15, 2015, to stockholders on record at September 23, 2015 was approved.
Caribbean Producers BUY RATED again

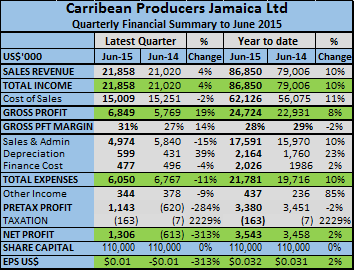
CPJ Mkt PlCaribbean Producers reported profit of US$3.54 million or 32 US cents per share for the year to June 2015, versus $3.46 million or 31 cents in 2014, according to the company’s audited financial statements. Sales brought in $86.85 million during the year compared with $79 million in 2014, a gain of 10 percent and for the quarter sales were up just 4 percent over 2014 to $21.86 million from $21 million in 2014 while profit came in at $1.3 million compared with a loss of $613,000 in 2014.
Profit for the latest quarter is 23 percent higher than the $922,000 earned in the March quarter, a period that is usually the highest earner. Earnings per share ended at 32 cents for the year or close to J$3.75.
Gross profit margin jumped in the June quarter to 31 percent and well over the 27 percent enjoyed in the 2014 quarter and higher than the 28 percent for the full year. Gross profit climbed as well by 19 percent to $6.8 million for the quarter much faster than the growth in revenues and was up by 8 percent for the year a bit less than revenue growth. Selling and administrative expenses fell in the quarter, by 15 percent but was up 10 percent for the year.
Profits seem to be moving in the right direction with cost falling in some areas and profit margin improving. At the current price of J$2.50 the stock is undervalued as it should be moving into the J$3 region with these results. The group has been seeing improvement in the St Lucian operations and that could be improved upon in 2016 fiscal year. CPJ 6-15Caribbean Producers made a profit of $447,000 in the September 2013 quarter but made on $2,500 profit in 2014, the results for this year’s September quarter should be better as 2014 had certain cost associated with new products and the holding of prices for certain items sold to the hotel sector during that period.
The bother continues to be the heavy debt, at $24.76 million which is down from $25.2 million in 2014, while equity is up to $19 million from $16 million in 2014 thus improving the debt to equity ratio quite a bit. The probability exists that there should be an improvement in 2016 as well, as profit continue to perform, thus building up equity.
IC Insider is restoring it BUY RATED stamp on this one.

FCIB from consolidation to expansion

Years of adjustment, heavy loan loss provisioning, contraction and now consolidation at FirstCaribbean International Bank have started to bear fruit and is now leading to expansion. The bank that sprawls over the Caribbean has suffered with the declines in economic activities within the region that saw it writing off large amounts of loans that went bad.
FCIB MPThe struggles to overcome the drag that the economic pressures placed on the bank that is a subsidiary of the Canadian Imperial Bank of Commerce has been tough and can be seen in in the performance of loans and assets. At April 2009, loans which stood at US$6.9 billion and assets of $10.6 billion, slipped to just $6 billion and $10.9 billion, respectively by July this year.
“We have just recently announced that the Rendezvous Branch in Barbados will be converted into a sales centre catering to Platinum Banking, Business Banking, Corporate and International Banking customers. We have opened new branches across the region, most notably the Santa Cruz mini-branch in Jamaica. Another branch at Fairview in the Montego Bay area is under construction. Additionally, we recently opened a Representative Office in Aruba and have plans to open a full service branch in 2016, as part of our expansion plan for the Dutch Caribbean,” Rik Parkhill, Chief Executive Officer of the bank stated in a report to shareholders.
The Bank enjoyed improving net profit of US$34 million in the third quarter, up $11 million or 49 percent over the prior year’s third quarter profit of $22.9 million. For the nine months, net profit attributable to shareholders was $85 million. In 2014 the bank reported a loss of $173 million after taking a one off hit of $116 million for Impairment of intangible assets.
Total revenue during the third quarter and the nine month period declined moderately compared to 2014 primarily due to lower interest earnings from loans and securities.
Operating expenses over the nine month period were down by $3 million and for the quarter $1 million compared with the same periods last year. Loan loss impairment expense was of $7 million in the third quarter and $35 for the year to date, were sharply down, on the $23 million and $193 million for the nine months in 2014 respectively. Results have been converted to US$ at an exchange rate of US$1 to BDS$2.
“ Some countries continue to experience low credit demand, additionally interest margins on loans and securities yields were lower. While productive loans balances are down 1 percent over the prior year, an improved performance over the second quarter of 2015 was recorded with 1 percent or $80.6 million in loan growth as a larger proportion of the sales pipeline was converted into productive loans during the latter half of this quarter. Additionally, non-productive loan balances were down 18 percent to $651 million compared with the same period last year as efforts continue to further strengthen the quality of our loan portfolio,” the bank reported.
The turnaround why commendable, the bank needs to find means of growing its loan portfolio and a reasonable pace again in order to generate attractive profits increases going forward for the stock to be an attractive buy.
FirstCaribbean is listed on the Barbados and Trinidad and Tobago stock exchanges and were last traded at TT$5 and Bds $1.89.

FirstCaribbean leaving Belize

FCIBFirstCaribbean Bank, a subsidiary of CIBC Canada, is set to exit banking activities in Belize the Central American country with lots of land and a small population of 332,000.
“The bank entered into an agreement on August 3, to sell its net assets in Belize to a local banking institution, Heritage Bank Limited. At July 31, 2015, assets for the Belize operation totalled US$169 million, while total liabilities were US$140 million”, FirstCaribbean said in a note to their July interim financials. The bank currently operates 5 branches in the country.
Upon the completion of the sale and related wind-up activity the Bank will discontinue its operations in Belize. The transaction is subject to approvals from the Central Banks of Belize and Barbados, along with other related governmental authorities. The transaction is not expected to have a material impact on the Bank’s capital ratios, the FirstCaribbean report stated.
The sale will make a huge difference to the acquiring bank as the acquired assets will more than double its size. Heritage Bank had assets of Belize $244 million Hertitage Bnkat the end of 2012 which fell to $204 million at the end of 2013, with deposits falling from $228 million at the end of 2012 to $187 million and cash declining from $110 million to $57 million.
The bank made a profit of $1.76 million in 2013 after tax and $2.2 million in 2012 but had accumulated deficit of $21 million with net equity of $14 million at December 2013. It takes two Belizean dollar to purchase one US dollar.
Heritage has 10 branches in Belize according to information on their website.

Blue Power disappoints again

blue powerFor the six consecutive quarters, soap manufacturer, Blue Power, disappoints investors, with a fall in profit compared to the prior year’s results. For the three months to July this year, the company reported profit before tax of $21 million compared to $29 million in the same period last year, a fall of 28 percent.
Revenues for the period ended at $306 million that are up 8 percent from the $282 million for the same period last year and a big recovery from $260 million experienced during the poor April quarter.
The five-year tax-free concession the company enjoyed for listing on the junior market ended in April, resulting in an estimated tax liability of $2.19 million which reduces net profits to $18.60. The profit performance helped to generate gross cash flow from operations of $24 million versus $28 million in 2014.
While sales grew, gross profit fell and gross profit margin declined with the former falling to $64 million from $66 million and administrative and other expenses rose 14 percent to $46 million.
The contribution of Lumber Depot division to the before tax was $7.55 million and $6.09 million in 2014, while Blue Power division contributed $13.24 million and in 2014, profit of $22.6 million. Earnings per stock unit for the quarter fell from 51 cents to 33 cents.
Divisional sales had mixed fortunes with the lumber depot division enjoying an increase of $28 million to $212 million, while sales for the Blue Power division, declined by $3.5 million to $90 million in 2015 compared to July 2014 quarter. Sales for both divisions were higher in the July quarter than for April with the Lumber Depot sales also improved from $189 in April 2015 and Blue Power division from $71 million.

Blue Power jumped to a 52 weeks' high of $14 on Monday

Blue Power jumped to a 52 weeks’ high of $14 on Monday

“We attribute some of the improvements in the Lumber Depot division to the whole range of changes made in the previous six months in terms of service, advertising, web site development, etc. In the Blue Power division, we resumed sales to one of our major customers while shipping a number of containers of laundry soap to Guyana,” Dhiru Tanna CEO said in a release with the financials.
Cash and equivalent has risen to $168 million from $156 million in 2014 and receivables declined to $74 million but Inventories jumped to $266 million from $220 million while loan financing amounts to just $8.7 million.
The stock which was previously given a BUY RATED grade lost it with the declining profits and no clear indication of a strong pick up in revenues to propel profits upwards to warrant a buy rating at this time.

31 seats for PNM poll suggests

PNM logoThe voters in the twin island state of Trinidad and Tobago go to the polls on Monday, September 7 in general election to elect a new government with polls showing a possible massive victory for the main opposition party, the PNM. The incumbent, the People’s Party Coalition – United National Congress (PP/UNC) won the last election with 29 out of the 41 seats that makes up the parliament. A recent opinion poll shows the governing party trailing the main opposition party by a large percentage.
If the actual results of the elections are close to what the poll indicates, it would amount to a massive victory for the PNM, with approximately 54 percent to the (PP/UNC) 43 percent of the popular votes. The PNM is likely to garner 31 or 76 percent of the 41 seats up for grabs, IC Insider calculations show. Two of the 31 seats are very marginal and could go either way.
The recent poll was conducted by H.H.B. & Associates was carried out on behalf of Guardian Media Ltd. According to the poll results, the People’s National Movement (PNM) is leading the race in voter support with just eight days to go before the election with 37 per cent of respondents said the PNM, while 30 per cent said the PP/UNC. The undecided respondents accounted for 31 per cent, while two per cent said Independent Liberal Party.
The poll was conducted between August 22 and 28, through the regional corporations in Trinidad. A random sample of 1,000 persons were surveyed.

Profit jumps 129% at Honey Bun

Honey bun 2Profit jumped 129 percent over the June 2014 quarter, after taxes for Honey Bun to $17 million for the June 2015 quarter and growth for the nine months period to $64 million versus $41 million, an increase of 58 percent, and cash flow from operation of $98 million from increased sales of 17.5 percent, to $672 million.
For the quarter sales grew 20 percent to $218 million from $181 million in 2014, whilst gross profit was up by a larger 24 percent. The company attributes the increase in sales to a strategic restructuring of the sales department. Gross profit margin increased to 45.5 percent up from 44 percent in the June quarter of 2015 versus 2014 and 44.9 percent for the nine months in 2015.
Export sales increased by 48 percent year to date. “The major increase in exports is as a result of our placement in ASDA stores in the UK” Michelle Chong, Chief Executive Officer said, in response to IC Insider.com enquiry, and is in keeping with the Company’s objective of increasing exports.
The problem in the past has been the last quarter with a tendency for lower sales and losses, is the company over this? “The company services a lot of schools and so the summer months are normally reduced due to the holiday season for July and August. We will always have this challenge but we have somewhat overcome a significant portion of it by way of the development of new products that are not directly geared for schools and by targeting other markets also. This has made a significant impact,” Chong stated in response to questions posed to her by IC Insider.com.
Hony BunLast year there were problems and added cost in the distribution department, it appears that the company is over that for 2015 fiscal. “We have outsourced over 50 of the distribution that was costing us excessively very successfully and last year we were also suffering from 2 of our major distribution vehicles being out of service and so we had to pay a lot for other vehicles to service the deliveries. These critical vehicles are now back in service” Chong said.
Honey Bun would have enjoyed savings in electricity and flour cost with the reduction of prices of oil and wheat on the world market. Chong agrees and indicated, “yes but besides the reduced rates we have also undertaken significant energy conservation on our own. We have also commenced the first phase of a large solar energy project”.
Receivables remained static at $56 million over June 2014 figure while Inventories fell to $45 million from $51 for the same period while payables were up to $59 million from $55 million. The company ended the quarter with $72 million in cash and investments, borrowed funds of $38 million and equity of $363 million. During the fiscal year a dividend totalling $11 million was paid more than twice the $4.7 million paid in the prior fiscal year.
IC Insider’s project a slight loss in the final quarter ending September this year with earnings for the full year to end at 66 cents versus 68 cents reported for the three quarters to June and 43 cents for the fiscal year to September 2014.

Carib Flavours profit up – Now BUY RATED

Ingredients input into Caribbean Flavours products

Ingredients input into Caribbean Flavours products

Focusing on the end results of Caribbean Flavours & Fragrances for the year to June 2015 with increased profit of 22 percent over 2014 would lead one to look elsewhere, but that would be a big error.
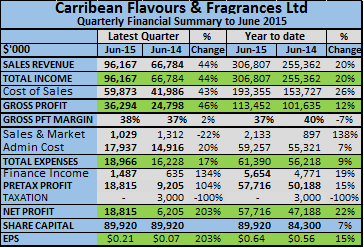
For while the nine months to March showed profit down marginally to $39 million from $40 million, profit for the March quarter was up 20 percent over March 2014 quarter but the June quarter increased by 143 percent to $18.77 million from just $7.6 million for June 2014.
The future much brighter that the past year, for the company that manufactures and distributes flavours mainly for the beverage, baking and confectionery industries and also sells food colouring and fragrances. The company audited financial statements show profit of $58 million or 64 cents per share versus $47 million or 56 cents in 2014, from sales that were up to $307 million from $255 million in 2014. It is the performance of revenues that is the most telling message to flow from the report that points to big improvement in profits to come. Revenues jumped 44 percent in the quarter to reach $96 million the best quarter by far for the financial year. CFF 6-15rAccording to the company’s board, “the economic environment has allowed the company to grow its revenues and profits by securing new markets for fragrances and increasing the volume of sales of flavours to existing and new customers in foreign markets. Based on the outlook for the coming year, it is expected that the company will continue to improve its profits whilst increasing its market share in the domestic and overseas markets”.
IC Insider has projected profits for 2016 at $100 million or $1.10 per share with increased sales and improving profit margins.
Net asset value is $2.25 per share, with the price of the stock on the junior market trading at $2.55 for a PE of just over 3 and 2.3 based on the forecast, indicative of much upside price potential.

General Accident lousy results

Gen Acc General Accident reported lousy first quarter results for 2015, with profit of $26 million and followed that up with even worse figures for the June quarter, just $457,000, and $26.6 million for the first half of 2015, compared with $88 million and $187 million respectively, in 2014. |
Investors were not pleased with the numbers and marked the stock down to a 52 weeks low of $1.30 from which it has made some recovery to $1.50 where it is now trading on the junior market of the Jamaica Stock Exchange.
“For the first half of the year, gross written premium grew to $3.8 billion, an increase of 10 percent over the same period last year despite a sharp contraction in property rates, operating costs also increased by 8 percent in line with our expectations”, management said in their report accompanying the results.
The report when on to state, “Nevertheless, claims charges saw a significant increase by 30 percent to $413 million from $316 and from $169 million for the June 2014 quarter to $228 million in 2015. This sharp increase in claims negatively impacted both our loss ratio and combined ratio which worsened from 86 percent (2014) to 106 percent for comparable periods, respectively”.
The company reported an underwriting loss of $59 million for the half year versus a surplus of $69 million in 2014 and for the Jun e quarter, a loss of $45.6 million compared to a surplus of $20 million.
Investment| Investments delivered reduced income for the first half of 2015 with $94 million earned, below the $125 million generated in 2014 and for the June quarter $50 million versus $68 million in 2014.
“Over short periods of time, our loss ratios may experience significant volatility. Nevertheless, we remain confident that the consistent application of General Accident’s standards and practices will continue to produce underwriting profits over the long-term. As a result, we expect our performance in the second half of the year to improve significantly” Paul Scott, Chairman and Sharon Donaldson, Managing Director reported to shareholders.
Looking forward, investment income could be under threat with lower inflation and interest rates locally and less likelihood of robust gain in the forex market. It will take good management of the various resources to grow income and profits going forward beyond 2015.
Earnings per share for the six months, came out at just 3 cents, down from 18 cents last year.