Revenues at GraceKennedy rose 9.7 percent to $117.8 billion, over $10.4 billion earned for the nine months to September over the same period in 2022. Profit before tax reached $8.8 billion, up by J$1.1 billion, or a 14 percent increase, while net profit after tax rose 14.2 percent to $6.4 billion.
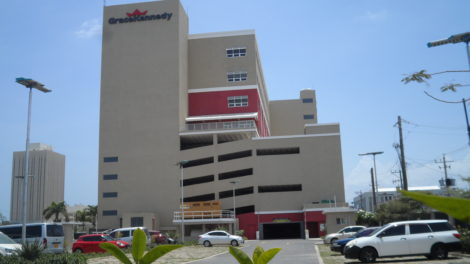 Profit attributable to stockholders hit $6 billion, a 15.3 percent increase over the corresponding period last year. Earnings per stock unit for the period were $6.02, compared to $5.23 in 2022.
Earnings per share for the full year ending in December should hit the $8 market, with PE ratio of 9 based on Thursday last traded price of $71.50.
The company stated that “GK’s food business demonstrated strong performance, with notable growth in revenue and profitability for the period. GraceKennedy Financial Group also delivered a positive performance, driven by strong top-line growth”.
A dividend of $0.65 per stock unit has been announced and will be payable on December 15, 2023, totalling approximately $643 million. This is the fourth and final dividend payment by GK for 2023, bringing GK’s year-to-date total dividend pay-out to approximately J$2.15 billion.
Profit rises 14% at GraceKennedy
Profit jumps 31% at Lasco Manufacturing
Profit climbed 31 percent after taxation of $258 million to $615 million in the September quarter this year at Lasco Manufacturing, from $469 million after provision for taxation amounting to $210 million in 2022. For the half year, after taxation of $453 million, profit jumped 29 percent to $1.14 billion from $883 million in 2022 after taxation of $361 million.
 Sales revenues rose 11 percent for the quarter, to $3.19 billion from $2.9 billion in 2022 and grew 10 percent for the year to date, to $6 billion from $5.5 billion in 2022.
After a brief one year dip in profit in the 2020 fiscal year, profit has been on a roll since and seems destined for a new record in the current fiscal year ending next March.
Management delivered an improvement in profit margin in the second quarter to 38 percent from 37 percent last year resulting in gross profit rising faster than sales with an increase of 13 percent, with a gross profit of $1.22 billion versus $1.08 billion in 2022. Gross profit for the half year soared 38 percent from 36 percent last year, resulting in an increase of 16 percent to $2.3 billion compared with $1.98 billion in 2022.
Operating expenses rose by just 4 percent in the quarter and half year to $394 million in the second quarter from $378 million in 2022 second quarter and in the half year to $755 million from $725 million in 2022. Finance cost declined in the quarter, to $23 million from $36 million in 2022 and from $15 million to $5 million for the six months period.
Lasco’s ICool drinks.
The operations generated Gross cash flow of $588 million and it was increased to $778 million after a reduction in funds previously tied up in working capital, additions to fixed assets of $309 million. After pumping $589 million into short term investments and $496 million in dividends the net cash position ended at $1.6 billion.
Current assets ended at $9.2 billion inclusive of trade and other receivables of $3.3 billion, cash and bank balances of $3.8 billion, while inventories were steady at $2 billion. Current liabilities ended at $1.86 billion. Net current assets was a solid $7.3 billion.
At the end of September, shareholders’ equity closed at $11.75 billion up from $9.9 billion at the end of September last year. There was no long-term borrowing, while short term loan was just $89 million.
Earnings per share for the quarter was 15 cents and 28 cents for the year to date. IC Insider.com computation projects earnings of 70 cents per share for the fiscal year ending March 2024 and 90 cents in 2025, with a PE of 6.7 times the current year’s earnings based on the price of $4.60 the stock traded at on the Jamaica Stock Exchange
Lasco’s products
Junior Market and the value is well down on the average for the market at 11.6, a clear indication of the potential gains ahead in the price. Net asset value ended the period at $2.85 with the stock selling at 1.6 times book value.
The company is in a healthy financial position to do a major acquisition, with no major loan commitment currently and a tidy wad of liquid funds, with more to come as profit increases in the rest of the fiscal year.
Buy and hold for a few years until growth in sales and profit slows considerably to single digits, investors should see a doubling in the stock price by next year June.
ICInsider.com gives the stocks Buy Rated seal of approval.
Paramount Trading profit drops 32%
Paramount Trading reported lower profits and revenues in the first quarter ending August following what the company states is the conclusion of a major six month contract for admixture supplied to the construction sector. Revenues declined by 28 percent to $426 million from $595 million the previous year. Profits fell by 32 percent to $65 million from $97 million the last year.
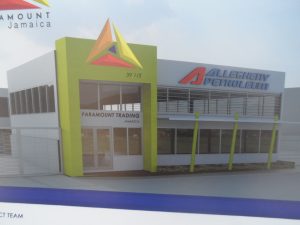
Paramount
ICInsider.com forecast earnings of 27 cents per share for the current fiscal year ending May 2024. The stock traded on the Jamaica Stock Exchange Junior Market at $1.48 on Wednesday is valued at a PE of 6 times earnings based on the projected earnings and trades at just under two times the book value of 77 cents.
Gross profit declined by $23 million in the current year, down 10 percent from $203 million generated in the previous year, resulting in a gross profit margin of 42 percent, up from 34 percent in 2022. The company also generated other operating revenues of $19 million, down from $29 million in the last year. Administrative costs declined 7 percent from $123 million to $115 million this year. Selling and distribution costs increased from $2.6 million to $4.6 million this year. Finance costs climbed from $11 million in 2022 to $14 million in the current year despite a reduction in the total amount of funds borrowed.
Earnings per share came in at just under four cents for the quarter compared to just over 5 cents in the previous year’s quarter.
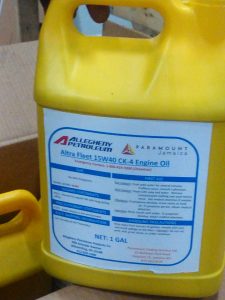
Container of Allegheny lubricant produced at the local plant
The company generated a positive cash flow of $77 million, which was reduced by an increase in working capital, amounting to $36 million and ended the year with cash funds of $144 million after paying $13 million toward a reduction in borrowed funds. At the end of August 2022, cash funds were $226 million and $121 million at the end of May this year.
Shareholders’ equity ended the period at $1.19 billion, up from $993 million at the end of August 2022 and long term borrowings were $115 million. Short term loans due to be paid within twelve months amounted to $338 million.
Current assets ended at $1.59 billion, and current liabilities were $902 million, resulting in net current assets of $683 million.
Profit to jump 40% in 2024 at Wisynco
Profit after tax for the first quarter ending September this year jumped 20 percent at Wisynco Group to $1.55 billion in the current year from $1.3 billion in 2022. Profit before tax also grew by 20 percent from $1.73 billion in 2022 to $2.1 billion, but profit is projected to jump 39 percent for the current year to $6.8 billion, ICInsider.com projections show.
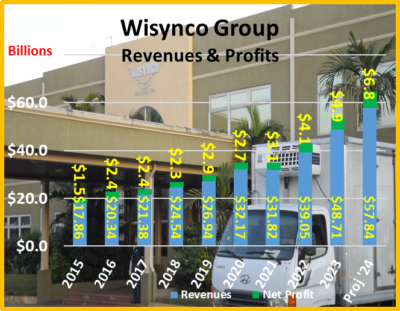 The profit performance resulted from a 15 percent rise in revenues from $11.95 billion in 2022 to $13.73 billion in the current year. Although revenues climbed 15 percent, gross profit increased by just 11 percent, from $4.3 billion in 2022 to $4.8 billion in the current year, as input cost climbed 17 percent to $8.93 billion from $7.6 billion in 2022.
Selling and distribution expenses rose 14.3 percent from $2.12 billion to $2.43 billion and administrative expenses popped nearly 13 percent from $455 million to $513 million. Finance income brought in $168 million versus $85 million in the previous year, but finance cost fell from $150 million to just $11 million, despite borrowings standing at $8.9 billion at the end of the period.
Earnings per share for the quarter rose to 41 cents from 35 cents last year and is projected to reach $1.84 for the full year and $2.40 in 2025. The stock, up 15 percent for the year to date, trades at a PE of 11.3 at the last traded price of $20.70 on the Main Market at the Jamaica Stock Exchange. The PE is slightly below the market average of 12.2.
A dividend of 23 cents per share, totalling $863 million, was paid in July, up from 22 cents per share, totalling $751 million in July 2022. In addition to the above dividends, 22 cents per share was paid in March 2023 and 20 cents in March 2022. The stock trades at 3.4 times a net book value of $6.05 at the end of September.
Cash flow generated for the 2023 quarter amounted to $2.2 billion and $1.9 billion in 2022. After working capital movements, operations delivered net flows of $2.4 billion, up from just $800 million in 2022
Wata is one of Wisynco’s known brands.
Shareholders’ Equity climbed to $22.7 billion at the end of September, up from $19 billion in September last year. Long term borrowings jumped to $2.8 billion from $790 million at the end of September last year and short term loans ended at $1.3 billion and $920 million in 2022. Some of the amounts borrowed are used explicitly to fund a significant expansion of its facilities currently on the way, so far consuming $1.8 billion in the quarter.
Net Current Assets closed the period at $13.5 billion, up from $11 billion at the end of September 2022 and emanate from Current Assets of $12 billion and $8.9 billion at the end of September last year and includes cash and investments of $10.2 billion and $7.7 billion in 2022. These amounts do not take into consideration $2.2 billion in longer term securities at the end of the quarter.
Current Liabilities ended at $7.4 billion at the end of September this year compared to $6.1 billion last year.
The group acquired the distribution rights for the Jamaican Teas products for sale locally. It will add around 2-3 percent to revenues in an entire year in addition to the expansion of the factory and warehousing currently underway and expected to come on stream by March 2024. The expansion will allow for increased production to meet demand they are unable to fill currently and provide capacity to expand exports.
Q3 profit triples at Transjamaican
Profits more than tripled in the September quarter, moving by 208 percent to $6.46 million from $2.1 million in 2022 at Transjamaican Highway, from a 15 percent increase in revenues over the September 2022 quarter to $19.2 million from $16.7 million. For the nine months, profit chipped in with a 327 percent surge to $17.5 million, up from $4.1 million in 2022, from a 17.8 percent rise in revenues to $55.4 million from $47 million in 2022.
Operating expenses fell from $9.9 million in the September 2022 quarter to $5.6 million and from $29 million to $16.6 million for the nine months to September. Administrative expenses rose from just $358,000 to $2 million for the quarter and year to date, it moved from $1 million to $6 million. Finance costs inched down from $3.75 million to $3.63 million and, for the nine months, from $11.2 million to $10.94 million.
Profit before tax amounts to $8.6 million versus $2.8 million in the previous year’s third quarter and year to date, it jumped to $23.2 million from just $5.8 million in 2022.
Taxation accounted for $2.1 million in the September 2023 quarter, up from $714,000 and for the nine months, to $5.77 million versus $1.7 million in the previous year.
Earnings per share reported for the quarter is 0.0005 US cents, up from 0.0002 US cents in 2022 and year to date, 0.0014 US cents versus 0.0003 US cents in the previous year. The full year results should be around 2 US cents per share.
The exceptional results emanate primarily from acquiring the majority shares in Jamaican Infrastructure Operators that lowered operating costs and raised revenues.
Gross cash flow of $35 million was generated, up from $17.9 million nine months to September in the prior year, resulting in $12.9 million in free funds available for use at the end of the fiscal period from $7.3 million at the end of September 2022 after repaying $5.4 million in loans, compared with $4.7 million for the same period in the previous year and after moving $17.7 million to restricted cash, up from $10.6 million in 2022, but before the payment of dividends.
Transjamaican Highway
Shareholders’ equity stands at $42 million, down from $51 million in September 2022 and $40 million at the end of 2022. Total current assets amount to $15.4 million, up from $8.4 million at the end of September 2022. Total current liabilities ended at $32.3 million, including a provision of $15 million for dividend payment and $7 million in 2022, the latter being a part of the $23 million in total current liabilities at the end of September 2022.
The Board of Directors approved an interim dividend of J$0.1866 per share paid on October 25, totalling J$2.33 billion. A dividend of $0.0855 per share amounting to J$1.069 billion was paid on October 25, 2022.
ICInsider.com projects 30 Jamaican cents per share earnings for the current year and 40 cents for 2024, which will be helped by the company earning income from the new leg of the highway from May Pen to Mandeville. The Jamaica dollar denominated stock traded at $2.58 on the Jamaica Stock Exchange on Tuesday, with a PE of 8.3 and is valued at 6 times 2024 earnings.
At the above price, the dividend yield is 7.23 percent per annum, but by 2024, the yield based on the present price will most likely be higher as the company increases the amount paid as profit grows.
In April with the price at $1.77, ICInsider.com placed the stock on a Stock to Watch list, since then the price is up 47 percent and 57 percent including the 2023 dividend.
Kremi ekes out small profit
Caribbean Cream reported revenues of $646 million for the August quarter this year versus $645 million in 2022, with the year to date revenues slipping to $1.25 billion from $1.257 billion in the previous year. Profit fell to $3.6 million in the August quarter from $7 million in 2022 and rose to $10 million for the six months from $8.5 million in 2022.
Caribbean Cream Kingston outlet
Improvement in production cost pushed gross profit up 10 percent to $390 million for the half year versus $354 million in 2022 and $205 million for the quarter to August this year, up 8.5 percent from $189 million in 2022. Cost savings were only realised in some areas as administrative expenses and finance costs climbed over 2022. Administrative expenses increased 6 percent to $158 million from $149 million, with finance costs climbing 60 percent to $24 million, from $15 million in the August 2022 quarter. For the half year, administrative costs rose 7 percent to $306 million from $286 million the previous year, while finance costs jumped 56 percent from $27 million to $42 million for the half year.
Finance cost associated with the expansion of the warehouse and building out of the cogeneration energy plant is being written off directly as a current expense rather than capitalising it, with the equipment as such, the reported profit over the past three years appears understated as a result of the treatment of this item. Accordingly, the 2023 full year’s profit should be closer to $70 to $80 million than the above figure, and the 2023 half year’s figure should be around $37 million.
Operations generated Gross cash flow of $77 million, growth in working capital and $206 million spent in addition to fixed assets offset by loan inflows net of outflows of $238 million, resulting in funds growing by $78 million during the six months.
 Considerable sums have been spent on plant and machinery to improve efficiency and, by extension, increase profit. Accordingly, $439 million was expended over the past year, bringing the gross amount in fixed assets to $2.7 billion from $1.7 billion at the end of February 2022. Most of the new expenditure went into equipping a new cold storage plant that has expanded freezing and cold storage capacity, with some spent on the cogeneration energy plant, which is intended to cut energy costs.
The company remains financially healthy, with current assets of $539 million, including trade and other receivables of $114 million, cash and bank balances of $145 million and inventories of $248 million, up from $183 million in August 2022. Current liabilities ended at $225 million and net current assets at $314 million.
At the end of August, shareholders’ equity amounts to $836 million, a rise from $807 million at the end of August 2022, with long term borrowings at $1.2 billion and short term loans at $43 million.
Earnings per share for the quarter was one cent and 3 cents for the year to date. IC Insider.com computation projects earnings of 55 cents per share for the fiscal year ending February 2024, with a PE of 7 times current year’s earnings based on the price of $3.95 the stock traded at on the Jamaica Stock Exchange Junior Market on Friday. The PE ratio compared with a market average of 10.7. Net asset value ended the period at $2.21, with the stock selling at just under two times book value.
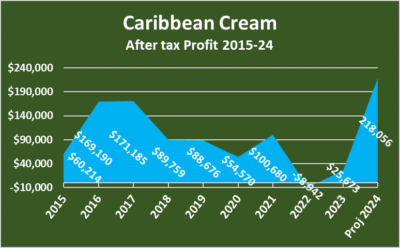
The company has a checkered profit history, as shown by the attached chart of profits, since 2015 and has struggled with increased costs since the disruption caused by COVID-19. The situation is worsened by the treatment of interest incurred to finance the new warehouse.
Profit bounce at Margaritaville
Margaritaville Turks was one company delivering improved revenues and profit for the 2023 period to August versus 2022, mostly reflecting improvement in tourism traffic to the Caribbean region.
 The company operates a restaurant solely in the Turks and Caicos Islands, and delivered revenues of US$1.8 million in the August 2023 quarter, up 27 percent from US$1.42 million in the prior year and produced gross profit of $1.33 billion this year versus US$1.033 million in the previous year.
Net profit came in at US$230,000 for the quarter against US$94,000 in 2022, even as administrative expenses climbed to US$979,000 from US$833,000 in the previous year, with depreciation charge being flat at US$69,000. Other operating expenses amount to US$44,000, with none incurred in the last year and finance cost was just US$6,000 for the current year, down from US$29,000 in the last year’s first quarter.
The operations generated a gross cash flow of US$300,000, but US$496,000 advanced to a related party, resulting in negative flows of US$74,000, reducing cash funds to a mere $49,151.
Margaritaville located in the Turks & Caicos Islands
Current assets ended the period at US$3.8 million and include US$2.7 million due from related companies, up from US$2.2 million in 2022. Current liabilities ended the period at US$1.96 million, from US$1.89 in 2022. Net current assets ended the period at US$1.8 million.
At the end of August, shareholders’ equity amounts to US$4.2 million, with long term borrowings at US$166,808 and short term at US$100,000.
Earnings per share for the quarter was 0.34 US cents, up from 0.14 US cents for the August 2022 quarter. IC Insider.com computation projects earnings of 2 US cents per share for the fiscal year ending May 2024, with a PE of 6.5 times the current year’s earnings based on the price of 12.7 US cents the stock traded on the Jamaica Stock Exchange, with an average PE of 12. Net asset value ended the period at 6 US cents, with the stock selling at two times book value.
AS Bryden & Sons JSE listing imminent
AS Bryden & Sons Holdings Ltd seems set to be the next listed company on the Main Market of the Jamaica Stock Exchange. The company, through its listing agents NCB Capital Market, posted an abridge financial statement on the JSE website on Monday, a sign that the listing will be in days, so far, there are no signs that is will list in Trinidad at the same time.
 The company has shareholders” equity of TT$576.2 million of Jamaican J$13.25 billion as of June 2023 with total borrowings exceeding shareholders equity with long term loans of TT$285 million and medium term borrowings about two TT$534 million.
Current assets stand at TT$1.19 billion, with inventories and trade receivables amounting to TT$976 million and current liabilities at TT$576 million.
Sales revenue for the six months to June amounts to TT$1.18 billion with gross profit of TT$304 million, for a 25.7 profit margin. Pretax profit amounts at TT$74 million an after tax profit of TT$56 million.
Massey Holdings is trading around 10 times current year’s earnings if this is achieved by Bryden it would value the stock at J$12 billion or just a bit below book value.
The company focuses is on the distribution of fast-moving consumer goods (FMCG) and the sales divisions are grouped into three teams specialising in Premium Beverages, Food & Grocery, and Hardware & Housewares.
Seprod owns 54 percent of Bryden, which was acquired in 2022.
Carib Cement Q3 profit jumps 60%
Caribbean Cement recorded a solid 48 percent increase in pretax profit to $2.6 billion, from $1.7 billion in 2022 for the third quarter, with the nine months at $5.6 billion, marginally lower than the $5.8 billion reported in 2022. After taxation of $617 million in the third quarter and $517 million in 2022, profit ended at $1.94 billion, up a healthy 60 percent from $1.2 billion in 2022. For the nine months of 2023, profit after accounting for taxation of $1.5 billion and $1.86 billion in 2022 ended at $4.39 billion, from $4.25 billion in 2022.
 Earnings per share for the quarter was $2.28, up from $1.42 in 2022 and $5.15 versus $5 for the year to September.
Revenues jumped a robust 13.4 percent to $7.0 billion for the third quarter to September this year over the $6.2 billion in the 2022 period and were up 8 percent to $21.27 billion for the nine months to September 2023 compared to $19.68 billion in 2022.
While revenues were racing ahead, cost of sales remained flat during the third quarter at $3.48 billion against $3.42 billion in the September 2022 quarter, but it rose 18 percent in the year to date period from $10.8 billion in 2022 to $12.77 billion. Gross profit in the quarter jumped 28 percent from $2.75 billion to $3.5 billion in the September quarter and, for the year to date, declined from $8.85 billion in 2022 to $8.5 billion. Administrative expenses rose a significant 36 percent from $225 million in the September 2022 quarter to $304 million in 2023 and popped 17 percent from $695 million in the year to September 2022 to $811 million in 2023.
Notwithstanding the increase in revenues, distribution costs fell from $433 million in the September 2022 quarter to $354 million in the current year and moved from $1.2 billion down to $1.1 billion in the nine months to September.
Other expenses, mainly fees paid for management and royalty to the parent company that was flat year over year, rose to $254 million in the September quarter from $166 million in the prior year, and for the nine months, it was marginally down to $669 million from $680 million in the preceding nine month period.
Finance costs for the September quarter fell to $48 million, down from $154 million in the 2022 quarter and for the nine months, from $430 million to $142 million in the current fiscal year to September.
 In relation to the cash flows, “Net cash provided by operating activities” was $5.7 billion for the nine months and $2.46 billion for the quarter. The cash flow generation during the quarter and the available cash at the beginning of the period have allowed the Group to invest $4 billion during the nine months of the year and $2 billion during the second quarter, leaving the company with $639 million in cash and bank balance at the end of the period.
As a result of the excellent performance, the company paid a dividend of $1.8976 per share, amounting to $1.6 billion, a 37 percent rise over the $1.17 billion paid in 2022 and resulting in Shareholders’ equity ending at $22.76 billion at the end of September, a sizable improvement over the $18.75 billion at the end of September 2022 and $20 billion at the end of December last year.
Total current assets ended at $10.67 billion as of September 2023, compared with $7.47 billion in 2022, with inventories being $4.68 million and $4.53 billion in 2022. Receivables from related parties amounted to $4.1 billion, up from $1.1 billion in 2022, with the 2023 balance including a deposit investment account of J$4 billion, the equivalent of US$26 million in CEMEX Innovation Holding Limited, which generates interest at a rate equal to the Western Asset Institutional Liquid Reserves Fund rate plus 30 basis points on a daily basis.
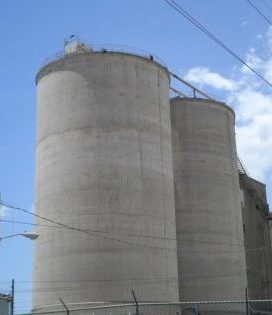
Caribbean Cement silos
Total current liabilities stood at $7.1 billion, down from $8.2 billion in 2022. There was only $228 million in other financial obligations outstanding at the end of September, down from $1.89 billion at the end of September 2022.
Caribbean Cement “implementation of its requisite business strategies has been paying dividends as the company continues with expansion and the achievement of significant milestones. It also included the company’s ability to adequately supply the local market, having enough spare capacity to export 3,500 metric tonnes of high-early strength cement to the Turks and Caicos Islands. In the next quarter, the company expects to build on its current achievements and maximise its performance as it remains optimistic about its future. The company will also continue to undertake its flagship social impact initiatives of installing concrete pavements in certain communities across the island,” the company stated in their commentary on the results.
With ICInsider.com projected earnings at $7, the stock still has the potential to go higher from the current price of $50.32, with the current PE at just 7 times 2023 earnings compared to an average of 12 for the market. Not to be ignored are a few developments that augurs well going forward. The continuing expansion to hotel rooms and road expansion should ensure continued demand for cement for several years ahead. Immediately, the September quarter profit suggests that earnings in 2024 could exceed $9 per share if the current trend continues into 2024.
Profit at Dolla jumps 59% in Q3
Microlender Dolla Financial reported results for the quarter ending September, with profit rising a solid 59 percent to $102 million after tax, from $70 million in the prior year’s September quarter and a profit of $328 million for the nine months to September a b 74 percent increase over the $188 million generated in 2022 for the similar period.
 Profit for the September quarter was marginally lower than the June quarter. Still, revenues from loans of $300 million in the September period were slightly higher than the $294 million in the June quarter.
After provision for loan impairment losses, net interest income climbed 65 percent to $243 million in the quarter, from $150 million in the prior year and by 75 percent to $724 million for the nine months versus $414 million in 2022.
Administrative costs climbed faster than revenues, with a jump of 83 percent for the quarter to $150 million and the nine months by 92 percent to $420 million.
Loans receivable net of provision for loss amount to $2.6 billion, an increase of $1.5 billion or 125 percent over September 2022, and grew by just $69 million over the June quarter. Funds borrowed amount to $1.85 billion and increased $100 million over the June quarter. Funds on hand are almost $147 million, with most available for lending.
The company needs to take on additional debt to maintain the hectic growth in the loan portfolio and profitability going forward. The significant acquisition of shares in the company by Mayberry Investments and Supreme Venture should provide them with a constant potential source of funding to maintain the growth in the loan portfolio, supportive of an annual increase in profits going forward.
 According to the company’s commentary on the results, “business loans accounted for 82 percent of the total loan portfolio, while personal loans accounted for the remaining 18 percent. Secured loans constituted 81 percent of the portfolio, with unsecured loans making up the remaining 19 percent. The collateralised loan strategy has proven instrumental in maintaining the loan portfolio quality, with non-performing loans holding steady at 9 percent, remaining within budgeted expectations and below the sector average.”
As of September, shareholders’ equity stood at $938 million, up from $715 million at the end of September last year.
Profit resulted in earnings per share of 4 cents for the quarter and 13 cents for the year to date. IC Insider.com computation estimates earnings of 20 cents per share for the fiscal year ending December 2023, with a PE of 12.8 times the current year’s earnings based on the price of $2.56, the stock traded on the Jamaica Stock Exchange Junior Market. The PE ratio compares with an average of 10.9 for the Junior Market but less than 19.5 times the top 9 stocks. Net asset value ended the period at 38 cents, with the stock selling at 6.6 times book value.