Carib Cement hit by exchange loss

Caribbean Cement traded at $45.200 on Tuesday.

Sale revenues at Caribbean Cement rose 6.7 percent for the quarter, to $4.46 billion from $4.18 billion in 2017 and rose 7.9 percent for the year to date, to $13.2 billion from $12.25 billion in 2017.
A $464 million foreign exchange loss hit the results for the September quarter pulling the strong 44 percent increase in operating profit to $1.2 billion from $836 million, into lower net profit of $305 million than $748 million for the prior year’s period. For the nine months to September, profit fell 28 percent to $1.3 billion from $1.8 million in 2017.
Energy cost climbed by $233 million in the quarter and $342 million year to date but other operating cost declined, with the repurchase of the mill and kiln, previously leased from Trinidad Cement with only $213 million was incurred in the third quarter versus $1.1 million in 2017. For the nine months $1.57 million was incurred compared to $3.3 billion. On-the-other-hand finance cost excluding foreign exchange loss rose to $227 million up sharply from just $11 million in 2017 in the quarter and $299 million versus $4 million year to date. Depreciation and amortisation cost rose to $342 million from $132 million in 2017 and for the nine months to $808 million from $400 million in 2017. The net effect is that the company enjoyed a savings of $500 million per quarter or $2 billion per annum as a result of the buy of the lease, but virtually none of this, benefited shareholders.
Earnings per share came out at 39 cents for the quarter and $1.54 for the nine months and should end the fiscal year ending to around $3.50, as the company reverses the foreign exchange loss in the December quarter and picks up some gains, as well as increased revenues resulting from a price increase of just over 4 percent, effective on October 22.
Carib Cement could earn $5.30 in 2019.


But IC Insider.com is forecasting a jump in earnings for 2019 around $5.30 per shares, as the plant upgrades is completed and commissioned, allowing for the elimination of costly imports that negatively impacted cost in 2018 and will see them moving back into exports.
Gross cash flow brought in $849 million but growth in receivables, inventories, addition to fixed assets, loan repayment and increased payables resulted in negative total flows thus reducing the cash on hand to $468 million. For the nine months the operations brought in $2.6 billion but working capital needs and capital transactions saw cash funds reduced from $1.67 billion to $468 million.
The sharp changes in funds is due to the repurchase of equipment that was previously leased that drove fixed assets to $23 billion from $7.7 million in 2017 and borrowing to $12 billion.
Shareholders’ equity stood at $10.26 billion with borrowings at just $12 billion and net current assets ended the period was negative $1 billion.
The stock traded at $45.20 on the Jamaica Stock Exchange with a PE ratio of 13 times 2018 earnings and sits around the centre of the market valuation. the price could double in 2019. Net asset value is $12 with the stock selling at almost 4 times book value.
Going forward, the company results should be helped from the improvement in the Jamaican economy and growth that is likely to flow from the construction sector including buildings and roads and bridges as well as from increased exports. There is also focus on cost reduction with the high energy cost being the next centre of attention.
Carib Cement chops $2B from lease cost

Jamaica Caribbean Cement Company slashed the cost formerly associated with leasing of Kiln 5 and Mill 5, from Trinidad Cement after acquiring direct ownership of the assets by $2 million per annum.
Data disclosed by Jamaica’s sole cement producer in their nine months interim report showed that excluding foreign exchange gains or loss that there was a $500 million savings in the overall cost associated with the two items formerly leased.
The equipment lease ended in April 2018 when both parties agreed to the ending of the arrangement leading the Jamaican company agreeing to purchase same. The interim figures show finance cost excluding foreign exchange loss rose to $227 million up sharply from just $11 million in 2017, in the quarter and $299 million versus $4 million year to date. Depreciation and amortisation cost rose to $342 million from $132 million in 2017 and for the nine months to $808 million from $400 million in 2017. The net effect is that the company enjoyed a savings of $500 million for the quarter or $2 billion per year.
A $464 million foreign exchange loss hit the results for the September quarter pulling the strong increase in operating profit of 44 percent to $1.2 billion from $836 million into lower net profit of $305 million than the $748 million generated for the prior year’s period. For the nine months to September, profit fell percent to $1.3 billion from $1.8 million in 2017.

Margaritaville flat profit, growth coming

Margaritaville Turks traded 531,220 shares at 20 US cents on friday

Margaritaville posted flat profit for the first quarter of the May 2019 fiscal year, with net earnings of US$290,815, down slightly from US$296,412 in 2017.
Revenue was also down moderately to $1.8 million, from $1.86 million in the 2017 period, but growth should be coming when Carnival Lines expands the port facilities in Turks and Caicos in 2019.
Cost declined modestly, with direct expenses falling to $471,386 from $483,803 in 2017, resulting in a gross profit margin of 74 percent, while administrative and other cost declined to $1.057 million, modestly down from $1.082 million in the prior period in 2017.
Earnings per share came in at 0.43 cents. For the full year to May 2018, earnings per share was 1.58 cents resulting from net profit of $1.067 million. The stock trades on the Jamaica Stock Exchange US market at 25 US cents at a PE of 16.
Equity capital stood at $5 million while current assets amounted to $2.7 million with current liabilities of $1.1 million.

Ian Dear Chairman

Going forward Chairman Ian Dear, told IC Insider.com that Carnival Line is expanding the docking facility in Turks and Caicos Islands that will allow much larger ships to dock and will result in increase in the number of passengers landing and will bring more business for the company. According to Dear, the ships currently in use can accommodate up 3,000 passengers plus crew but the newer ships will carry 8,000 passengers and they could have two of these ships on a typical day. The expectation that the first ship should dock in Turks next year. The coming on stream of the increased business will see Margaritaville adding another restaurant, with construction to commence shortly after carnival advises them of date the news ships will commence operations.

Iron Rock’s first profitable quarter

Iron Rock hits 52 weeks’ high of $4.07 on Friday.

Improvement in its bottom-line of Iron Rock Insurance continued into the September quarter, with profit of $1.1 million, the first quarterly profit in its short history. For the nine months’ period, the company suffered a loss of just $7.6 million down from $60.4 million in 2017.
For the quarter, gross premium income (GPI) increased to $99.4 million from $83.9 million in 2017 with net premium written of $41 million and net earned premium of $48.3 million. For the nine months of 2018, GPI grew 48 percent to $382 million, up from $257 million in 2017 and net earned premium increased 272 percent to $129 million from just $47 million in 2017.
Operating expenses inched up to $36.5 million in the quarter from $35 million in 2017 and grew 11 percent to $111 million from $100 million in 2017. Insurance claims jumped to $23 million from $12 million for the quarter and $61 million for the nine months, from $34 million last year.
Other income totaled $13.5 million for the quarter, from $10 million previously and $35 million for the period to September, versus $24 million. The company is projected to end the year with an overall profit.
Shareholders’ equity now stands at $525 million, down from $512 million at the end of September last year. Cash and investments now amount to $617 million, while Insurance liabilities, claims and other payables amount to $373 million.
The stock now trades on the Junior Market of the Jamaica Stock Exchange at $4.80.

More profits & stocks for WI Tobacco

Watch Witco stock in coming days

Pretax profit increased 10.2 percent at Trinidad based West Indian Tobacco to $438.7 million, for the nine months to September 2018, over the similar period in 2017 while Profit after tax increased 10 percent to $303 million over 2017, from increased revenues of 9.5 percent to $862 million from $787 million.
For the September quarter, revenues grew 6.4 percent to $292 million from $274 million and resulted in profit after tax rising 12.5 percent to $109.6 million. The company benefitted from improved gross profit margins in both periods, with 65 percent in the quarter versus 61.5 percent in 2017, while the nine months improved to 61.8 percent from 60.44 percent in 2017. Distribution cost more than doubled to $8.4 million in the quarter from $3.5 million in 2017 and rose sharply from $9.9 million in 2017 to September to $18.7 million. Administrative and other operating expenses declined for the quarter to $18 million from $23.7 million while the nine months rose from $68 million to $77 million.
Profit for the 2018 fiscal year, declined to $380 million from $515.5 million in 2016 as increased taxation on profits and cigarettes negatively impacted sales and the results.
Earnings per share for the quarter amounted to $1.30 and $3.60 for the nine months, with the full years likely to exceed $5 and resulting in a PE ratio of 18 times earnings.
The stock will be split into three shares for each existing one held by shareholders and will make the price and liquidity going forward, more attractive for investors. The stock last traded at $90 on the Trinidad and Tobago Stock Exchange.
The Board approved the payment of a third interim dividend of $1.17 per ordinary share payable on 26 November 2018, to shareholders of record at close of business on November 5.

Profit jumps 56% at Knutsford Express

Knutsford Express posted strong gains in profit for Q1.

After more than a year when Knutsford Express traded at elevated levels, things are on the mend but investors in the stock may still have to wait to see their investment paying off with much increase in the stock price.
The company’s latest results is encouraging that investors’ wait for full recovery of the price may not be far away. Profit jumped 56 percent in the August quarter to $88 million from $57 million in 2017 from Sale revenues that rose 23 percent for the quarter to $293 million from $237 million in 2017.
The company still has not provided investors with relevant information to be able to see what gross profit margin they are enjoying to better determine how well the operation is being managed.
Expenses rose at a slower pace than revenues, climbing 16 percent to $211 million from $181 million. Earnings per share rose to 18 cents for the quarter, up from 11 cents on 2017. IC Insider.com is forecasting 75 cents per share. The stock traded at $11.5 on the Junior Market of the Jamaica Stock Exchange, with a PE ratio of 15 times 2019 earnings.
Gross cash flow brought in $108 million but growth in receivables, inventories, addition of $61 million to fixed assets net cash flows used up just $4 resulting in with cash and bank balances of $134 million plus short term investments of $96 million. At the end of August, shareholders’ equity stands at $714 million with borrowings at just $71 million. Net current assets ended the period $280 million well over Payables of $34 million.

Mayberry Equities profit rises

Mayberry Investments

Strong growth in the Jamaican stock market drove the net assets of Mayberry Jamaican Equities to $15.6 billion at the end of September from $7.4 billion at September last year and from $8.9 billion at the end of December.
Mayberry reported an after-tax profit of $250 million for the September 2018 quarter, up sharply from $65 million in 2017. For the year to September this year, profit rose to $690 million from just $84 million in 2017 but a strong increase of $615 million in the September quarter and $1 billion year to date were the main drivers of the increased results in 2018. The performance resulted in Earnings per share of 21 cents for the quarter and 57 cents for the nine months.
Total comprehensive income for Q3 amounted to $4.25 billion, compared to $295 million for the corresponding quarter of 2017 and the booking of $6 billion for the nine months period reflecting gains from stocks held in the portfolio.
Net Revenues increased to $658 million from just $23 million in the 2017 quarter and is up to $1.26 billion for the nine months to September from a mere $32 million for the similar period in 2017.
Unrealized gains on investment, accounted for the bulk of the income while dividend Income amounted to $69 million in the quarter versus $29 million in 2017 and for the year to September, $296 million versus just $65 million in 2017. The addition of Supreme Ventures to the portfolio would have contributed in a major way to the increase.
Operating expenses increased to $390 million in the quarter from $8 million in 2017, for the year to date it moved to $548 million from $36 million in 2017 due to incentive and management fees for Investment management services and, also, Legal and Professional fees for a corporate loan of $2.2 billion acquired to expand the equity portfolio.
At the end of the quarter the company had cash funds of $1.37 billion and investments of $16.95 billion and amounts due creditors of $482 million and Net Book Value per share moved to J$13.01, at September 30 but fell by October 5, 2018 to $11.96, the company reported on the website of the Jamaica Stock Exchange.
The company’s portfolio comprises 31 securities including, Lasco Financial Services, Caribbean Producers, Blue Power, Iron Rock Insurance and Supreme Ventures.

Prestige profit slips & slides

Prestige Holdings brand – TGIF

Profit at Trinidad’s fast food franchise operators, Prestige Holdings fell a sharp 35 percent to TT$7.7 million for the quarter ending in August, compared to $11.8 million for the similar period in 2017 as economic pressures continued to affect the Twin island state of Trinidad & Tobago, where the bulk of the income is generated.

The operation includes, Prestige Holdings’ of KFC, Pizza Hut, Subway and Starbucks, Weekenders Trinidad Limited (TGI Fridays Trinidad) and Prestige Restaurants Jamaica, (TGI Fridays Jamaica).
Revenues slipped in the quarter to $268 million from $273 in 2017 quarter, dragging down gross profit to $90 million versus $95 million in the 2017 period, as cost of sales remained flat at roughly $178 million in both periods.
For the nine months to August, revenues increased a mere 1 percent to $790 million and profit after tax declined 24 percent to $21 million, from $27.7 million in the previous year. For the 2017 fiscal year, the company reported $32.9 million in after tax profit, from revenues of $1.04 billion.
Earnings per share for the nine months ended at 34 cents compared to 45 cents for the same period in 2017. The results were generated from an average number of 123 restaurants, the company stated in a release with the quarterly results.
Other operating expenses were flat in the quarter but rose moderately, by just $5 million to $170 million for the nine months. Administrative expenses edged up slightly, in both the quarter and year to date period, to $20.6 million from $20 million and from $61 million to $63.7 million respectively.
According to the Chairman, Christian Mouttet in his report to shareholders, “our less than stellar performance for the nine months of 2018, as mentioned in my Half Year Report, has been driven primarily by higher costs, a still recovering local economy and consumers who are very price and value sensitive. As mentioned then, we are implementing initiatives and making changes to our operations that over time will improve our performance and strengthen our business. Additionally, we opened our tenth Pizza Hut restaurant in Princes Town on 1 October 2018.”
“We do not anticipate any significant changes in the macroeconomic environment in the short term and expect to finish the year broadly in line with the previous nine months.”
The Board approved an interim dividend of 12 cents per common share (2017 – 14 cents) to be paid on October 31.
Prestige closed the period with shareholders’ equity of $290 million, Current assets of $131 million and Current liabilities of $131 million. Non-current liabilities amounted to $54 million. The stock closed at $7.52 or a PE ratio of 17 on the Trinidad & Tobago Stock Exchange on Monday.

Everything Fresh down but not out

Everything Fresh is one of a hand full of initial public stock offers to be selling below the IPO price months after the issue. The stock that was over priced has only been partially helped by a big jump in 2018 half year profit.
The fall in the price was due to over pricing the initial offer and failure to provide more up to date information on the 2018 performance to the time of the IPO and to address developments with the margins. Even with improved results, the stock remains one of the higher priced units on the Junior Market, at a PE of 14 times this year’s pretax earnings and is in line with the market’s average.
Boosted by a big jump in profit margins, earnings after tax jumped 180 percent in the June quarter, to $26.5 million from $9.5 million in 2017. For the six months to June, profit climbed 99 percent to $38.6 million from $19.4 million in 2017. For the next five years, profit will be free of corporate taxes and in the second five years will pay taxes at half the regular rate.
Sales revenue rose 9.7 percent for the quarter, to $494 million from $451 million and increased 6 percent for the half year, to $969 million from $915 million in 2017.
Improvement in profit margin in the first half of the year that grew from 8 percent to 11 percent, increased further to 13 percent in the June quarter and was the major contributor for the sharp increase in profit. The Chairman, Gregory Pullen informed IC Insider.com, that the company took a deliberate decision in 2017 to go after certain clients with an introduction of low margins, with the expectation that they would be able to enjoy higher margins in 2018 onwards.

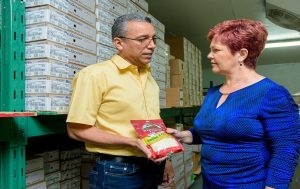
Everything Fresh two major owners and directors, Mr. & Mrs. Pullen.

The effect of the changes, operating profit rose 84 percent in the quarter, to $66 million from $36 million and increased 49 percent for the year to date, to $108 million from $72 million in 2017.
Sharp increase in administrative expenses by 38 percent to $28 million in the quarter and by 30 percent in the six months period to $54 million, kept the growth in the top line from filtering fully into profit. Marketing expenses associated the public of share issue added to cost in the period. Finance cost rose in the quarter, to $5 million from $4.3 million in 2017 and from $8.7 million to $9.3 million for the six months.
Earnings per share before tax came out at 5 cents for the quarter and 8 cents for the six months and should end the year at 15 cents for PE of 14 times 2018 earnings and 10 times 2019 projected earnings of 20 cents per share. The stock traded at $2.10 on the Junior Market of the Jamaica Stock Exchange on Friday.
Gross cash flow brought in $48 million but changes in working capital and inflows from the issue of shares, resulted in $213 million of cash funds as of June. A large portion of the share issue proceeds was received after the end of the quarter, the chairman’s report to shareholders stated.
At the end of June, shareholders’ equity climbed to $651 million from $225 million in 2017. Borrowings stood at just $107 million. Net current assets ended the period at $614 million inclusive of trade and other receivables of $503 million and cash and bank balances of $213 million. Current liabilities ended the period at $207 million.
The company is looking at three meat processing facility locally with a view to acquiring one and expects that discussions will conclude by the end of this year or early in 2019. The plan is to enable the manufacturing of products by them to sell directly to its clients at more competitive prices.

Sales jump sharply at Main Event

Main Event backed with IC BUY RATED status

Growth in revenues while not an exact proxy for increased profits, is often a very good indicator of greater gains ahead. That may be exactly what is happening at the Junior market listed Main Event.
The results for the nine months to July show strong sales growth but flat profits. Revenues for the July quarter surged nearly 26 percent to $364 million, but profit fell 7 percent to $24.5 million from $26.3 million in 2017. For the nine months to July, profit was up just 4 percent to $105.5 million that flowed from a 13 percent rise in revenues to $1.07 billion, compared to net income of $101 million in 2017.
The company incurred increased cost as it seeks to expand its service offerings. The results to date suggest that the full year earnings will not vary much from the 2017 full year results of 37 cents. But 2019 could be a blow out year for them, if revenue growth seen so far for this year, continues into 2019.
Profit margin in the first half of the year, was held to the same level as in 2017, at 48 percent and declined in the July quarter to 45 percent from 49 percent in the 2017, the impact, operating profit rose just 15 percent in the quarter to $164 million from $143 million but fell to 14 percent for the year to date, to $512 million from $447 million in 2017.
Administrative expenses rose 20 percent to $111 million in the quarter and increased 15 percent in the nine months period to $311 million. Marketing and sales expenses increased by 44 percent to $15 million for the nine months. Depreciation rose 49 percent to $24 million in the quarter and increased 29 percent in the nine months to $69 million, an indication of increased capital spend to accommodate expansion and increased income. Finance cost was flat in the quarter, at $5.2 million and rose just 5 percent to $13.6 million for the nine months.
Earnings per share came out at 9 cents for the quarter and 37 cents for the nine months and should end the fiscal year around 40 cents. For 2019 earnings should be in the order of a string increase to 75 cents.
“Performance has been negatively impacted by write downs on trade receivables to align to reporting standard, IFRS 9, continued start up expenditure for new service offerings and cost with higher head counts and incentive compensation,” the Chairman Ian Blair and Chief Executive Officer reported to shareholders in their commentary accompanying the quarterly.
Gross cash flow brought in $175 million but growth in receivables, inventories, addition to fixed assets of $160 million, offset by net loan inflows and increased payables resulted in net cash flow ended at a negative $63 million and leaving $29 million in cash at the end of July. Shareholders’ equity stood at $551 million with borrowings at just $185 million, including amounts due to related parties. Net current assets ended the period at $141 million, inclusive of trade and other receivables of $304 million, cash and bank balances of $29 million. Current liabilities amounted to $209 million inclusive of short term borrowings.
The stock traded at $5.50 on the Junior Market of the Jamaica Stock Exchange with a relatively low PE ratio of 7.3 times 2018 earnings and is elevated to BUY RATED status.